Un sector público más digital para una América Latina más productiva

Jens Arnold, Aida Caldera, Priscilla Fialho, Paula Garda, Alberto González Pandiella, Michael Koelle, Alessandro Maravalle, Dimitris Mavridis, Claudia Ramírez y Adolfo Rodriguez-Vargas, Departamento de Economía, OCDE

La última edición de las Perspectivas Económicas de la OCDE ofrece un diagnóstico realista pero esperanzador sobre las economías latinoamericanas. Aunque el entorno global sigue siendo complejo, marcado por tensiones comerciales y geopolíticas, la región tiene oportunidades claras para fortalecer el crecimiento económico a través de las reformas estructurales. Una de las más prometedoras: la transformación digital del sector público para simplificar trámites, reducir costos y mejorar la eficiencia regulatoria.

América Latina muestra resiliencia pero con desafíos persistentes

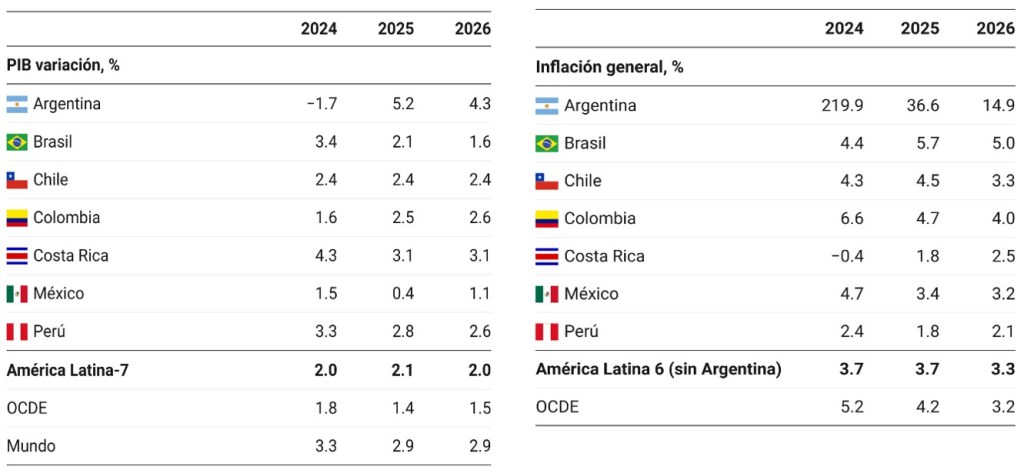
En línea con la evolución de la economía global, tras un crecimiento proyectado del 2.3% en 2025, se prevé una ligera desaceleración al 1.9% en 2026, antes de repuntar al 2.4% en 2027 en las  siete principales economías de la región. Factores como la consolidación fiscal en muchos países de la región, necesaria pero restrictiva, y una elevada incertidumbre política y económica seguirán afectando la demanda interna, la inversión y las exportaciones, principalmente en 2026.

Cuadro. Perspectivas económicas para los países de América Latina
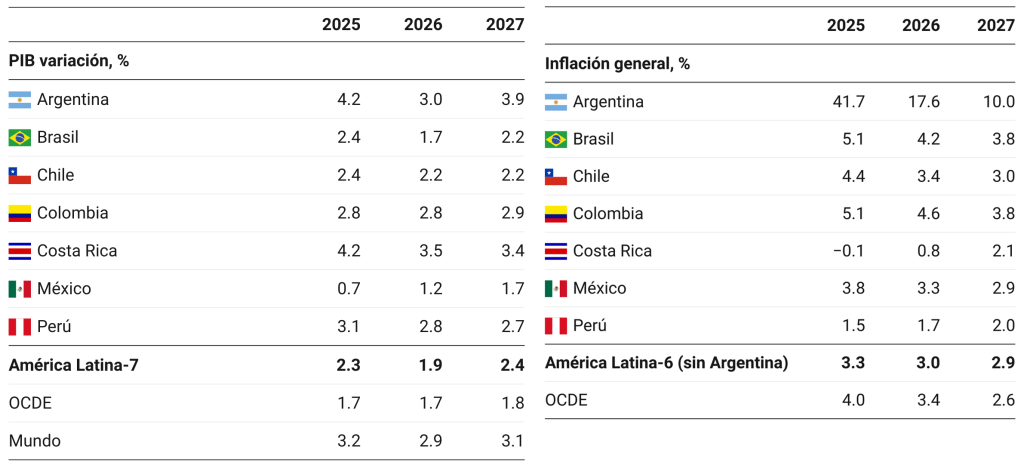
Nota: América Latina 7 es la media ponderada por el PIB a valores de paridad del poder de compra de los 7 países en la tabla para el PIB. América Latina 6 es la media simple de los países incluidos en el cuadro para la inflación excluyendo a Argentina.
Fuente: OCDE Perspectivas Económicas No. 118, diciembre de 2025.

La inflación en los últimos meses ha sido más persistente de lo esperado. En la mayoría de los países se prevé que en 2025 la inflación se mantenga por encima de las metas de los bancos centrales, convergiendo gradualmente hacia las metas en 2026 y 2027. Excepciones son Perú, donde la inflación está controlada hace un año, Costa Rica, que mantiene una inflación negativa en 2025, y Argentina, en donde la elevada inflación seguirá reduciéndose gracias a una combinación de consolidación fiscal y política monetaria restrictiva. La mayoría de los países tendría que mantener una política monetaria prudente basada en datos y orientada a devolver la inflación a sus metas sin generar presiones innecesarias sobre la actividad. En este contexto, los bancos centrales deben mantenerse atentos a la evolución del comercio global, las condiciones financieras, las expectativas de inflación y la orientación de la política fiscal. Al mismo tiempo, será clave que la consolidación fiscal siga avanzando con medidas concretas y más ambiciosas, dada la elevada deuda pública y la necesidad de asegurar su sustentabilidad en un entorno externo incierto y con elevados costos de financiamiento.

Los riesgos económicos están sesgados a la baja:

  • Incertidumbre global derivada de tensiones comerciales y geopolíticas, junto con la incertidumbre política en algunos países de la región asociada al ciclo electoral u otros factores internos, podría afectar negativamente a la inversión y las exportaciones, con repercusiones adversas sobre el crecimiento económico.
  • Desviaciones fiscales podrían subir el coste del servicio de la deuda, socavar la confianza, frenar la inversión y generar presiones inflacionarias.
  • Persistencias inflacionarias limitarían el espacio para reducir las tasas de interés, afectando las condiciones financieras y desincentivando el consumo y la inversión.

Sin embargo, también hay riesgos al alza: una reducción de las barreras comerciales o redirección del comercio hacia la región y una menor incertidumbre geopolítica podrían fortalecer el consumo, la inversión y el consumo.

Aprovechar la revolución digital para avanzar hacia marcos regulatorios más simples y eficientes

El capítulo especial de las perspectivas económicas subraya la necesidad de avanzar hacia marcos regulatorios más simples y eficientes. En este contexto, la transformación digital del sector público emerge como una herramienta clave para facilitar esta simplificación regulatoria, reduciendo la carga administrativa y modernizando procesos normativos. Una implementación eficiente de la gobernanza digital representa una gran oportunidad para América Latina, tanto para mejorar la eficiencia del gasto público y la transparencia, como mejorar el crecimiento económico al impulsar la productividad de las empresas, históricamente baja. Un gobierno digital bien implementado permite:

  • Ofrecer servicios públicos más rápidos, sencillos e inclusivos.
  • Reducir costos administrativos y simplificar trámites gubernamentales, mejorando el entorno de negocios, lo que cual se puede traducir en ganancias significativas de eficiencia al reducir costos y tiempos de espera, ampliar la cobertura y fomentar la competitividad de las empresas. 
  • Fortalecer la transparencia y rendición de cuentas facilitando el acceso ciudadano a la información, la detección de irregularidades, contribuyendo a prevenir el fraude.

Los indicadores de la OCDE muestran que países como Colombia y Brasil lideran el gobierno digital en la región. Colombia ha avanzado significativamente con la puesta en marcha de plataformas en línea, aplicaciones móviles para trámites gubernamentales y datos abiertos, mientras que Brasil ha sido pionero en servicios como el voto electrónico, las declaraciones de impuestos digitales, y más recientemente la centralización del acceso a cientos de servicios y la identificación digital. No obstante, muchos otros países siguen rezagados (Figure 1).

¿Qué se necesita para una transformación digital exitosa del sector público?

Para lograr una transformación digital exitosa en el sector público, los gobiernos de América Latina aún enfrentan retos importantes y requieren redoblar esfuerzos para lograr:

  • Infraestructura digital robusta con cobertura suficiente y sistemas interoperables entre niveles de gobierno para garantizar que todos puedan acceder a los servicios digitales.
  • Coordinación efectiva entre gobiernos centrales y locales. En muchos países de la región, existe una gran brecha en el uso de herramientas digitales entre las instituciones públicas centrales y las locales.
  • Autoridad política clara para liderar la transformación.  El reciente impulso a la agenda digital en México, incluida la creación de la Agencia de Transformación Digital y Tecnológica, es un ejemplo destacado de cómo dotar de liderazgo institucional a estos procesos
  • Regulación ágil y flexible para tecnologías emergentes como la inteligencia artificial.
  • Confianza ciudadana. Garantizar la privacidad y la seguridad de los datos es esencial para que los ciudadanos confíen y utilicen los servicios públicos digitales, aprovechando así al máximo el potencial de la digitalización. Además, publicar datos en formatos reutilizables facilitaría el acceso a información pública completa y confiable, mientras que impulsar la colaboración entre gobiernos, sociedad civil, universidades y empresas, aceleraría la experimentación y mejoraría el impacto de la gobernanza digital.

Casos exitosos como el de Estonia demuestran que una gobernanza digital bien implementada puede generar ahorros al gobierno equivalentes al 2 % del PIB anual.

Digitalizar para transformar

La digitalización del sector público no solo mejora la eficiencia del gasto público. También genera beneficios que se extienden a toda la economía, al elevar la productividad, reducir cargas administrativas para ciudadanos y empresas, facilitar la formalización y mejorar el acceso a servicios esenciales, todos desafíos de larga data en la región. Pero para que la gobernanza digital tenga legitimidad y pueda realmente desplegar todo su potencial, es necesario que todos se conviertan en “ciudadanos digitales”. Esto implica centrarse en las necesidades reales de la población y crear las condiciones para que todos tengan acceso a conexión a internet, dispositivos adecuados y las habilidades necesarias para navegar con seguridad. La transformación digital debe ser ambiciosa. Solo así la región podrá aprovechar todo su potencial y construir un futuro más próspero.

Para más información:

OECD (2025), OECD Economic Outlook, Volume 2025 Issue 2, OECD Publishing, Paris, https://doi.org/10.1787/9f653ca1-en – Reporte completo en inglés con las proyecciones macroeconómicas, los principales desafíos estructurales e información detallada por país.

Perspectivas económicas de la OCDE para países de América Latina

Información detallada por país: Argentina Brasil Chile Colombia Costa Rica | México Perú


The hidden carbon markets: how forests can balance emissions

Positive effects of forests can offset greenhouse gas emissions
How OECD Economic Surveys reveal the drivers of deforestation, and the policy tools to stop it


By Michael Koelle, OECD Economics Department

Tropical forests cover vast swaths of land in many OECD member and accession countries, including more than 75% of Costa Rica’s territory, and over half of Brazil, Colombia, Indonesia and Peru. In these countries, emissions from land use, land use change and forestry (LULUCF), largely driven by forest loss and degradation, account for a large share of total emissions (Figure 1). In fact, land use emissions are in some cases the main driver of national emission trends. But forests can also be part of the solution, as the experiences of Finland and New Zealand, two forest-rich OECD members, teach us.

For many countries, forests are no longer just a conservation issue, they are central to climate mitigation plans. Turning forests into carbon sinks is one of the most cost-effective ways to offset hard-to-abate emissions from agriculture, transport and energy. Finland and New Zealand have long had negative LULUCF emissions thanks to sustainable forest management and afforestation. Costa Rica managed to turn around LULUCF emissions, converting its forests into a carbon sink. Indonesia aims to achieve net negative emissions from LULUCF by 2030 while in Peru and Brazil, LULUCF accounts for 65% and 38% of planned emissions reductions by 2050, respectively. The economic case for protecting forests, through stronger enforcement, property rights, sustainable agriculture, and better incentives, has never been clearer. 

Insights from Economic Surveys: What’s really driving deforestation?

What do Brazil, Costa Rica, Colombia, Finland, Indonesia, New Zealand, and Peru have in common? They are all forest-rich economies, and each has been subject of in-depth analysis in OECD Economic Surveys. These studies go beyond emissions reporting. They dig into the underlying economic drivers of deforestation and discuss what can be done to turn forests into carbon sinks. While each country has its own context, common drivers of deforestation emerge. Forest loss is rooted in economic structures and incentives, from the rapid expansion of agriculture to unclear or unenforced property rights and misalignment between individual incentives and broader societal goals. Developing forest-based activities that generate sufficient economic value while keeping forests intact is far from impossible, given that cleared forest land is often used for low-profitability activities. Moreover, as seen in Finland and New Zealand, afforestation can be one of the least costly ways to reduce net greenhouse gas emissions. Tackling deforestation therefore requires structural policy responses that make choosing forests the economically sensible option, not just environmental regulation.

Fostering sustainable agriculture

Across all countries studied the expansion of the agricultural frontier is the main driver of deforestation. In Peru, OECD research shows that 90% of all deforested land is used for agriculture and livestock-rearing (Garcia Soto and Koelle, 2025). Moreover, 75% of these lands are identified as mixed-use, where farmers combine crop growing and livestock grazing on relatively small plots. In Brazil, cattle is a major pressure; in Indonesia, palm oil plantations continue to push into forest areas. Cattle grazing was also a main driver of deforestation in Costa Rica and Colombia. Most of these activities have low productivity and profitability, making extensive use of underpriced land. As Finland’s experience shows, managing soil emissions from agriculture and forestry can become a crucial issue even when forest stocks have stabilised.

To address this, OECD Economic Surveys recommend:

  • Eliminating environmentally harmful agriculture subsidies, such as cattle ranching subsidies, which contributed to successful reforestation in Costa Rica.
  • Improving scientific knowledge of agriculture, soils and forests, which provides the basis for cost-efficient emissions reduction and carbon storage activities in Finland.
  • Boosting productivity on existing land, to reduce pressure to expand the agricultural frontier.
  • Incentivising agroforestry and sustainable land-use practices and enforcing compliance with the law and regulations tied to land rights.

Strengthening property rights

Most deforestation occurs on land that is either publicly owned or of unclear or unenforced property rights. In Peru, state lands without designated purpose are at the highest risk for deforestation. In Colombia, land rights are often unclear and ambiguous after decades of conflict and displacement of rural populations. In Brazil, a strong framework exists, but enforcement is a challenge. Indigenous communities are especially vulnerable in defending their property rights, even if formally recognised.

OECD Economic Surveys recommend:

  • Creating comprehensive land registries using modern technology.
  • Strengthening property rights and law enforcement in remote areas, including based on satellite imagery.
  • Recognising and enforcing indigenous land rights, which are linked to lower deforestation rates.

Aligning incentives with climate goals

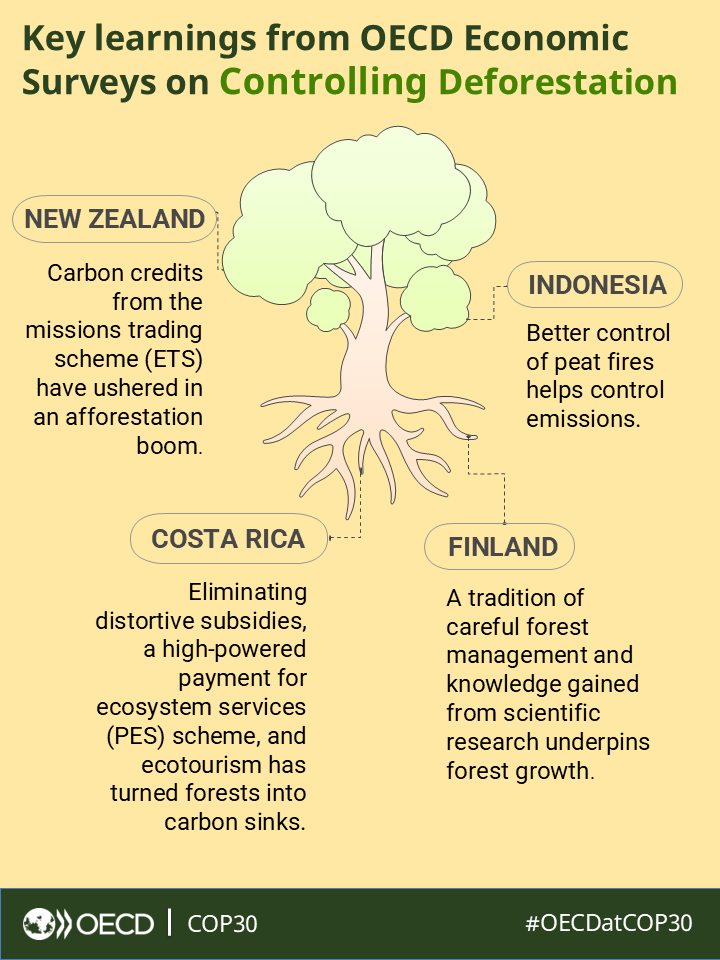
Even with secure land rights and strong enforcement, forest conservation must make economic sense. Intact forests need to generate real value for communities and landowners. Payment for ecosystem services (PES) that provide payments to forest owners for forest preservation are an essential policy tool. Costa Rica’s model stands out: funded by an earmarked portion of fuel taxes it covers 40% of all the nation’s forests, even if financing needs to be put on a broader footing. Other countries have significantly underfunded PES systems or rely mostly on international mechanisms like REDD+ and Article 6 of the Paris Agreement that provide a global mechanism for protecting the world’s remaining forests, but implementation is slow and partly untested. The possibility to sell carbon credits through emissions trading schemes (ETS) can provide powerful incentives for reforestation. New Zealand’s pioneering inclusion of forestry in its ETS, where forest owners can earn carbon credits for capturing carbon through tree growth and must surrender credits if they deforest, provides useful lessons on how such schemes should be designed in forest-rich countries. There should be differentiation according to the emissions removal potential of different forest types, and the design should ensure a sufficiently high carbon price to incentivise carbon-efficiency in non-LULUCF sectors.

The OECD Economic Surveys call for:

  • More robust, broader, and sustainably financed payment for ecosystem services schemes and the expansion and integration of emissions trading schemes.
  • Better integration of eco-tourism, agroforestry, pisciculture and sustainable timber industry into regional economic development and planning.
  • Public incentives that complement, not contradict, private-sector logic.

Conclusion

To truly value forests, governments must embed them into national budgets, tax systems and investment frameworks. Forest conservation must be seen as a sensible investment into preserving the nation’s natural wealth and resources. The cost of these investments is often relatively modest but strong leadership and coordination is needed to ensure that institutions and incentives all work in the same direction.  At COP30 in Belem, forest rich countries have a chance to lead, not just in emission reductions, but also in showing how forests can support climate goals and the economy.

Infographic

REFERENCES

OECD Economic Surveys: Costa Rica 2025, https://doi.org/10.1787/048cf07b-en

OECD Economic Surveys: Finland 2025, https://doi.org/10.1787/985d0555-en

OECD Economic Surveys: Peru 2025, https://doi.org/10.1787/76f6eb73-en

OECD Economic Surveys: Colombia 2024, https://doi.org/10.1787/a1a22cd6-en

OECD Economic Surveys: Indonesia 2024, https://doi.org/10.1787/de87555a-en

OECD Economic Surveys: New Zealand 2024, https://doi.org/10.1787/603809f2-en

OECD Economic Surveys: Brazil 2023, https://doi.org/10.1787/a2d6acac-en

Garcia Soto and Koelle (2025): “Deforestation in Peru: Key facts and main drivers”. OECD Economics Department Working Paper No. 1846, https://doi.org/10.1787/e7786877-en


Convertir la incertidumbre global en oportunidad: Una agenda de competitividad para América Latina

Por Jens Arnold, Aida Caldera, Priscilla Fialho, Paula Garda, Alberto González Pandiella, Michael Koelle, Alessandro Maravalle, Dimitris Mavridis, Claudia Ramírez y Adolfo Rodriguez-Vargas, OCDE.

El contexto global, marcado por una alta incertidumbre política y fragmentación, plantea nuevos desafíos para América Latina, pero también abre nuevas oportunidades para fortalecer su competitividad y reducir vulnerabilidades.

Se espera que el PIB en América Latina crecerá 2.1% en 2025 y 2% en 2026, lo que refleja una desaceleración generalizada en la región. Estas cifras son más bajas que las previstas a fines del año pasado y se sitúan por debajo del promedio de otras economías emergentes. Aunque se espera una fuerte recuperación en Argentina, el crecimiento se mantiene débil en la mayoría de los países, con revisiones a la baja para Brasil, México y Colombia (Tabla), en un contexto generalizado de una débil demanda externa y la alta incertidumbre.

Cuadro. Perspectivas económicas para los países de América Latina

Nota: América Latina 7 es la media ponderada por el PIB a valores de paridad del poder de compra de los 7 países en la tabla para el PIB. América Latina 6 es la media simple de los países incluidos en el cuadro para la inflación excluyendo a Argentina.
Fuente: OCDE Perspectivas Económicas No. 117, junio de 2025.

La desinflación avanza, pero persisten las presiones inflacionarias. La inflación se mantiene por encima del objetivo en muchos países. En cambio, Argentina ha logrado avances significativos gracias a una combinación de consolidación fiscal y una política monetaria más restrictiva. Con la excepción de Argentina y Brasil, los bancos centrales de la región deberían continuar con su flexibilización monetaria prudente y gradual para asegurarse que la inflación se acerque al objetivo, manteniéndose alerta ante riesgos de salidas de capitales y nuevas presiones inflacionarias.

Los riesgos para las perspectivas son a la baja. Un aumento de los aranceles comerciales y menor dinamismo al previsto en socios comerciales clave podría debilitar aún más las exportaciones y presionar a la baja los precios de las materias primas. Los costos comerciales podrían ralentizar más de lo esperado la desinflación en las economías avanzadas y prolongar tasas de interés globales más altas. Una elevada deuda pública y unas condiciones financieras globales más restrictivas de lo previsto, podrían retrasar la tan necesaria inversión. Si se intensifican las salidas de capital, los bancos centrales podrían tener menos margen de maniobra para flexibilizar la política monetaria.

Una agenda de competitividad para tiempos inciertos

En este complejo entorno global, la región necesita más que nunca mejorar sus políticas domésticas. Un área donde es posible avanzar, y urgentemente necesario, es en competitividad, comercio e inversión. Estas no son prioridades nuevas, pero los cambios globales en el comercio, las cadenas de suministro y la transición hacia economías más sostenibles aumentan su relevancia estratégica. Los países que ofrezcan estabilidad institucional, apertura y baja carga administrativa estarán mejor posicionados para atraer inversión y expandir sus mercados.

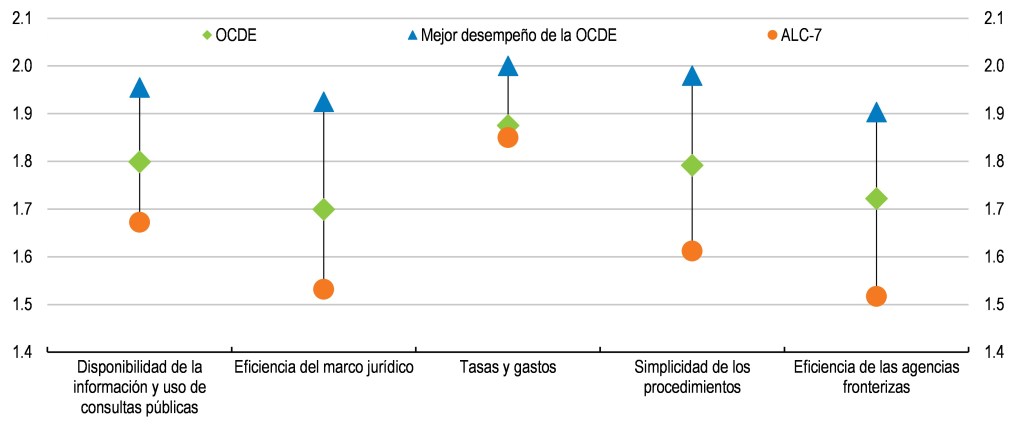
Mejorar los procedimientos aduaneros representa una oportunidad clara. Según los Indicadores de Facilitación del Comercio de la OCDE, América Latina aún enfrenta altos costos comerciales debido a procedimientos aduaneros complejos, inspecciones redundantes y poca coordinación entre agencias fronterizas (Figura). Hay amplio margen para mejorar el procesamiento, levante y despacho de mercancías, en particular mediante una mayor automatización y una mejor coordinación entre las agencias aduaneras, sanitarias, tributarias y otras agencias fronterizas. Medidas prácticas como la cooperación entre agencias de distintos países en la frontera, la agilización de los procesos judiciales y una mayor digitalización pueden beneficiar a los exportadores, especialmente a las pequeñas empresas, y atraer inversión. Además, estas medidas reducen los costos de operar formalmente, lo que incentiva a más empresas a salir de la informalidad.

Figura. Las políticas de facilitación del comercio pueden mejorarse en América Latina

2 = Mejor desempeño

Nota: Disponibilidad de la información y uso de consultas públicas es la media de los indicadores de la facilitación del comercio (TFI, por sus siglas en inglés) A y B. Eficiencia del marco jurídico es la media de los indicadores TFI C y D. Simplicidad de los procedimientos es la media de los indicadores TFI F, G y H. Eficacia de las agencias fronterizas es la media de los indicadores TFI I, J y K. ALC-7 es la media de Argentina, Brasil, Chile, Colombia, Costa Rica, México y Perú.
Fuente: Estadísticas sobre los Indicadores de Facilitación del Comercio de la OCDE (TFI, por sus siglas en inglés).

La facilitación del comercio debe ir acompañada de reformas más amplias que fomenten la productividad. Impulsar la competitividad de las exportaciones y la productividad empresarial también requiere un entorno empresarial más dinámico, una mayor competencia doméstica, un mejor acceso a la financiación, más capacitación y capacidad de innovación. Estas reformas se refuerzan mutuamente: las empresas más productivas tienen mayor probabilidad de exportar, invertir y formalizarse.

El fortalecimiento de la integración regional sigue siendo relevante en América Latina, especialmente en un mundo donde las cadenas de valor están cambiando y los centros regionales cobran mayor importancia. El enfoque debe centrarse en la cooperación: mejorar la cooperación entre organismos fronterizos, el reconocimiento mutuo de normas, el intercambio de datos, los sistemas interoperables y el reconocimiento de estándares técnicos comunes. La región también cuenta con un potencial sin explotar en el comercio de servicios, gracias a idiomas compartidos y husos horarios similares; sin embargo, el comercio interregional de servicios sigue siendo bajo en comparación con los estándares mundiales.

América Latina debe adoptar una visión más orientada hacia el exterior. Acuerdos comerciales como el de la UE-Mercosur, y la participación en marcos plurilaterales como la Alianza del Pacífico o el CPTPP pueden ayudar a diversificar mercados de exportación, atraer inversión, fortalecer la participación en las cadenas globales de valor y aprovechar nuevas tecnologías. Sin embargo, para aprovechar al máximo los beneficios de estas iniciativas, los países deben mejorar su capacidad de implementación y garantizar la coherencia entre las políticas comerciales, de inversión y regulatorias.

América Latina cuenta con ventajas reales: vastas reservas de minerales críticos, abundante energía renovable, una fuerza laboral joven y cada vez más cualificada, y proximidad a mercados clave. Al impulsar reformas concretas que mejoren la competitividad, reduzcan las barreras comerciales y atraigan inversión de calidad, la región puede convertir los desafíos actuales en oportunidades y sentar las bases para un crecimiento más sólido y resiliente.

Referencias:

OECD (2025), OECD Economic Outlook, Volume 2025 Issue 1, OECD Publishing, Paris, doi – Reporte completo en inglés con las proyecciones macroeconómicas, los principales desafíos estructurales e información detallada por país.

Perspectivas económicas de la OCDE para países de América Latina, Junio 2025.

Información detallada por país: Argentina Brasil Chile Colombia Costa Rica | México Perú


Building on recent reform progress In Brazil

By Falilou Fall, Priscillia Fialho, and Jens Arnold, OECD Economic Department

Brazil’s economy has recovered strongly from the consecutive shocks of the last years says the latest OECD Economic Survey of Brazil. This year, buoyed by good weather and a record-high harvest, the economy is expected to grow at 3%, which is far above its long-term growth trend over the last decade. Unemployment is at its lowest level since 2015, while inflation has returned to the central bank’s target after having risen to almost 12% in mid-2022. Even if in the next years growth will fall short of the exceptional performance of 2023, the current OECD projections of 1.8% in 2024 and 2.0% in 2025 are strong in historical comparison, and are largely driven by expanding domestic demand.

The time has now come to re-focus on the pressing structural challenges that Brazil is facing. These include limited fiscal capacity that hampers necessary investments, weak productivity performance, and the need to end deforestation in the Amazon, after visible increases during 2018-2022.

Building fiscal space will help to focus on policy priorities

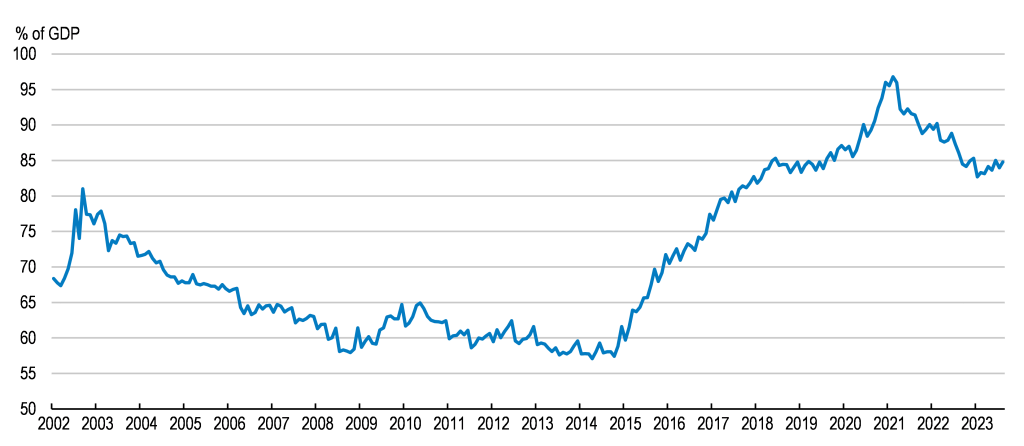
With gross public debt exceeding 80% of GDP (Figure 1), rebuilding fiscal buffers is important to ensure that the public sector can undertake the necessary investments in education, social protection and infrastructure in the future. This will require credible deficit targets that guide fiscal policy over the next years. A recently legislated new fiscal framework is expected to become an essential tool in this context, as it combines a clear path for fiscal outcomes with safeguards for public investment, which has all too often fallen victim to fiscal adjustments in the past.

Figure 1. Rebuilding fiscal space is important
Evolution of public debt

Source: CEIC; Central Bank of Brazil.

Making the most out of scarce fiscal space will also require more agile budgeting processes. These are currently characterised by widespread revenue earmarking and mandatory spending floors that commit 91% of the budget. This limits the government’s ability to address priority policy challenges.

Further important fiscal reforms are either ongoing or planned. A fundamental overhaul of Brazil’s notoriously complex system of consumption taxes has just been approved by Congress. Moving from a fragmented system of consumption taxes towards a unified value-added tax system will make tax compliance much easier for firms and reduce a number of tax-induced distortions that hold back growth. Beyond consumption taxes, there is scope to reform personal income taxes, including with a view towards making them more progressive.

Raising productivity and growth inclusiveness

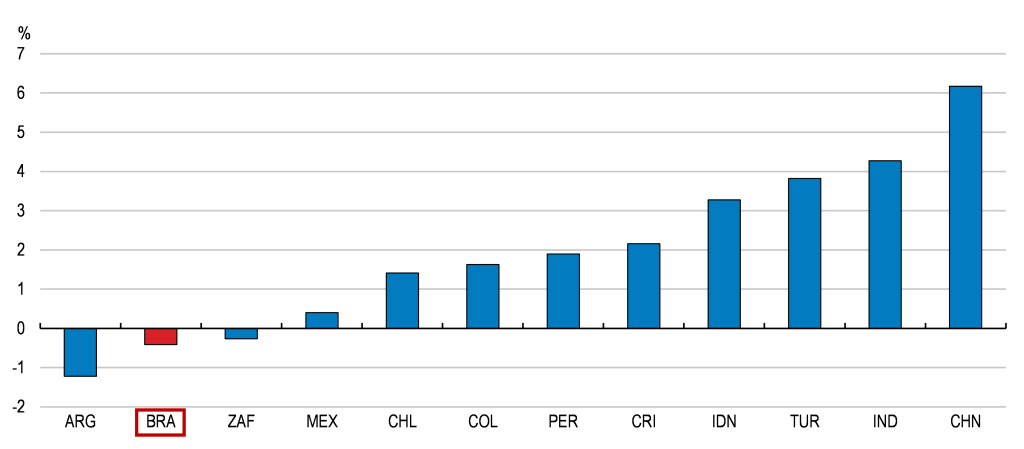
Productivity has been on a declining trend since 2010, and compared to other emerging market economies, Brazil’s per capita growth has been substantially weaker (Figure 2). This is particularly worrying in light of rapid population ageing. A young population has underpinned economic growth in the past, as more and more people were joining the labour force. Over the next 25 years, however, population ageing  is expected to reverse the entire growth dividend that Brazil has reaped from more favourable demographics since the turn of the millenium.

Figure 2. Weak productivity performance and infrastructure competitiveness are impeding stronger growth
Average annual GDP per capita growth, 2012-2021

Source: World Bank; and OECD calculations.

Years of insufficient infrastructure investment have given rise to logistics bottlenecks and high transportation costs, which are one factor behind Brazil’s weak productivity performance. But scarce resources are not the only challenge. Improvements in planning and project execution could substantially improve the performance of many infrastructure projects. As a result of challenges in project management, public infrastructure investment has delivered results that have often fallen short of expectations. 

Competition, another key driver of productivity growth, has been held back by complex regulations and administrative burdens, some of which shield incumbent firms from potential new market entrants. Recent regulatory reforms have led to improvements in this area, but market entry barriers in services sectors remain above the OECD average. Further regulatory reforms in professional services, including the abolition of exclusive rights for certain ancillary tasks, can stimulate competition in crucial markets. Manufactured goods remain subject to elevated trade barriers, with average import tariffs approximately eight times higher than in Mexico. Lowering these trade barriers can facilitate access to foreign markets and foster a deeper integration into global value chains.

Mobilising currently underutilised labour resources and improving education outcomes is equally essential for sustaining stronger long-term economic growth. Womens’ labour force participation and employment rates lag approximately 20 percentage points behind those of men. The pandemic has exacerbated educational disparities by leaving a stronger mark on children from disadvantaged backgrounds. Prioritising investments in the early years of schooling and expanding access to early childhood education, especially for children from disadvantaged backgrounds, have the potential to reduce gender inequality and equip children with better opportunities later in life.

Making growth more sustainable

Deforestation, the largest contributor to greenhouse gas emissions, has increased since 2018, but policy priorities have changed and early indicators now suggest a decline in 2023. Strengthening enforcement of the Forest Code, coupled with allocating more resources to enforcement agencies, will aid in tackling deforestation. Emissions from agriculture, the second-largest source of greenhouse gas emissions, primarily arise from livestock (Figure 3). Better regulations and stronger incentives for more sustainable production hold significant potential for reducing these emissions. Energy emissions are already fairly low given the significant share of hydroelectric energy sources, but also solar and wind energy, where Brazil’s still untapped potential could turn into a major competitive advantage in the future. The planned introduction of carbon pricing mechanisms will be a milestone in the transition towards a lower-carbon economy.

Figure 3. Deforestation and agriculture are the main sources of greenhouse gas emissions
Million tonnes of CO2 equivalent, 2021 or latest

Source: OECD environment database; Estimativas Anuais de Emissões de Gases de Efeito Estuda no Brasil (6ª Edição), Ministério da Ciência, Tecnologia e Inovação; and OECD calculations.

References

OECD (2023), OECD Economic Surveys: Brazil 2023, OECD Publishing, Paris, https://doi.org/10.1787/a2d6acac-en


Difficult decisions in difficult times – Improving public spending in Brazil

By Jens Arnold and Robert Grundke, OECD Economics Department

Portuguese version: Escolhas difíceis em tempos difíceis – Melhorando os gastos públicos no Brasil

Brazil’s government designed one of the strongest COVID-19 fiscal support packages in Latin America. Poor households who were already part of the government’s transfer programmes received extra cash. Formal workers could benefit from short-time work schemes in which the government paid part of their salaries so that their employers would keep their jobs alive. In addition, an entirely new emergency benefit was created for informal workers, which account for 40% of the workforce. On the whole, government policies supported the incomes of more than 67 million people, spending more than 8% of GDP. 

Now Brazil’s economy has started to recover and is expected to grow by 2.6% next year, provided that recent increases in infections do not require new containment measures. But the bill that the state has to foot as a legacy of COVID-19 will make public finances even more complicated than they were before the crisis. Public debt has increased from 76% to 91% of GDP and is projected to exceed 100% of GDP in a few years time. This will make it difficult to continue all the emergency benefits beyond the end of December, when they are currently meant to end. At the same time, there are still 9% of workers who lost their employment with the pandemic and have not been able to find a job since. Many people are still in need, more than 9 months after COVID-19 hit Brazil.

So how can the fiscal dilemma be solved? Brazil’s tax burden is already as high as in advanced economies. Moreover, Brazil’s tax system is itself in need of reform, as it does little to reduce inequality and its complicated rules weigh on productivity. But a closer look at Brazil’s public expenditure reveals a number of ideas about where to start. Current subsidies, tax exemptions, special tax regimes and other tax expenditures cost almost 5% of GDP in lost revenues (Figure 1). This is a similar amount to what Brazil spends on education. Not all of that lacks a purpose, but many of these tax expenditures make tax treatment less equal and benefit special interests, not those most in need. Although some reductions have been achieved in recent years, touching these expenditures is often politically challenging, but all the more important now in the wake of COVID-19. The legislative branch will have to collaborate in efforts to make public spending more effective, as more than 95% of the budget is outside the control of the government, bound by automatic spending rules that require congressional approval to modify.

The 2020 OECD Economic Survey of Brazil discusses these issues in more detail, analysing how changes to current policies could improve the situation of those most in need through better social protection, improve education and vocational training so that more Brazilians can reap new opportunities, and strengthen competition to raise productivity and incomes. Tackling these issues now is more important than ever.

Further reading:
OECD (2020), OECD Economic Surveys: Brazil 2020, OECD Publishing, Paris,
https://doi.org/10.1787/250240ad-en.


Escolhas difíceis em tempos difíceis – Melhorando os gastos públicos no Brasil

Por Jens Arnold e Robert Grundke, Departamento de Economia da OCDE

English version: Difficult decisions in difficult times – Improving public spending in Brazil

O governo brasileiro elaborou um dos pacotes de apoio fiscal mais fortes da América Latina. As famílias pobres que já faziam parte dos programas de transferência do governo receberam dinheiro extra. Os trabalhadores formais puderam se beneficiar de regimes de um regime de trabalho em horário reduzido em que o governo pagava parte de seus salários para que seus empregadores mantivessem seus empregos vivos. Além disso, um benefício de emergência inteiramente novo foi criado para os trabalhadores informais, que representam cerca de 40% dos trabalhadores no Brasil. No total, as políticas governamentais sustentaram a renda de mais de 67 milhões de pessoas, gastando mais de 8% do PIB. 

Agora a economia do Brasil começou a se recuperar e deve crescer 2,6% no próximo ano, desde que os aumentos recentes nas infecções não exijam novas medidas de contenção. Mas a conta que o estado terá de pagar como legado da COVID-19 complicará ainda mais as finanças públicas do que antes da crise. A dívida pública aumentou de 76% para 91% do PIB e prevê-se que ultrapasse 100% do PIB dentro de alguns anos. A luz disso, dar continuidade a todos os benefícios de emergência após o final de dezembro, quando eles deveriam terminar, será difícil. Ao mesmo tempo, ainda há 9% dos trabalhadores que perderam seu emprego com a pandemia e não conseguiram encontrar emprego desde então. Muitas pessoas ainda precisam de ajuda, mais de 9 meses após o COVID-19 chegar ao Brasil.

Então, como o dilema fiscal pode ser resolvido? A carga tributária já é tão alta quanto nas economias avançadas. Além disso, o próprio sistema tributário do Brasil precisa de reforma, pois faz pouco para reduzir a desigualdade e suas regras complicadas pesam sobre a produtividade. Mas um olhar mais atento sobre os gastos públicos do Brasil revela uma série de ideias sobre por onde começar. Os atuais subsídios, desonerações fiscais, regimes fiscais especiais e outras despesas fiscais custam quase 5% do PIB em receitas perdidas (Figura 1). Esse é um valor semelhante ao que o Brasil gasta com educação. Nem tudo isso carece de um propósito, mas muitas dessas despesas fiscais reduzem a igualdade de tratamento e beneficiam interesses especiais, não aquelas pessoas que mais precisam de ajuda. Embora algumas reduções tenham sido alcançadas nos últimos anos, tocar nessas despesas é muitas vezes politicamente desafiador, mas ainda mais importante agora na esteira do COVID-19. O Legislativo terá de colaborar nos esforços para tornar o gasto público mais eficaz, já que mais de 95% do orçamento está fora do controle do governo, vinculado a regras automáticas de gastos que requerem aprovação do Congresso para serem modificadas.

O Relatório Econômico do Brasil da OCDE 2020 examina essas questões com mais detalhe, analisando como mudanças nas políticas atuais poderiam melhorar a situação dos mais necessitados por meio de melhor proteção social, reforzar a educação e a formação profissional para que mais brasileiros possam colher novas oportunidades e fortalecer a concorrência para aumentar a produtividade e a renda. Lidar com essas questões agora é mais importante do que nunca.


Reaching out to informal workers in Latin America: Lessons from COVID-19

By Jens Arnold, Paula Garda, Alberto Gonzalez-Pandiella, OECD Economics Department

Social distancing has led to sharp declines in mobility and activity across Latin America. Widespread informality creates particular challenges for the livelihoods of many workers. As their activities are shut down to contain the spread of COVID-19, informal workers or small entrepreneurs are usually not covered by social protection. Largely out of reach of the public sector, they easily fall through the cracks of emergency income support measures. This has highlighted a major need to rethink and strengthen social protection mechanisms in Latin America. Providing more complete social safety nets that are not tied to formal employment and that can react rapidly to income losses would be one solution. In many countries in the region, such safety nets could be built on the basis of existing conditional cash transfer programmes.

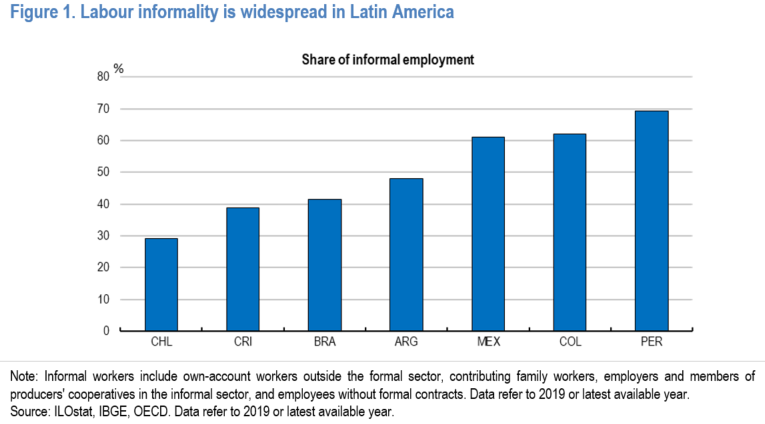
Informal workers and small entrepreneurs account for a significant share of the workforce across Latin America (Figure 1). Most of them have no access to social protection, and almost no savings to carry them through the trough. Informal employees were the first to lose their jobs, while self-employed entrepreneurs such as street sellers and small service providers were left with no source of income as streets became empty. Working from home may be a solution for educated middle-class workers, but it is out of reach for the most vulnerable (Mongey and Weinbergy, 2020).

The crisis has exposed shortcomings in existing social protection mechanisms

Governments in Latin America responded swiftly to the unprecedented challenges posed by COVID-19. Many countries designed temporary support measures, building on existing instruments such as formal-sector unemployment insurance and cash transfers. Formal-sector employees benefitted from more flexible access to unemployment benefits, for example in Brazil and Chile, while temporary short-time work schemes, wage subsidies or lower labour contributions helped to preserve formal labour contracts Brazil, Colombia, Costa Rica and several Mexican states. Cash transfer schemes targeted to low-income households play important roles in Argentina, Bolivia, Brazil, Chile, Colombia, Costa Rica, Ecuador, Mexico and Uruguay, among others. These cash transfer schemes are typically based on large locally-maintained registries of low-income households that can consider both formal and informal incomes. Providing additional resources to these schemes allowed to raise benefit levels and/or expand coverage, including by eliminating previous enrolment waiting lists, as in the cases of Brazil, Chile, Colombia and Peru.

The COVID-19 policy response, however, has also exposed significant gaps in existing social safety networks. Amid policy support for formal workers and for the poor, vulnerable households whose livelihoods depend on informal activities are often left without any social protection mechanism to fall on. Before the pandemic, many of these had successfully escaped poverty and gained incomes above the threshold where they would qualify for cash transfers, but without gaining access to the kind of social protection in place for formal employees. As distancing measures led to unprecedented declines in demand, many of these households were left without any income.

Reaching informal workers is a challenge for public policies and has required innovative ideas. Beyond the grasp of income tax systems, and with no access to social benefits, many informal workers have traditionally been outside the radar of the state. In addition, they often lack access to banking services, so governments had to respond creatively and ensure the creation of basic bank accounts for emergency benefit recipients. More than 50 million Brazilians used a smartphone application to receive an emergency benefit established after the outbreak. Colombia has been similarly successful, paying out benefits to 1.5 million households previously not covered by social benefits, and including free digital banking products. Chile is supporting more than 2 million vulnerable and informal households through different cash transfers, handing out debit cards to those without a bank account. Costa Rica’s new cash transfer also offers the creation of a bank account. Such programmes have replaced significant shares of pre-crisis incomes for low-income households (Busso et al., 2020).

Lessons for the future

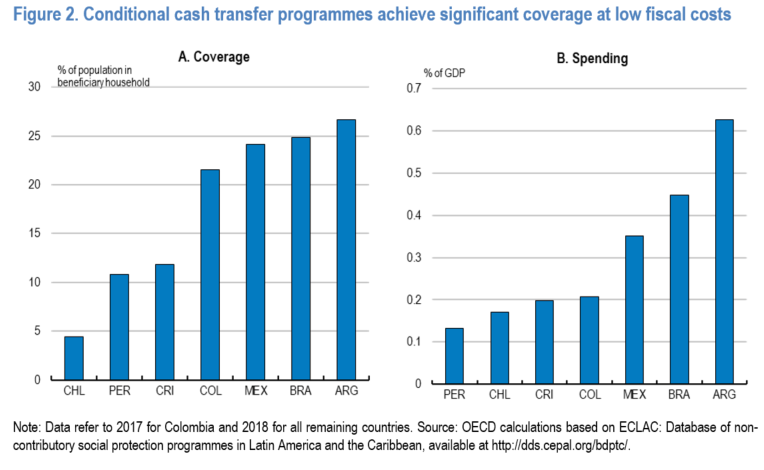
Building more effective universal social safety nets that include informal workers and entrepreneurs emerges as one of the main lessons from the COVID-19 crisis and the social unrest during 2019. Given their wide reach in many countries, existing cash-transfer programmes would be the most straightforward basis for effective social safety nets (Figure 2, Panel A). In several countries, eligibility is in principle universal, but in practice, enrolment processes are too slow or cumbersome to help people in the face of sudden income losses. An important step would therefore be to make cash transfer programmes more agile, so that they can disburse quickly when people lose their livelihoods, following the examples of the UK’s Universal Credit or Malaysia’s BSH programme. More universal social safety nets based on means-tested cash transfers could also help to reduce the widespread fragmentation of social programmes, and strengthen their effectiveness.

Financing universal social safety nets will require additional resources, but building on existing programmes may make the cost manageable. Cash transfer schemes are among the most cost-efficient social expenditure programmes, and they cost relatively little (Figure 2, Panel B). Brazil’s successful Bolsa Família programme, for example, currently only costs 0.5% of GDP, compared with 12% spent on formal social security schemes. During the COVID-19 pandemic, additional spending of 0.04% of GDP was enough to eliminate an accumulated queue of 1 million benefit applicants. Building on existing citizen identification systems and digital technologies could further reduce costs.

Social protection for informal workers should go along with efforts to foster formalisation. Reviewing non-wage labour costs can help to reduce informality, as illustrated by Colombia’s 2012 tax reform. Costly and complex business regulations, including those for starting a formal business, also hamper the formalisation of firms and jobs. Expanding the use of one-stop shops for business regulations would be one way forward. Social programmes could increasingly integrate training and lifelong learning for informal workers. This could create a virtuous circle between formal employment, growth and equity.


Informality and weak competition – a deadly cocktail for growth and equity in emerging Latin America

By Piritta Sorsa, Jens Arnold and Paula Garda, OECD Economics Department

Why is growth persistently low and so unevenly distributed in emerging Latin America compared to emerging Asia despite a huge potential? Potential growth is ranging around 2-3% in the region. Some refer to dependence on commodities, poor education, weak business environments or corruption as possible causes. But the question is deeper and more complex. A crucial factor for Latin America is low productivity, often related to a poor use of available resources. Across the region, many workers and significant amounts of capital are stuck in activities that are not efficient. The reasons for this are many, but two important forces stand out: high informality and weak competition.

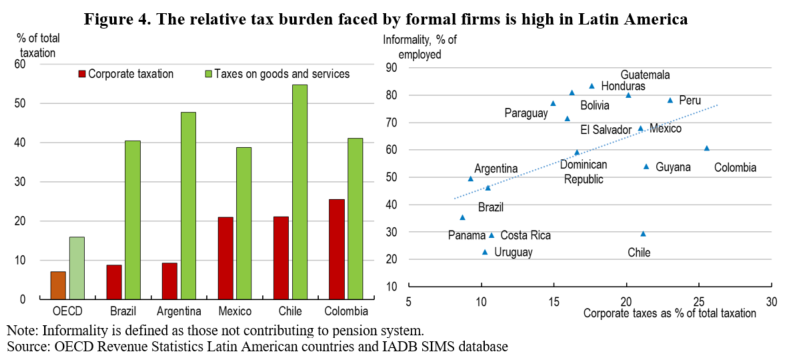
High and persistent informality in the region leaves workers more vulnerable and deprives them from social protection, thus contributing to inequality. For example, old age poverty in Colombia is high as low-skilled workers spend much of their working lives in informal employment, without pension contributions (OECD, 2019[1]). In Brazil and Argentina, informal workers retire later than others for the same reason, until they eventually reach the age to benefit from a non-contributory pension (OECD, 2019[2]; OECD, 2018[3]). In Mexico, poverty and informality are highly correlated among regions (OECD, 2019[4]). Informality also tends to maintain companies small with often low productivity as growing would face high costs of formalisation. Indeed, informal-sector productivity in the average LAC country is only between 25 and 75 percent of total labour productivity, and productivity decreases as informality rises (Loayza, 2018[5]). Informality also reduces the tax base for corporate and personal income taxes, reducing the capacity of the public sector to boost productivity and reduce inequality, and requires a higher tax burden on larger formal companies.

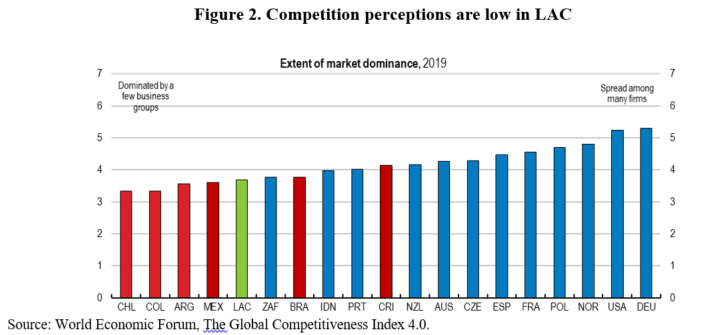
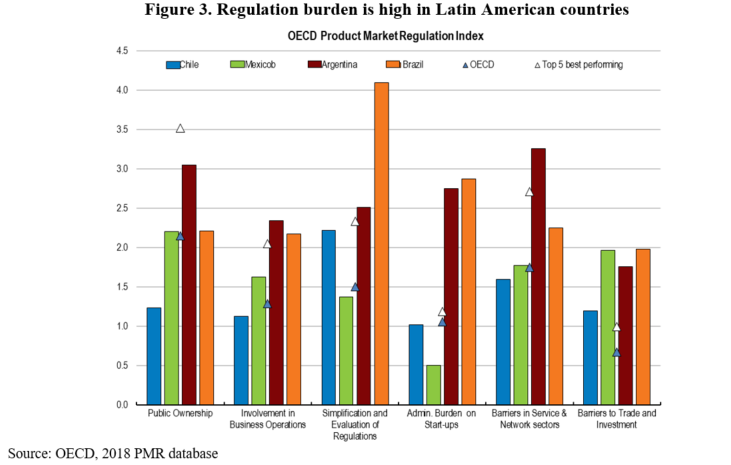
Weak competition is a second reason behind low productivity and is often reflected in high concentration (Figure 2). Entry barriers can protect existing activities that have little future growth potential at the cost of new dynamic and productive firms. Weak competition creates rents and lowers the share of wages in value-added worsening income distribution. Higher prices for consumers reduce purchasing power, affecting disproportionally low-income households.

Reducing informality for productivity and equity

The causes of informality are multiple. Informality is often a consequence of high costs of hiring formal workers, both wage and non-wage, especially in relation to labour productivity, given low educational outcomes.

Where high informality and weak competition coincide, as is the case in many Latin American countries, the consequences for both growth and equity can be particularly severe. For emerging Latin America to grow stronger and better share the fruits of growth, dealing with informality and competition should be priority.

Labour informality is often caused by rigid labour regulation. High firing costs of workers can discourage formal-sector hiring and promote inequality (Loayza, 2018[5]; OECD, 2018[6]; Heckman and Pages, 2000[7]). In Mexico, a labour reform in 2012 reduced hiring and firing costs, introduced different models of contracting and brought changes to the resolution of labour conflicts. Formal salaried jobs increased in the aftermath (OECD, 2019[4]). Minimum wages can be high compared to productivity or average wages keeping most workers informal. In Colombia, the minimum wage is close to the median wage and two thirds of workers earn less than that (OECD, 2019[1]). High payroll taxes can also have a detrimental effect on informality rates (Bobba, Flabbi and Levy, 2018[8]). Antón and Rastaletti (2018[9]) show how lowering employer social security contributions could lead to a substantial increase of labour formalisation. At a minimum, lower employer contributions could be offered temporarily for hiring low-skilled workers that enter the formal sector for the first time (OECD, 2017[10]). Lowering payroll taxes in Colombia helped reduce informality after the 2012 reform (Kugler et al., 2017[11]; Morales and Medina, 2016[12]; Fernández and Villar, 2016[13]; Bernal et al., 2017[14]). While incentives are crucial, better enforcement also needs to be part of any formalisation strategy.

Cumbersome administrative barriers and high taxes can keep companies informal. Latin America stands out in this respect (Figure 3). The tax burden on formal companies is also high compared to the OECD and positively associated to informality rates (Figure 4). To promote formalisation, regulatory and tax systems should be simple, with gradual increases in the tax burden as firms grow, so as not to discourage growth, and keep marginal tax rates as low as possible (Loayza, 2018[5]). These characteristics are crucial to encourage investment and employment in growing and larger companies.

Many countries in the region have implemented simplified schemes and reduced costs for small taxpayers with the aim of reducing informality. For example, Mexico introduced a special simplified regime for SMEs (Regimén de Incoporación Fiscal, RIF) in 2014, which induced 1.5 million informal firms to join the tax system (OECD, 2018[15]). In Brazil, a special tax regime for microenterprises (Microemprendedor Invididual, MEI) reduced the cost of formalisation and contributions to social security as of 2008. This regime helps explain the rising formalisation of the self-employed, including of women (OECD, 2012[16]). In Argentina, a simplified tax regime called Monotributo helped formalise self-employed workers. In Colombia, the tax reform in 2018 introduced a new simplified tax scheme (Simple) for small firms, and there are signs of positive impact on firm formalisation during 2019. At the same time, these regimes have to be designed carefully. When participation thresholds for special SME tax regimes are set too high, the effectiveness for formalisation declines while fiscal cost and threshold effects rise, as in the case of Brazil’s Simples Nacional (OECD, 2018[3]). At times, simplifying the general tax regime may be preferable over creating exceptions.

Education and skill levels are also linked with informality. Countries with lowest informality rates tend to have significantly higher levels of human capital (Docquier, Müller and Naval, 2017[17]). It is not a coincidence that the decrease in informality over recent decades in Latin America went hand in hand with steady progress towards universal education. Evidence shows that improvements in education have been an important driving force behind falling informality in Colombia and Brazil (International Monetary Fund, 2018[18]; OECD, 2018[3]).

Increasing competition for productivity and equity

In Latin America, the same complex rules that discourage formal job creation often coincide with overly strict regulations that stifle competition. Competition is affected by how easily firms can enter or exit markets, by the extent of license requirements for starting or expanding a business and by competitive pressures from imports. Relatively high trade protection adds to this in a number Latin American countries, shielding domestic producers from international competition (OECD, 2018[3]). All of this tends to raise prices for consumers and keep resources in low-productivity activities where informality is widespread, for both workers and firms.

These circular relationships suggest that it is important for the public sector to take stock of burdens that even well-intended regulations and codes can impose on private activity. Disincentives for firms to go formal will inevitably preclude workers from the benefits of formal jobs, while unnecessary barriers to competition will keep more jobs in activities with limited potential for productivity and wage growth. To foster formal job creation, all parts of a country’s regulatory framework should be simple and clear, promote competition, and facilitate both market entry and exit of firms (Loayza, Oviedo and Serven, 2005[19]).

Getting there

A comprehensive strategy is needed to deal with both informality and competition. It involves simplifying labour regulations, keeping administrative burdens and license requirements for companies as easy as possible, facilitating market entry and reducing trade barriers. Bringing more workers and firms into the formal sector would bring about broader social and labour protection, fairer wages, a more even tax burden and higher potential growth. Many of these policies are politically difficult as they involve dealing with vested interests and require appropriate sequencing. But that is not an excuse for inaction. These reforms should be accompanied with training and other active labour market policies for affected workers, as the informal sector often fulfils the function of absorbing excess labour supply, especially during transitions or economic recessions. Reforms to improve quality and relevance of education to raise worker productivity and policies that can raise investment and boost firm productivity should be also part of the strategy.

References

Antón, A. and A. Rasteletti (2018), Imposición al trabajo en contextos de alta informalidad laboral: Un marco teórico para la simulación de reformas tributarias y de seguridad social, Inter-American Development Bank, Washington, D.C., http://dx.doi.org/10.18235/0001467.

Bernal, R. et al. (2017), “Switching from Payroll Taxes to Corporate Income Taxes: Firms’ Employment and Wages after the Colombian 2012 Tax Reform”, IDB Technical Note, No. 1268, Inter-American Development Bank.

Bobba, M., L. Flabbi and S. Levy (2018), “Labor Market Search, Informality and Schooling Investments”, Interamerican Development Bank, https://publications.iadb.org/en/publication/12928/labor-market-search-informality-and-schooling-investments.

Docquier, F., T. Müller and J. Naval (2017), “Informality and Long-Run Growth”, The Scandinavian Journal of Economics, Vol. 119/4, pp. 1040-1085, http://dx.doi.org/10.1111/sjoe.12185.

Fernández, C. and L. Villar (2016), “The Impact of Lowering the Payroll Tax on Informality in Colombia”, No. 72, Fedesarrollo, http://hdl.handle.net/11445/3300.

Heckman, J. and C. Pages (2000), “The Cost of Job Security Regulation: Evidence from Latin American Labor Markets”, NBER working paper, No. 7773, National Bureau of Economic Research, http://dx.doi.org/10.3386/w7773.

International Monetary Fund (2018), “Colombia: Selected Issues”, Country Report, No. 18/129, http://www.imf.org.

Kugler, A. et al. (2017), “Do Payroll Tax Breaks Stimulate Formality? Evidence from Colombia’s Reform”, NBER Working Paper Series, http://www.nber.org/papers/w23308.

Loayza, N. (2018), “Informality : Why Is It So Widespread and How Can It Be Reduced?”, Research and Policy Briefs, No. 20, World Bank, http://documents.worldbank.org/curated/en/130391545228882358/Informality-Why-Is-It-So-Widespread-and-How-Can-It-Be-Reduced.

Loayza, N., A. Oviedo and L. Serven (2005), “The impact of regulation on growth and informality – cross-country evidence”, Policy, Research working paper World Bank 3623, http://documents.worldbank.org/curated/en/212041468134383114/The-impact-of-regulation-on-growth-and-informality-cross-country-evidence.

Morales, L. and C. Medina (2016), “Assessing the Effect of Payroll Taxes on Formal Employment: The Case of the 2012 Tax Reform in Colombia”, Borradores de Economia, Banco de la Republica, http://www.banrep.gov.co/en/borrador-971.

OECD (2019), Economic Surveys: Colombia, https://doi.org/10.1787/e4c64889-en.

OECD (2019), Economic Surveys: Mexico, https://doi.org/10.1787/a536d00e-en.

OECD (2019), OECD Economic Surveys: Argentina 2019, OECD Publishing, Paris, https://dx.doi.org/10.1787/0c7f002c-en.

OECD (2018), Economic Surveys: Chile, https://doi.org/10.1787/eco_surveys-chl-2018-en.

OECD (2018), Getting it Right: Strategic Priorities for Mexico, OECD Publishing, Paris, https://dx.doi.org/10.1787/9789264292062-en.

OECD (2018), OECD Economic Surveys: Brazil 2018, OECD Publishing, Paris, https://dx.doi.org/10.1787/eco_surveys-bra-2018-en.

OECD (2017), OECD Economic Surveys: Argentina 2017: Multi-dimensional Economic Survey, OECD Publishing, Paris, https://dx.doi.org/10.1787/eco_surveys-arg-2017-en.

OECD (2012), Closing the Gender Gap ACT NOW: Brazil Country note, OECD, Paris, France, http://www.oecd.org/gender/closingthegap.htm.


Positive economic outlook for the main economies in Latin America but downward risks have intensified

Alvaro S. Pereira (Director) and Latin American desks, Economics Department, Country Studies Branch, OECD

The global economy is navigating rough seas. Global GDP growth is strong but it has peaked. In many countries unemployment is well below pre-crisis levels, labour shortages are biting and inflation remains tepid.  Yet, global trade and investment have been slowing on the back of increases in bilateral tariffs while  many emerging market economies are experiencing capital outflows and a weakening of their currencies. The global economy looks set for a soft landing, with global GDP growth projected to slow from 3.7% in 2018 to 3.5% in 2019-20. However, downside risks abound and policy makers will have to steer their  economies carefully towards sustainable, albeit slower, GDP growth.

The economic recovery in the Latin American economies has become dissimilar. While in some countries, growth has been revised downwards, in others it has been revised upwards. This disparity is closely linked to how these economies have evolved in the face of the financial stress and increased financial volatility in recent months. The region’s economies with the best macroeconomic fundamentals, independent central banks, countercyclical monetary policies, sound fiscal policy framework and no major currency mismatches in corporate or sovereign debt, were better able to sail the adverse global financial conditions that led to capital outflows, weakening their currencies.

Table LAC EO104

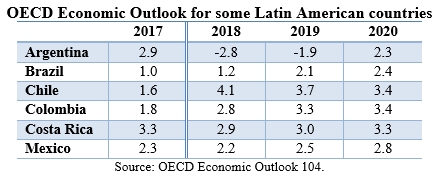
While Chile and Colombia have gained momentum, Brazil has shown lower growth and Argentina has fallen into recession. Mexico and Costa Rica have also experienced less momentum than expected. Growth in Argentina, Brazil, Chile, Colombia, Costa Rica and Mexico, countries covering about 85% of Latin America’s GDP, is expected to be around 1.4% this year and to accelerate to 2.0% in 2019 and 2.7% in 2020 (weighted average) (see Table). However, downside risks abound while the region is vulnerable to the global context. Several indicators, such as the fiscal and current account deficits have been accentuated in the last decade in most of these economies (Figure), suggesting that the region is still vulnerable. Needs to be noted that the situation is uneven and a broader list of indicators should be analysed.

Figure LAC EO104

An accumulation of risks could create the conditions for a harder-than-expected landing. First, further trade tensions would take a toll on trade and GDP growth, generating even more uncertainty for business plans and investment. Second, tightening financial conditions could accelerate capital outflows from the region and depress demand further. Third, a sharp slowdown in China would hit Latin America and other emerging economies, but also advanced economies if the demand shock in China triggered a significant decline in global equity prices and higher global risk premia.

Looking ahead, it will be necessary to strengthen the macroeconomic policy framework to reduce vulnerabilities where necessary. Most of the region’s economies are starting, or will start in the near future, more restrictive monetary policies, while also undertaking fiscal consolidation. Depending on each country, it will be important to find a balance between the needs for social spending and public investment, with the need to put debt on a sustainable path. In Chile, Colombia and Mexico, this consolidation can be done gradually, but Argentina, Brazil and Costa Rica need to do it more urgently. Pension or tax reforms will be necessary in this regard.

Given the limited scope for countercyclical policies, in the face of external risks and a more pronounced slowdown, the time to promote the necessary structural reforms is now to guarantee a future with a sustained increase in productivity and greater inclusion. Many countries in the region have scope to reform the tax system and make it more effective in improving investment incentives and raising more resources. Depending on the characteristics of each country, possible measures may include limiting the use of tax exemptions and reduced rates, particularly in VAT, but also in corporate taxes, extending the tax base by including more people in personal income taxes, reducing evasion or making greater use of property, inheritance or environmental taxes. Other priorities should focus on export promotion and diversification, which would help reduce current account deficits. Investing in quality and innovative human capital, closing infrastructure and logistical gaps, and curbing corruption would support exports and their diversification, strengthening growth. Encouraging women’s participation in the labour force, reducing precariousness and informality in the labour market, as well as pension reforms are also urgent in several countries of the region and necessary to increase productivity and reduce inequalities.

Argentina: A combination of massive fiscal and monetary tightening will keep the economy in recession during 2018 and 2019. Private consumption and investment will remain depressed due to lower real incomes and high interest rates, and unemployment will rise. However, a better harvest and a lower real exchange rate will support stronger exports.

Brazil: Growth will gain momentum during 2019 and 2020 as private consumption, supported by improvements in the labour market, will increase. Recovering credit and greater policy certainty as a new administration takes office will buttress the recovery. Political uncertainty around the implementation of reforms remains significant and could derail the recovery, but if uncertainty fades and reforms advance as assumed, investment will become stronger.

Chile: Growth is projected to remain strong over the next two years. With an uncertain external environment, solid domestic demand will underpin growth, aided by a stable inflation environment, public infrastructure projects and a tax reform. Inequality, though  decreasing, remains high, as informality and unemployment remain high and social transfers low.

Colombia: Growth is projected to pick up as infrastructure projects, lower corporate taxes and higher oil prices will boost investment. Improving confidence and financing conditions will support consumption. As growth gains traction, unemployment will edge down. Social indicators are improving but informality and inequality remain high.

Costa Rica: Growth is projected to recover to around 3¼ per cent in 2020 and be broad-based, underpinned by both domestic and external demand. However, uncertainty, particularly surrounding the planned fiscal reforms, is weighing on growth in the near term. The projections are based on the assumption that the fiscal reforms will be implemented from 2019, with modest fiscal tightening holding back growth in 2019 and 2020.

Mexico: Growth is projected to pick up to 2¾ per cent in 2020. Low unemployment, strong remittances and the recovery of real wages  will support household consumption. Investment, which has been persistently low, will strengthen on the back of announced public investment plans and increased confidence associated with the US-Mexico-Canada trade agreement. Exports will decelerate owing to less favourable global conditions, especially in the United States. Inflation has been pushed up by rising energy prices, but expectations and core inflation remain anchored and within the central bank’s target band. Informality is slowly declining but remains elevated,  contributing to persistently high inequalities and low productivity.

To read more about the Economic Outlook and the main structural challenges visit the english and spanish/portuguese version (it includes OECD forecasts and a chapter on decoupling of wages and productivity and the implications for public policy).

References:

OECD (2018), OECD Economic Outlook, Volume 2018 Issue 2: Preliminary version, OECD Publishing, Paris, https://doi.org/10.1787/eco_outlook-v2018-2-en.


Las perspectivas económicas son positivas en los principales países de América Latina pero los riesgos a la baja se han acentuado

Alvaro S. Pereira (Director) y mesas de países latinoamericanos, Departamento de Economía, Directorado de estudios de países, OCDE

La economía mundial está navegando mares agitados. El crecimiento del PIB mundial es fuerte, pero ha alcanzado su punto máximo. En muchos países, el desempleo está por debajo de los niveles anteriores a la crisis de 2008, la escasez de mano de obra se empieza a sentir, aunque la inflación sigue siendo templada. Sin embargo, el comercio y la inversión mundiales se han desacelerado como consecuencia del incremento de aranceles bilaterales y de mayor incertidumbre política, mientras que varias economías emergentes están experimentando salidas de capitales y un debilitamiento de sus monedas. La recuperación del crecimiento global  comenzará a desacelerarse, mientras que los riesgos a la baja se han acentuado. Se prevé que el crecimiento del PIB mundial disminuya del 3,7% en 2018 a 3,5% en 2019-2020. Sin embargo, abundan los riesgos de recesión y los responsables políticos tendrán que orientar cuidadosamente sus economías hacia un crecimiento sostenible, aunque más modesto, del PIB.

En las principales economías de América Latina, la recuperación económica se ha vuelto despareja. Mientras que en algunas, el crecimiento se ha revisado a la baja, en otras se ha revisado al alza. Esta disparidad está estrechamente ligada a cómo estas economías han evolucionado frente al estrés financiero e incremento de volatilidad financiera de los pasados meses. Las economías de la región con mejores fundamentos macroeconómicos, bancos centrales independientes, políticas monetarias contracíclicas, un marco de política fiscal sólido y sin grande descalce de monedas en la deuda corporativa o soberana, fueron los que sortearon mejor las condiciones financieras globales adversas que sometieron a varios países a una repentina salida de capitales y debilitamiento de sus monedas.

Table LAC EO104 Esp

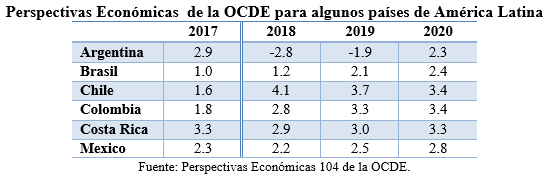
Mientras que Chile y Colombia han ganado ímpetu, Brasil ha mostrado menor crecimiento y Argentina ha caído en recesión. México y Costa Rica también han experimentado menor ímpetu al esperado. Se espera que el crecimiento en Argentina, Brasil, Chile, Colombia, Costa Rica y México, países que cubren alrededor del 85% del PIB de América Latina, se sitúe en torno al 1.4% este año y se acelere a 2.0% en 2019 y 2.7% en 2020 (promedio ponderado) (Tabla). Sin embargo, abundan los riesgos a la baja, mientras que la región se encuentra vulnerable al contexto global. Algunos indicadores, como los déficits fiscales y de cuenta corriente (Figura) se han acentuado en la mayoría de estas economías en la última década, sugiriendo que la región es aún vulnerable. Debe notarse que la situación es dispar y se debe mirarse una lista más amplia de indicadores.

Una acumulación de riesgos podría crear las condiciones para una desaceleración de crecimiento más acentuada de la esperada. En primer lugar, nuevas tensiones comerciales afectarían al comercio y al crecimiento del PIB, generando aún más incertidumbre para las empresas y la inversión. En segundo lugar, el endurecimiento de las condiciones financieras globales podría acelerar las salidas de capitales y deprimir aún más las monedas de la región. En tercer lugar, una fuerte desaceleración en China afectaría a la región y otras economías emergentes, pero también a las economías avanzadas si el shock de la demanda en China provocara un descenso significativo de los precios mundiales de las acciones y un aumento de las primas de riesgo mundiales.

Figure LAC EO104Esp

De cara al futuro, será necesario reforzar el marco de las políticas macroeconómicas para reducir vulnerabilidades donde sea necesario. La mayor parte de las economías de la región están comenzando, o lo harán en el futuro próximo, políticas monetarias más restrictivas, al tiempo que también deben llevar a cabo una consolidación fiscal. Dependiendo de las holguras de cada país, será importante encontrar un ritmo que balancee las necesidades de gasto social y de inversión pública, con la necesidad de poner la deuda en una senda sustentable. En Chile, Colombia y México, esta consolidación se puede llevar a cabo de manera gradual, pero Argentina, Brasil y Costa Rica necesitan hacerlo de manera más urgente. Reformas pensionales o tributarias serán necesarias en este sentido.

Dado el escaso margen para hacer políticas contracíclicas ante la realización de riesgos externos y una deceleración más acentuada, el momento de impulsar reformas estructurales necesarias es ahora, para garantizar un futuro con incremento sostenido de la productividad y mayor inclusión. Muchos países de la región tienen margen para reformar el sistema tributario y hacerlo más eficaz para mejorar los incentivos a la inversión y recaudar más recursos. Según las características de cada país, posibles medidas pueden incluir limitar el uso de exenciones tributarias y tasas reducidas, en particular en el IVA, pero también en los corporativos, extender las bases de imposición incluyendo más personas en los impuestos a los ingresos personales, reducir la evasión o hacer mayor uso de impuestos a la propiedad, a la herencia o impuestos ambientales. Otras prioridades deberían focalizarse en fomentar las exportaciones, y diversificarlas, lo que ayudaría a reducir los déficits de cuenta corriente. Invertir en capital humano de calidad e innovación, cerrar las brechas de infraestructura y logística y frenar la corrupción apoyarían a las exportaciones y su diversificación, fortaleciendo el crecimiento. Alentar la participación de la mujer en la fuerza laboral, reducir la precariedad e informalidad del mercado laboral, así como reformas al sistema de pensiones son también urgentes en varios países de la región y necesarios para aumentar la productividad y bajar las desigualdades.

Argentina: La economía seguirá en recesión en 2018 y 2019 debido a un endurecimiento fuerte y simultáneo de políticas monetarias y fiscales. El consumo privado y la inversión seguirán siendo bajos a causa del descenso de los ingresos reales y de los elevados tipos de interés, y aumentará el desempleo. Sin embargo, una mejor cosecha y un tipo de cambio real más competitivo contribuirán al aumento de las exportaciones.

Brasil: El crecimiento cobrará impulso en 2019 y 2020 gracias al aumento del consumo privado, respaldado por mejoras en el mercado laboral. La reactivación del crédito y el descenso de la incertidumbre política una vez que el nuevo gobierno tome posesión apuntalarán la recuperación económica. La incertidumbre política sobre la implementación de reformas sigue siendo importante y podría frenar la recuperación pero, si desaparece y las reformas siguen adelante como se supone que deberían hacerlo, aumentará la inversión.

Chile: Según las proyecciones, el crecimiento seguirá aumentando en los próximos dos años. Ante una incierta coyuntura externa, el crecimiento estará respaldado por la sólida demanda interna con ayuda de un entorno de inflación estable, proyectos de infraestructuras públicas y una reforma fiscal. A pesar que las desigualdades han disminuido, permanecen altas, debido a que la informalidad y el desempleo siguen siendo elevados y las transferencias sociales escasas.

Colombia: Las proyecciones indican que el crecimiento repuntará, ya que los proyectos de infraestructuras, el descenso del impuesto de sociedades y la subida de los precios del petróleo potenciarán la inversión. La mejora de la confianza y de las condiciones de financiamiento respaldará el consumo. A medida que el crecimiento se vaya afianzando, el desempleo descenderá. Los indicadores sociales están mejorando, aunque la informalidad y la desigualdad se mantendrán en niveles elevados.

Costa Rica: Según las proyecciones, el crecimiento se recuperará hasta el 3¼ aproximadamente en 2020 y será generalizado, sostenido tanto por la demanda interna como externa. Sin embargo, la incertidumbre, particularmente respecto a las reformas fiscales planificadas está lastrando el crecimiento a corto plazo. Las proyecciones parten del supuesto de que las reformas fiscales se aplicarán a partir de 2019, con un modesto ajuste fiscal que frenará el crecimiento en 2019 y 2020.

México: Está previsto que el crecimiento repunte hasta el 2¾ por ciento hacia 2020. El bajo nivel de desempleo, fuertes remesas y la recuperación de los salarios reales reforzarán el consumo de los hogares. La inversión, que ha sido persistentemente baja, se reforzará a consecuencia de los planes de inversión públicos anunciados y del aumento de la confianza vinculado al acuerdo comercial entre Estados Unidos, México y Canadá. El crecimiento de las exportaciones se reducirá debido a unas condiciones internacionales menos favorables, en especial en Estados Unidos. La subida de los precios de la energía ha empujado la inflación al alza, pero las expectativas y la inflación subyacente siguen ancladas y dentro del rango meta del banco central. El alto nivel de informalidad contribuye a que haya una gran desigualdad y una escasa productividad.

Para leer en más detalle sobre las proyecciones macroeconómicas, así como los principales desafíos estructurales ir al reporte en la versión español/portugués o inglés (que incluye proyecciones para países de la OECD, principales desafíos y un capítulo especial sobre la desvinculación de los salarios y la productividad y las implicancias en términos de políticas públicas).