Uncertainty: A persistent drag on trade

By Catherine MacLeod and Elena Rusticelli, OECD Economics Department.

Global trade growth has been surprisingly robust in 2025, boosted by strong demand in new AI-related investment and intense front-loading of activity ahead of new tariff increases, as shown in the latest OECD Economic Outlook. However, at the same time, trade policy uncertainty has risen and without concerted efforts to mitigate it, trade growth may be much lower than otherwise over the next three years.

Uncertainty about trade policy has risen markedly recently, with a peak in April following the announced increase in US bilateral tariffs on all its trading partners that month. Although uncertainty has subsequently drifted lower, it still remains elevated by past standards in many countries (Figure 1).

It is likely that trade policy uncertainty will decrease international trade. Prolonged economic uncertainty is already known to discourage long-term investment (OECD, 2025b) and cause households to delay consumption. Several studies have shown a sizeable decrease in international trade in the nine to 12 months period following a trade policy uncertainty episode (Caldara et al., 2019; Sampognaro, 2025). Nonetheless, in the very short term, uncertainty could provide an incentive for firms to increase imports immediately before anticipated, though unpredictable, costly policy changes. This was a factor behind the 38% annualised rise in US imports in the first quarter of 2025 (OECD, 2025a).

Figure 1. Uncertainty around trade policy remains globally high

Trade policy uncertainty indices

Note: All series shown until October 2025.
Source: Caldara, et al. (2019); Arbatli, et al. (2022); Davis, et al. (2019).

Persistent uncertainty will lower trade

To explore these effects, the impact of trade policy uncertainty on global trade volumes was estimated using a panel vector autoregression (VAR) model with quarterly data for 56 countries – 33 developed economies and 23 emerging market economies – over the period 2017-2025. The model includes the newspaper-based global trade policy uncertainty index of Caldara et al. (2019).

The results from a trade uncertainty shock are shown in Figure 2. Initially, there is a small rise in imports, which is consistent with possible front-loading. A similar pattern is apparent in investment, which again may stem from a wish to bring forward large, planned expenditures ahead of future trade policy changes.  However, over time trade policy uncertainty shocks are associated with lower trade, as well as lower consumption and investment. The downside impact of a trade policy uncertainty shock is estimated to peak after one year, with merchandise import growth being reduced by 4.2 percentage points.

Figure 2. Trade uncertainty is accompanied by short-term front-loading effects

Impact of uncertainty on real imports, investment and consumption growth
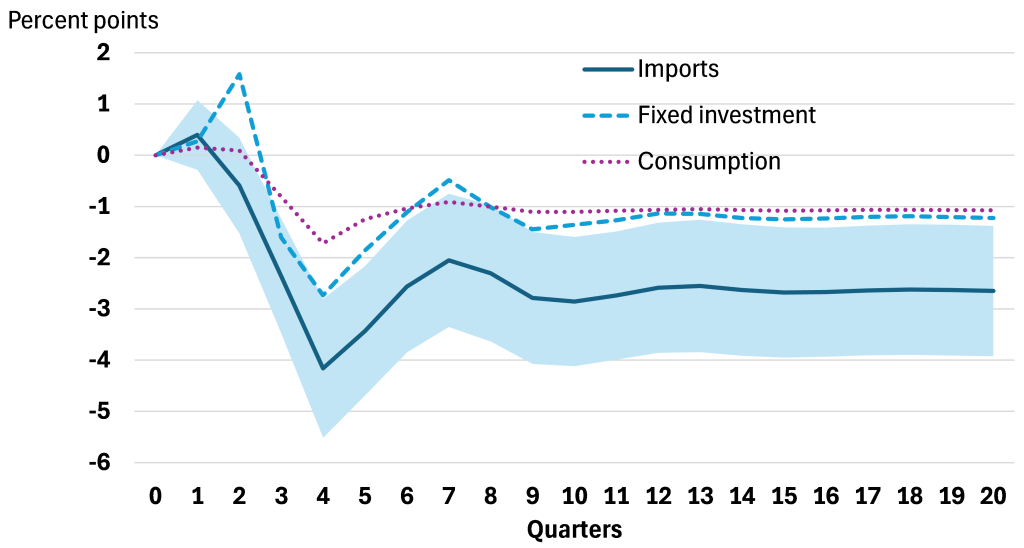
Note: The figure compares the estimated cumulative impact of a one standard deviation increase in the trade policy uncertainty index on the quarterly growth rate of merchandise import volumes, investment, and household plus government consumption volumes computed across 33 advanced countries and 23 emerging market economies. The shaded area depicts the 90% confidence band around the estimates. The dynamic panel VAR model is estimated using a generalised method of moments approach over 2017Q1-2025Q2 and it includes four lags of all variables.
Source: OECD Economic Outlook 118 database; OECD calculations.

Given the wide range of estimates from existing studies of the impacts of trade policy uncertainty, a number of checks were conducted to assess the robustness of these findings. First, the findings are robust even if data from 2024 and 2025 are excluded. Second, a related model using nominal bilateral trade amongst the G20 countries also yielded broadly similar results, albeit with larger negative effects on trade, consistent with the literature (Nana et al., 2025). Finally, the results were found to be robust to using an alternative text-based measure of uncertainty, based on analyst reports, with similar, although not identical, patterns, and without front-loading effects.  

Import tariff announcements amplify uncertainty damage

Announcements of policy changes – even if they are restrictive – could mitigate uncertainty by making policy clear and reducing speculation, or they could add to the trade inhibiting effects of uncertainty by increasing the expected probability of negative trade policy outcomes and expected losses (Handley and Limão, 2022). To test this, we added the number of products affected by an import tariff at the date of announcement as a separate variable in the model. Global merchandise import growth is found to be reduced by an additional one and a half percentage points after 1 year following an uncertainty shock and by two percentage points after 3 years (Figure 3, Panel A).

Finally, there is some evidence that emerging market economies have a higher sensitivity to trade policy uncertainty than advanced economies (Figure 3, Panel B). One possible factor behind this is that several countries in the emerging markets sample are manufacturing hubs, with a sizeable share of imports (foreign value added) in their manufactured exports. Trade in such economies is likely to be particularly sensitive to uncertainty (Nana et al., 2025).

Rules-based trade policies would help address uncertainty shocks

The harmful effects of trade policy uncertainty are occurring against a backdrop of elevated policy uncertainty more generally. This negative impact is likely to have been exacerbated this year by the large number of products and countries potentially exposed to trade policy changes. As stressed in the latest OECD Economic Outlook enhanced international cooperation to bolster and ensure rules-based, fair, trade policies would minimise trade-related uncertainty and likely support trade and investment.

Figure 3. Trade uncertainty has heterogeneous effects across countries and products
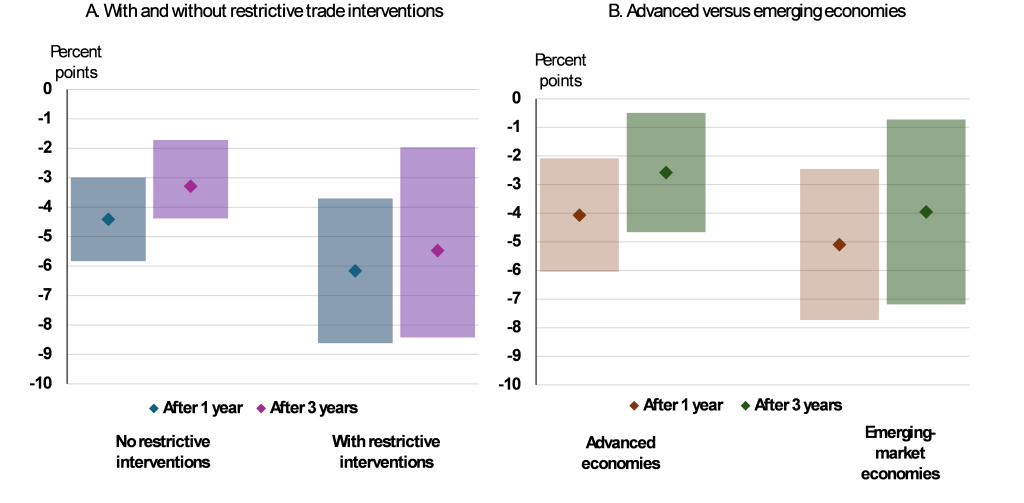
Note: Panel A compares the estimated cumulative impact of a one standard deviation increase in the trade policy uncertainty index on the quarterly growth rate of merchandise import volume with and without accounting for harmful trade policy interventions proxied by the number of imported products affected by a tariff at announcement date. Panel B compares the estimated impact on merchandise import volumes separately for advanced countries and emerging-market economies. Real investment and consumption have been replaced by the industrial production index to enable the inclusion of China in the country sample. The shaded area depicts the 90% confidence band around the estimates.
Source: OECD Economic Outlook 118 database; Global Trade Alert Data Center; OECD calculations.

References

Arbatli Saxegaard, E., S. Davis, A. Ito and N. Miake (2022) “Policy uncertainty in Japan”, Journal of the Japanese and International Economies, Volume 64.

Caldara, D., M. Iacoviello, P. Molligo, A. Prestipino and A. Raffo (2019), “Does Trade Policy Uncertainty Affect Global Econmic Activity?” FEDS Notes September 4, Board of Governors, Federal Reserve System.

Davis, S., L. Dingqian and S. Xuguang (2019), “Economic Policy Uncertainty in China Since 1949: The View from Mainland Newspapers”, Fourth Annual IMF-Atlanta Fed Research Workshop on China’s Economy.

Handley, K. and N. Limão (2022), “Trade Policy Uncertainty,” NBER Working Paper 29672.

Nana, I., R. Ouedraogo, and J.T. Sampawende (2025), “The heterogenous effects of uncertainty on trade”, IMF Working paper, No.139.

OECD (2025a), OECD Economic Outlook, Volume 2025 Issue 2: Resilient Growth but with Increasing Fragilities, OECD Publishing, Paris, https://doi.org/10.1787/9f653ca1-en.

OECD (2025b), OECD Economic Outlook, Volume 2025 Issue 1: Tackling Uncertainty, Reviving Growth, OECD Publishing, Paris, https://doi.org/10.1787/83363382-en.

Sampognaro, R. (2025), “Regardless of the outcome, uncertainty in trade policy will have significant effects on global trade”, OFCE blog, April 2025.



Winds of change: The effects of tariffs on equity markets

By Caroline Roulet and Srdan Tatomir

The international trade landscape is changing. The new tariffs introduced by the United States (US) this year up to mid-May are estimated to have raised the effective tariff rate on US merchandise imports to 15.4%, from just over 2% in 2024, the highest rate since 1938 (OECD, 2025). This has led to retaliation from China and, to a more limited extent, Canada. At the same time, indicators of trade policy uncertainty are at the highest levels since 1960 and several magnitudes higher than in 2018-2019 (Caldara et al, 2019).

Higher tariffs and higher trade-related uncertainty are expected to weigh on global trade and economic growth as outlined in the latest OECD Economic Outlook. It will take some time for the full effects of these changes on the real economy to emerge. Financial markets can provide an early signal about the potential impact of trade developments on companies around the world.

During the US-China trade tensions in 2018-2019, the equity prices of exposed companies weakened and this was subsequently associated with lower levels of activity. In the US, equity prices for publicly listed companies exposed to Chinese tariffs experienced a significant and persistent decline following tariff-related policy announcements, with larger declines for firms that were indirectly exposed to higher tariffs through their supply chains (Amiti et al, 2025; Yilmazkuday, 2025). US firms competing with imported Chinese goods benefited from less competition, but the rise in their equity prices was small (Huang et al, 2020). The tariff-related equity price declines were strongly correlated with lower profits and weaker output, employment and productivity levels, and higher perceived risks of corporate default (Amiti et al, 2025; Huang et al, 2020). In China, publicly listed firms exposed to the US also experienced declines in their equity prices (Huang et al, 2020). Higher US tariffs dented firms’ output and employment in Chinese regions more exposed to trade (Chor and Li, 2021).

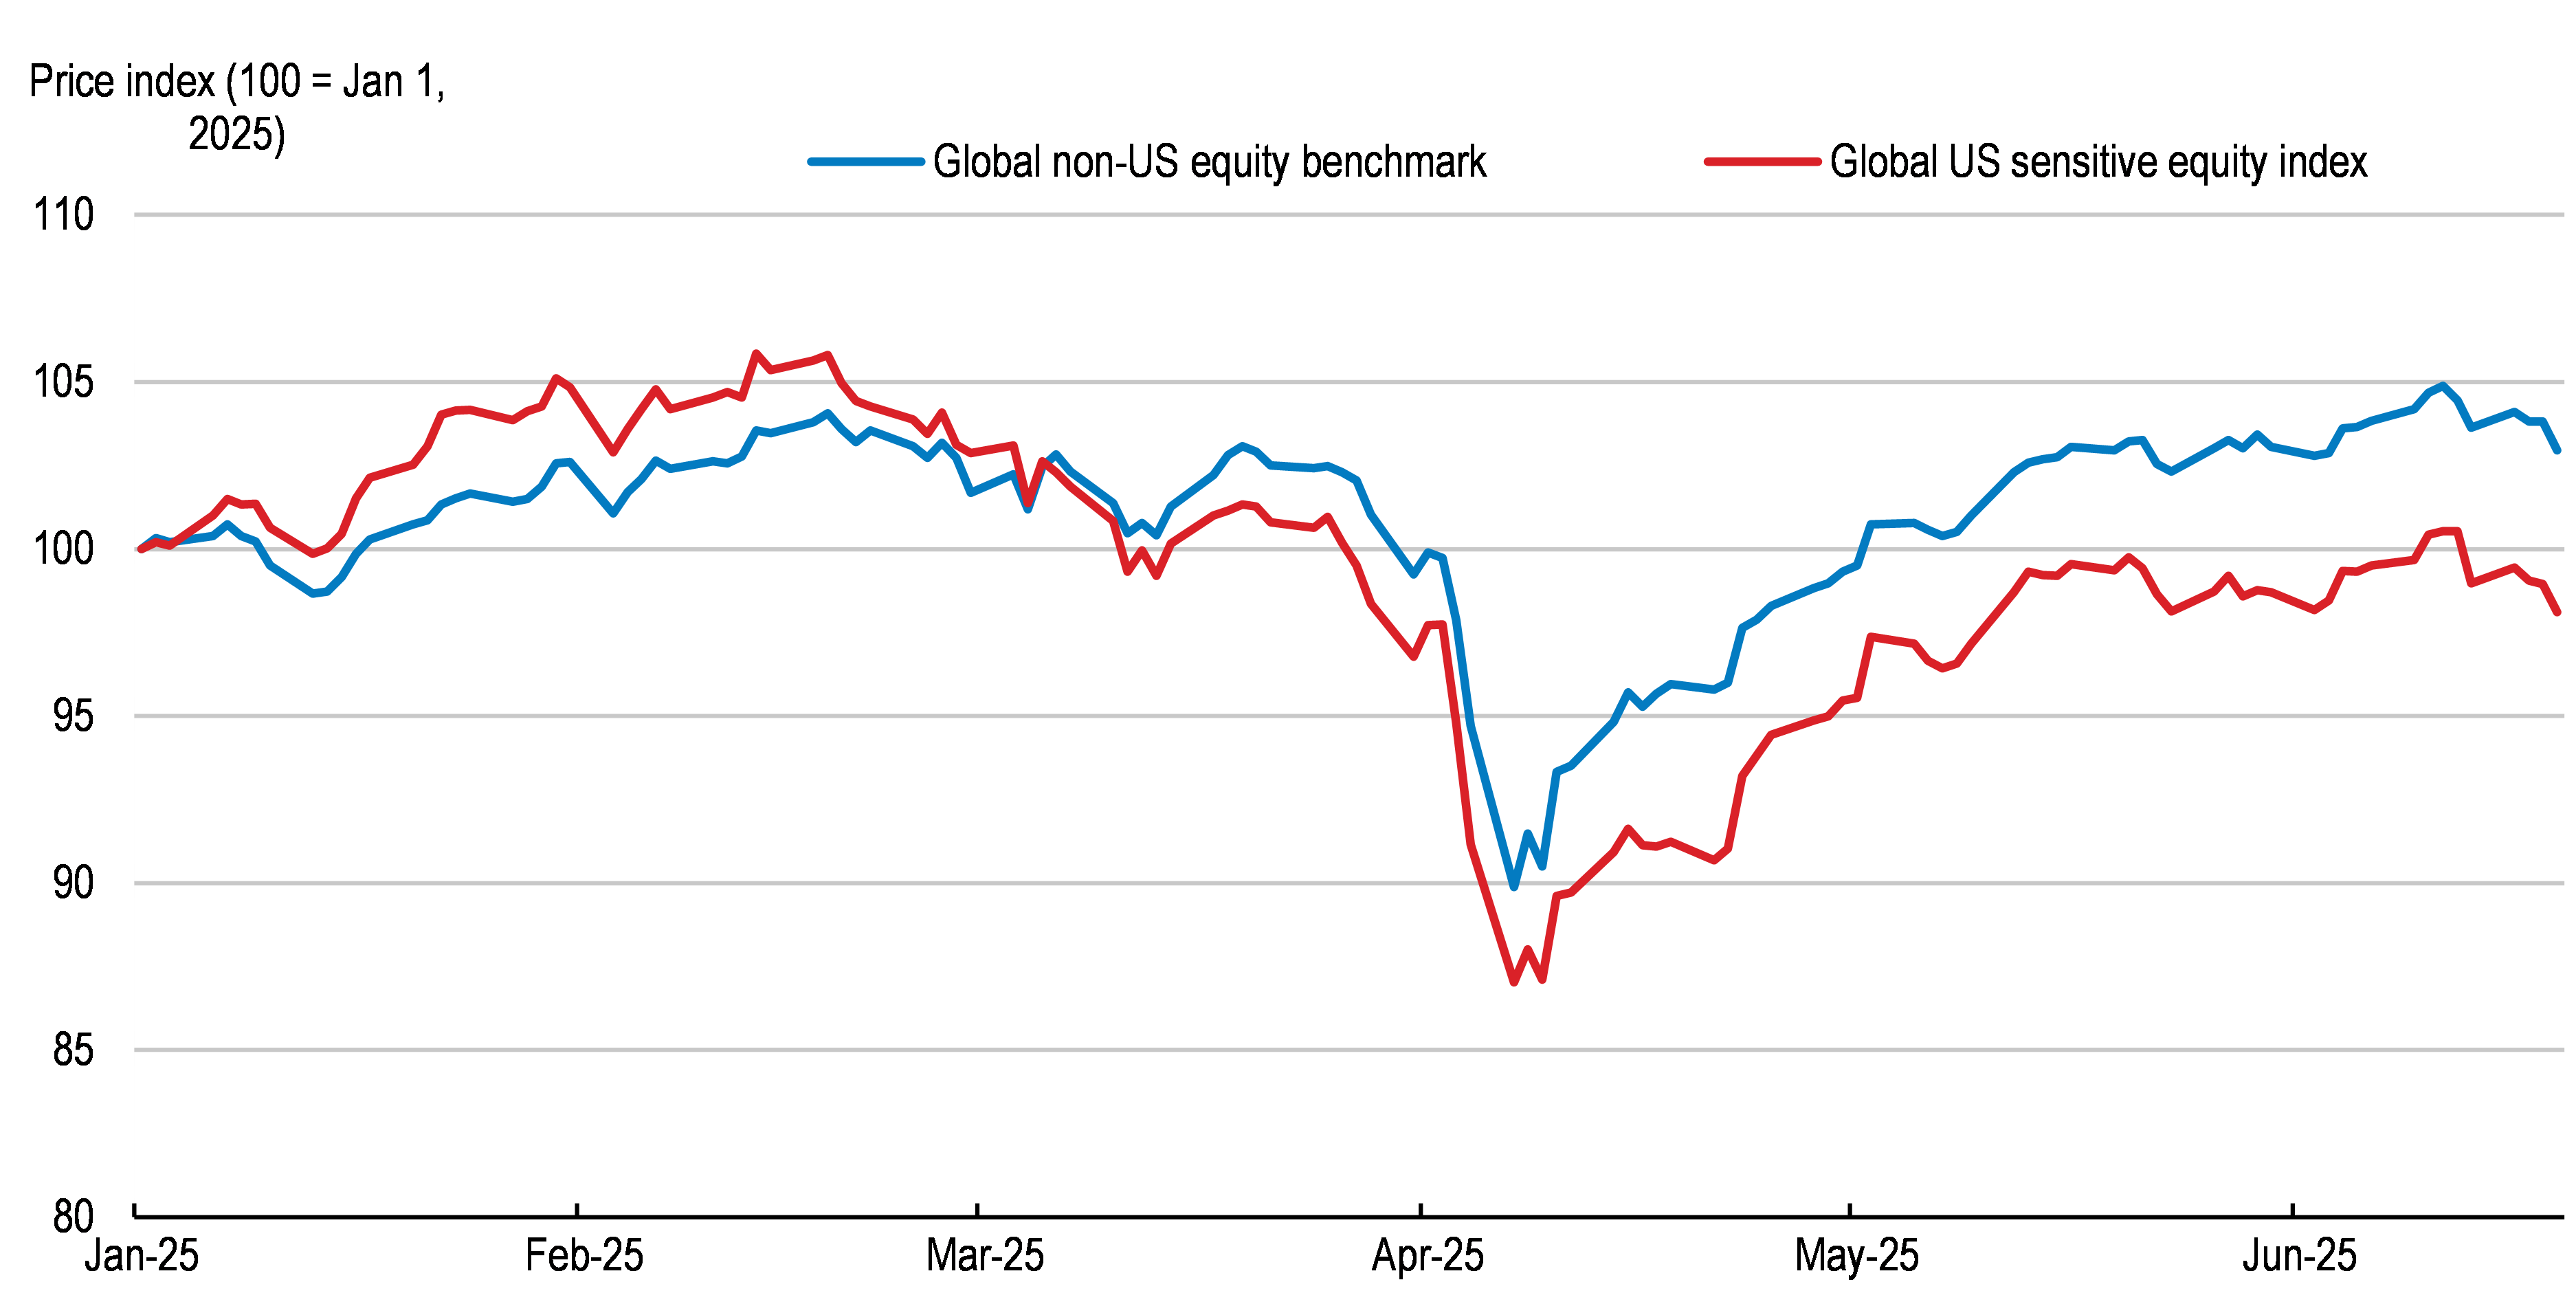
A similar set of concerns have appeared in 2025 in corporate equity markets. The equity prices of foreign companies highly exposed to the US economy have lagged behind the broader market since February. Following the substantial increase in US tariffs announced in April, the gap relative to January 1 widened to around 5 percentage points, which has persisted to date (Figure 1). Publicly listed companies in China, other emerging-market economies and in the Asia-Pacific region have been hit the hardest relative to their respective broader regional benchmarks, with European companies hit to a lesser extent so far (Figure 2).

Figure 1: Equity markets point to weaker performance for companies exposed to the US

Note: Based on data up to 19 June using a sample of 1,884 non-financial corporates in 28 selected advanced and emerging-market economies. The global US exposed index reflects the equity market performance of firms that are particularly sensitive to recent US policy changes, while the global non-US equity benchmark represents the broader non-financial corporate equity market. Exposed corporates are defined as ones with sales in the United States of 20% or more of their total sales. Indices are weighted by market capitalisation.
Source: OECD calculations.

In China, this could reflect the much higher increase in tariffs compared to most other US trading partners, as well as the sizable boost to domestically focused companies from policy support (OECD, 2025). In contrast, risks of a slowdown in growth have affected the equity prices of all companies in North America, resulting in smaller differences between companies exposed to the US and those who are domestically focused. The announced increase in tariffs has been relatively broad across different categories of goods and, when comparing sectors across countries, the negative effects have weighed on equity prices in many of them. However, companies exposed to the US in the discretionary consumer sector have tended to be more strongly affected relative to their respective sectoral benchmark, whereas technology and healthcare companies have seen little impact so far. Imports of pharmaceuticals and semi-conductors have remained exempt from new US import tariffs up to now.

In the United States, US companies with a relatively strong reliance on foreign sales initially traded at a discount in March and April, but the gap with other US companies has subsequently closed and become positive more recently (Figure 3). This could reflect initial expectations of retaliatory tariffs that have generally not materialised so far. Weaker US growth prospects relative to other countries, partly due to high uncertainty as well as higher costs of imported intermediate inputs, might be also disproportionately affecting US companies focused on the domestic market. However, historical experience suggests that the full impact of tariffs and trade-related uncertainty on equity prices develops over time (Adolfsen and Harr, 2025; Yilmazkuday, 2025). US companies are accumulating inventories ahead of anticipated tariff increases but surveys suggest they are already receiving fewer new orders, revising earnings forecasts downwards and scaling back investment plans (OECD, 2025).

Figure 3: Tariff effects have receded in US equity markets

Note: Based on data up until 19 June using a sample of 2,157 US non-financial corporates. Internationally exposed US corporates are defined as those with international sales of 20% or more of their total sales. Corporates that are not internationally exposed have a ratio of international sales to total sales of 0%. The US equity benchmark is the S&P 500 equity benchmark, excluding financials. All indices are weighted by market capitalisation.
Source: OECD calculations.

Overall, there have been clear signs in equity markets of differences across companies according to their potential exposure to tariff barriers, with the equity prices of foreign companies more highly exposed to the US market having underperformed others. As the announced tariffs have been relatively broad, the negative effects have weighed on the equity prices of most companies, but especially ones in the consumer goods sector. The equity prices of US companies with significant international exposure have recovered since falling sharply as tariffs began to be raised, but potential remains for further and unexpected trade policy events to disrupt markets again.

References

Adolfsen, J., F. and T. Harr (2025), Disentangling trade policy uncertainty and equity market performance, VOXEU column, May.

Amiti, M., Gomez, M., Kong, SH, and D. Weinstein (2025), Trade protection, stock-market returns, and welfare, NBER Working Paper No. 28758.

Caldara, D., Iacoviello, M., Molligo, P., Prestipino, A., and A. Raffo, (2019), The Economic Effects of Trade Policy Uncertainty, Journal of Monetary Economics, data retrieved from https://www.matteoiacoviello.com/tpu.htm on June 2, 225.

Chor, D., and B. Li (2021), Illuminating the effects of the US-China tariff war on China’s economy, NBER Working Paper No. 29349. 

Huang, Y., Che, L., Sibo L., and T. Heiwei, (2020), Trade Networks and Firm Value: Evidence from the U.S.-China Trade War, Centre for Economic Policy Research Working Paper DP14173.

OECD (2025), Economic Outlook June 2025, OECD Publishing, Paris.

Yilmazkuday, H (2025), U.S. Tariffs and Stock Prices [forthcoming], Finance Research Letters.


Extending trade benefits to more firms and workers

By Aida Caldera, Alberto Gonzalez Pandiella and Alessandro Maravalle

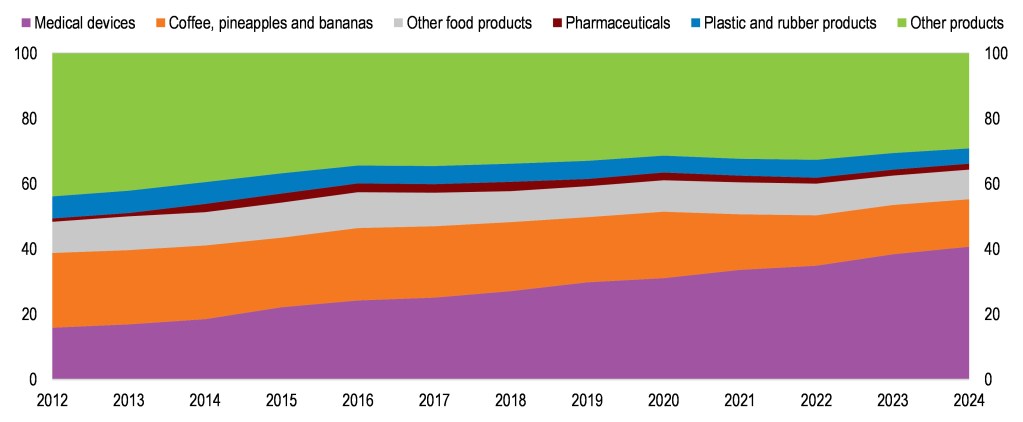
At the beginning of the 1990s, Costa Rica was primarily known for exporting agricultural products like bananas and coffee, along with its thriving tourism sector. Today, places like Alajuela have become global hubs for advanced manufacturing, particularly in the medical devices sector. A strong and sustained commitment with open trade explains this remarkable transformation.  Thanks to a more diversified export basket and a shift towards higher value-added goods and services (Figure 1), Costa Rica’s economy has grown more than other OECD countries and regional peers over the last three years and was more resilient to recent shocks. This success story is not without clouds or challenges, as detailed in the 2025 OECD Economic Survey. A long-standing challenge is that not all workers, companies and regions have so far benefited from trade.

Figure 1. High-tech products are a growing share of Costa Rica’s exports

Exports by type of product, % of total good exports

Source: Banco Central de Costa Rica.

Maximising trade benefits

There remain ample opportunities for Costa Rica to capitalize on its trade openness and FDI attractiveness. With Costa Rica’s exports remaining concentrated in a few destinations ongoing efforts to diversity trade agreements and enhance trade facilitation, which have regained considerable impetus since 2022, will facilitate stronger integration into global and regional value chains. Nearshoring offers new opportunities for Costa Rica to extend trade benefits to more workers, firms and regions. However, several barriers might prevent these opportunities from materializing. Continuing the path of reform to enhance education, foster innovation, improve infrastructure and promote stronger competition would help Costa Rica seize maximise trade benefits.

Costa Rica’s well-educated workforce has been traditionally key to attract FDI and develop value added exports. However, now large skills shortages pose a critical threat to Costa Rica’s FDI attractiveness. A comprehensive education reform is underway, but key timelines and milestones are still unclear. The ongoing efforts to reform education should prioritise the increase in the number of technicians and graduates in STEM areas and ensure that university education is better aligned with labour market demands.

Boosting innovation is crucial for Costa Rican firms to access international markets. However, interactions between public universities and businesses are weak, and most innovation funding goes directly to universities without impact evaluations. Competitive performance-based funding is limited, compared to other OECD countries. Strengthening interaction between public universities and businesses, and introducing  impact evaluations to innovation funding, would help boost firms’ innovation.

Infrastructure bottlenecks are large, driving up trade costs and limiting the participation of remote regions and SMEs in international trade. Key issues include poor-quality roads and overcrowded ports. The low quality of transport infrastructure can be attributed to underspending, deficient strategic planning and inefficient capital project execution, with only 30% of budgeted capital spending getting executed. Strengthening planning and design of transport projects and enhancing budget management  would reduce delays and cost overruns and contribute solve Costa Rica’s large infrastructure gaps.

Finally, boosting competition in domestic markets would help Costa Rican firms access better inputs at lower costs. Despite ongoing efforts to improve competition in some areas, , such as removing anticompetitive practices in professional services and reducing the large and complex stock of regulations, Costa Rica still has some of the strictest regulations in the OECD. Continuing to increase the Competition Authority’s budget is crucial for identifying and addressing anticompetitive practices.

References

OECD (2025), OECD Economic Surveys: Costa Rica 2025, OECD Publishing, Paris, https://doi.org/10.1787/048cf07b-en


Stepping up structural reforms to improve Egypt’s business climate

by Ania Thiemann, Economist and Competition Expert, Competition Division.

Egypt’s challenging business climate is holding back productivity and therefore also living standards. Labour productivity is still far below the OECD average (Figure 1), with low overall investment and a declining share of private investment in the total. Low investment in innovation, and research and development (R&D) also contributes to low productivity growth, as Egypt spends less than 1% of GDP on R&D. Market mechanisms, such as business entry and exit, and growth of the most efficient firms, appear to be weaker than in many similar emerging markets. Underlying these facts are deep-seated structural causes that impede market competition, investment and efficient resource allocation. These barriers stifle the country’s potential for long-term sustainable growth and restrict the development of a robust private sector. To ensure sustainable economic growth, as set out in Egypt’s National Structural Reform Programme, thorough policy reforms are required that can boost market competition. Regulatory and trade barriers, as well as a dominant state presence need to be addressed to revive private sector activity.  

Figure 1: Low output per worker is related to low investment

Note: Data for Egypt in all three panels refer to fiscal years (from July of indicated year to June of the following year). Neighbouring countries refer to Algeria, Israel, Jordan, Lebanon, Morocco, Tunisia and Türkiye.
Source: IMF, World Economic Outlook database – October 2023; OECD, National Accounts database; Ministry of Planning and Economic Development; and OECD calculation.

Removing regulatory barriers to enhance market entry and expansion

A central and long-standing challenge is the heavy regulatory burden that acts as a barrier to market entry and expansion, while also promoting informality. Complex and lengthy processes for obtaining business licenses and permits during the post-establishment phase constrain both domestic businesses and exporters (Figure 2). Despite recent reforms, the administrative load remains heavy, stifling Egypt’s business dynamism compared to regional and global averages, with comparatively low entry and exit rates. Moreover, overall regulatory quality remains low, reflecting lengthy and opaque decision-making processes and implementation.

Figure 2: Business licensing is a constraint on domestic businesses and exporters

Percentage of firms in Egypt identifying business licensing and permits as a major constraint, 2020

Note: Share of respondent firms out of 3075 firms surveyed.
Source: World Bank, Enterprise Surveys.

To support a more dynamic private business sector, Egypt needs to streamline its business registration and licensing processes. Licensing requirements can be replaced by online registration in most cases, while a more efficient on-line application system would speed up processes. A new online platform for business registration was opened up in 2023, but difficulties remain with local permits. Simplifying procedures and reducing bureaucratic hurdles can encourage new business formation and attract more investment. Additionally, improving the transparency of administrative procedures would also reduce opportunities for corruption, which is a crucial step towards creating a fair and competitive market landscape.

Strengthening competitive pressures through trade and investment

High tariff and non-tariff barriers to trade mean that the Egyptian market remains relatively insulated from global competition. Such trade restrictions limit the country’s integration into global value chains and reduce the spillover benefits of foreign technology and know-how, which are essential for boosting productivity.

Liberalising trade policies and reducing tariffs can enhance Egypt’s competitiveness on the global stage. The creation of the National Single Window (Nafeza) to support external trade, should help speed up customs procedures. Border clearance has improved but remains comparatively slow (Figure 3). To support faster import release, the authorities are working on a new risk management system, which should speed up processes by reducing the number of inspections to those selected by the risk matrix. However, Egypt should also simplify its tariff regime, as tariffs remain high and unwieldy, with particularly high tariffs for agricultural products, and for products that compete with Egyptian manufactured goods (with tariff rates of 40-60%), in a system with 7 850 tariff lines. Foreign traders whose products already meet domestic standards should not have to preregister their products, and import licences could be replaced by a simple registration with the customs authorities, as is the case in Europe. A more open and predictable trade regime would benefit domestic businesses and investors, as well as supporting more inward foreign investment. This in turn would facilitate the transfer of technology and expertise, thus foster productivity growth.

Figure 3: High import tariffs and slow border clearance are hampering trade

Note: In Panel A, data for the countries presented refer to 2019 except for Thailand (2015), Tunisia (2016), Israel (2017), Mexico (2018), Jordan and Malaysia (2020). Weighted mean applied tariff is the average of effectively applied rates weighted by the product import shares corresponding to each partner country. When the effectively applied rate is unavailable, the most favoured nation rate is used instead.
Source: World Bank, World Development Indicators; World Economic Forum (2019), Global Competitiveness Index 4.0.

Reducing the state’s footprint in the economy

State-owned enterprises (SOEs) play a significant role in Egypt’s economy, to the detriment of competitive market conditions by crowding out private sector activity. The government’s recent steps to level the playing field, though commendable, need to be more comprehensive and sustained. Over-reliance on SOEs in various sectors, such as utilities and transport, but also in manufacturing, prevents private enterprises from competing on an equal footing. Privatisation and divestment of SOEs should be pursued more aggressively to reduce the state’s dominance in the market. This move will not only improve efficiency but also stimulate private investment. The OECD’s guidelines on privatisation could serve as a valuable framework for Egypt in this regard.

Further actions to support private businesses: Access to finance and digital diffusion

Access to finance remains a significant hurdle for many businesses in Egypt. Banks overwhelmingly prefer to lend to the government, leaving private enterprises, especially small and medium-sized enterprises (SMEs), with limited financing options which hampers business expansion and innovation. Enhancing financial inclusion by opening up the banking sector to competition, notably by FinTechs with Open Banking regulation, can mitigate this issue. Policies aimed at improving the creditworthiness of SMEs and developing a robust microfinance sector will also support private sector growth. Improving digital financial services could play a critical role in this transformation.

Digital inclusion is key to boost productivity and competitiveness. However, Egypt lags behind in terms of digital infrastructure, and adoption by SMEs. The legal framework for digital business models needs significant improvement to allow for dematerialised businesses to expand. Investing in digital infrastructure and fostering a regulatory environment that supports digital innovation are therefore crucial steps to create a more vibrant business sector and help enhance overall economic efficiency.

References:

Thiemann, A. (2024), “Improving Egypt’s business climate to revive private sector growth”, OECD Economics Department Working Papers, No. 1808, OECD Publishing, Paris, https://doi.org/10.1787/a4b2ce91-en.

OECD (2024), OECD Economic Surveys: Egypt 2024, OECD Publishing, Paris.

OECD (2019), A Policy-Makers Guide to Privatisation:  https://www.oecd.org/en/publications/a-policy-maker-s-guide-to-privatisation_ea4eff68-en.html.


Strengthening economic resilience in Switzerland through trade

By Erik Frohm

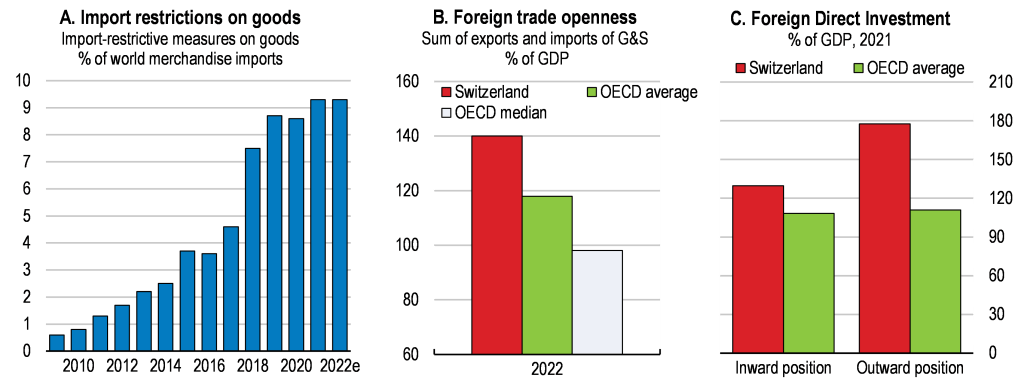
The COVID-19 pandemic and escalating conflicts, such as Russia’s war of aggression against Ukraine, have sent shockwaves through energy markets and global value chains. This has reinforced the imperative to foster economic resilience in many countries, while raising calls for self-reliance, more active industrial policies to benefit domestic industries and trade restrictions (Figure 1).

For Switzerland, a country deeply embedded in global markets, navigating these challenges is vital. Central to Switzerland’s success has been its steadfast commitment to openness, enabling the flow of goods and services, capital, people and ideas. Although trade may act as a conduit for adverse shocks, less integration into the global economy would not make Switzerland more resilient, as highlighted in the 2024 Economic Survey. Instead, stable and predictable trade and investment regimes reduce uncertainty and lower trade costs. This empowers companies to diversify and fortify their supply chains cost-effectively, as open trade makes markets “thicker”, by expanding the number of possible suppliers and buyers.

Figure 1. Global trade restrictions pose challenges for Switzerland’s open economy

Notes: For panel A, the chart denotes the global cumulative trade coverage of restrictions on goods estimated by the WTO Secretariat, based on information available in the TMDB on import measures recorded since 2009 and considered to have a trade-restrictive effect. The estimates include import measures for which HS (Harmonised Commodity Description and Coding System) codes were available. The figures do not include trade remedy measures.
Source: WTO November 2022 Report; Economic Outlook database; OECD International Direct Investment Statistics database.

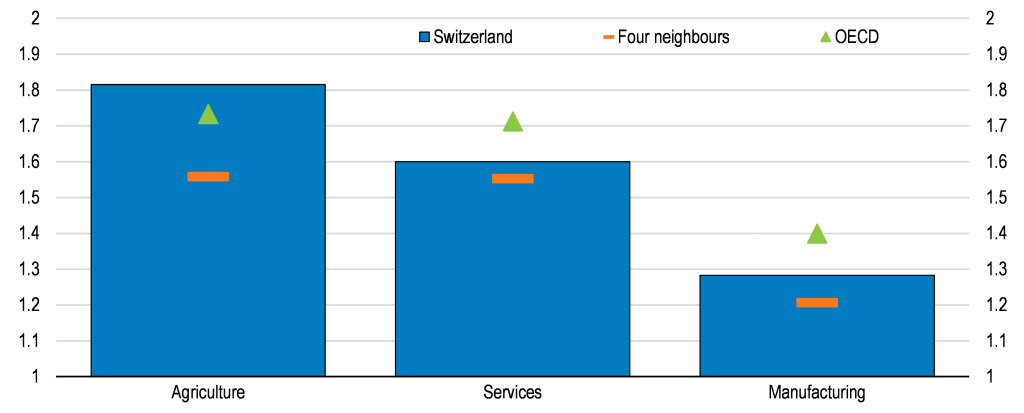
According to the WTO’s Trade Cost Database, effective trade costs, representing all factors constraining international trade versus domestic activity, are lower in Switzerland than the OECD average in manufacturing and services, yet higher than in the four neighbouring countries (Austria, Germany, France and Italy), see Figure 2. Trade costs can be lowered in many ways. Tariff cuts, deeper or new free trade agreements (FTAs), improved at-the-border regulations and procedures, as well as investments in digital infrastructure all help. In this regard, Switzerland unilaterally abolished tariffs on industrial goods from January 2024. Similarly, the signing of an FTA with India in March 2024 together with the EFTA member states (Iceland, Lichtenstein and Norway) represents an important milestone. Yet barriers to trade remain high in agriculture and the services sector. Less direct support and more import competition would raise agriculture productivity and lower prices. Minimising barriers to services trade will increase the gains from digital transformation and boost competitiveness.

Figure 2. There is scope to reduce effective trade costs, in particular in services and agriculture

Notes: The effective trade costs are estimates of the costs involved with international trade relative to domestic activity. The figure shows trade cost estimates from the WTO, averaged across ISIC Rev. 4 sub-sectors in 2018. The trade costs are expressed as ad-valorem equivalents, in logarithms. Four neighbours refer to Austria, Germany, France and Italy. OECD is a simple average of OECD countries.
Source: WTO.

Most of Swiss exports and imports flow within FTAs. The usage rate is 73% for imports, which is higher than for the EU average yet lower than best performing countries. There are several reasons why companies may choose not to use the FTAs, depending on the products they trade and their preferential rules of origin. Complying with the rules may be difficult due to complex information requirements or involve large administrative costs. Reducing the administrative burden and providing centrallised, clearly structured and understandable information could increase the use of FTAs.

With the EU standing as Switzerland’s largest trading partner, the bilateral relationship is of paramount importance. The current partnership is governed by roughly 120 separate treaties, but faces uncertainties as efforts to reach a comprehensive “framework agreement” stalled since 2021. The Federal Council’s adoption of a new negotiating mandate with the EU in March 2024 is a welcome step, and opens the door to continued deep economic integration. An erosion of the Switzerland-EU partnership would raise uncertainty, be harmful for Switzerland’s external trade and competitiveness and undermine its economic resilience.

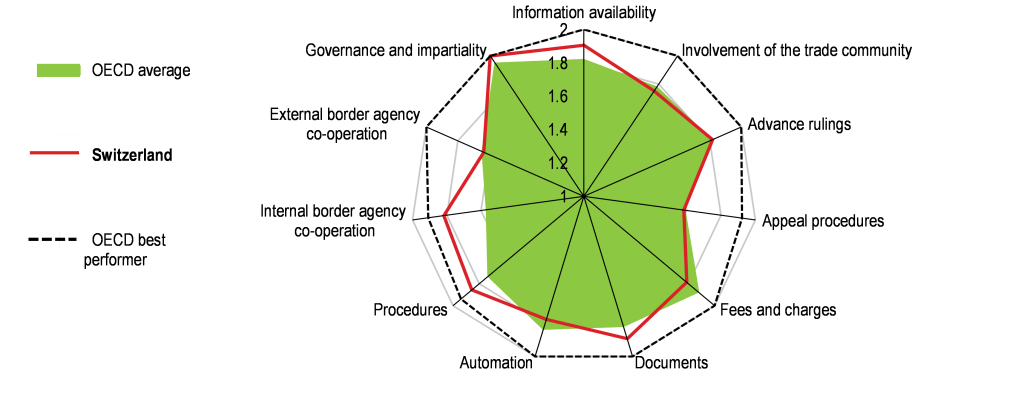
Addressing behind- and at-the-border regulations, as well as enhancing digital connectivity, are crucial steps to facilitating trade and limiting bottlenecks. While Switzerland outperforms the OECD average in several aspects of trade facilitation, there is further room for improvement, particularly in areas such as fees and charges, process automation, and external border agency cooperation (see Figure 3). Streamlining information availability and pre-arrival processing procedures for imports can significantly reduce the time and cost burden for businesses, particularly SMEs looking to expand internationally and diversify their supply chains.

As Switzerland charts its course through a changing global economic landscape, maintaining openness in trade and reducing regulatory burdens will be key to strengthening economic resilience. This approach can allow companies to improve the resilience of their supply chains, without unduly increased state influence or costly public support.

Figure 3. Improving trade facilitation measures would help reduce bottlenecks

OECD Trade Facilitation Indicators, from 0 to 2 (best performance), 2022

Source: OECD (2022), Trade Facilitation Indicators.   


Restoring growth

Economic Outlook November 2023 cover image

by Clare Lombardelli, OECD Chief Economist

Inflation is easing, but growth is slowing. The tightening of monetary policy needed to tackle inflation is taking effect. Despite stronger-than-expected GDP growth in 2023, tightening financial conditions, weak trade, and subdued confidence are taking a toll. Housing markets and bank-dependent economies, particularly in Europe, are feeling the impact.

The pace of growth is uneven. Emerging markets are generally faring better than advanced economies. Europe’s growth lags behind North America and major Asian economies. Inflation, while easing, remains a concern.

We are projecting a soft landing for advanced economies, but this is far from guaranteed. The relationship between inflation, activity and labour markets has changed, making the full impact of monetary policy tightening hard to judge. In the United States, the economy is demonstrating more strength than expected, and there is a risk that inflation proves to be persistent. In the euro area, the full impact of tighter monetary policy is still to appear and activity may be hit more strongly than we expect.

Many emerging markets have shown considerable resilience over the past year, but countries characterised by structural debt vulnerabilities have come under market scrutiny.

Global trade is weak. Not only cyclical, but also structural factors are causing a slowdown in the rate at which value chains are integrating across countries. Opportunities for growth, particularly from greater services trade, are being missed. We must revive global trade. Resilience in global value chains is best delivered by diversification, not by protectionism and inward-looking policies.

In many countries, fiscal pressures are mounting. Demographic changes, decarbonisation, and a combination of rising interest payments and slow growth mean countries face a challenging fiscal outlook. Governments need to take bold action to reduce such pressures and give a greater focus to growth in their policy making. That means reforming labour market and pensions policies, increasing competition, and using fiscal levers to increase human capital and productivity enhancing investment, including the investment needed to deliver the green transition.

In summary, the global economy is grappling with inflation, slowing growth, and mounting fiscal pressures. Policymakers must prioritise macroeconomic stability, structural reforms, smart fiscal policies and international cooperation to foster sustainable and inclusive growth.

For more info and data visit: www.oecd.org/economic-outlook/november-2023/

References

OECD (2023), OECD Economic Outlook, November 2023: Restoring Growth, OECD Publishing, Paris


Shifting sands: trade partner patterns since 2018

by Seung-Hee Koh, Catherine MacLeod and Elena Rusticelli

Global trade policy is undergoing a sea-change. The share of global merchandise imports subject to trade restrictions has risen particularly rapidly since 2018, initially due to a sharp increase in tariffs on bilateral trade between the United States and China. Since then, trade policy choices have steadily become more harmful to global trade in goods (Figure 1, Panel A). Trade policy uncertainty has also increased, alongside policy discussions about the re-location of value chains and ongoing changes in the design of national industrial policies. The latest OECD Economic Outlook (OECD, 2023) analyses trends in imports of manufactured goods across major OECD economies to understand what impact this has had on trade patterns.

So far, the increasing use of trade policies has coincided with a period of subdued world trade growth, but has not reduced global merchandise trade intensity (the ratio of trade in manufactures and commodities to GDP in volume terms). Nonetheless, since the global financial crisis, global trade intensity has risen only marginally, following a period of very sharp rises in the 1990s and early 2000s. The COVID crisis saw a shallower decline and faster rebound in merchandise trade intensity than the global financial crisis (Figure 1, Panel B). In 2022, global trade in goods was 22% of global GDP in volume terms, marginally higher than 2018.

The recent resilience of trade in volume terms may be linked to the huge increase in demand for goods during the COVID pandemic, as well as strong policy support during the pandemic and energy crises. Merchandise trade as a share of GDP generally rose in OECD countries between 2018 and 2022, including in Europe and Japan, offsetting a decline in Chinese merchandise trade intensity. However, merchandise trade intensity was relatively unchanged in the United States, where weak export growth offset a rise in import intensity.

Underneath the general rise in the value and volume of trade, imported manufactured goods at a country-level reveal important and differing shifts in the composition of manufactured goods imports since 2018 in the major economies (Figure 2). A particular issue of policy interest is the evolution of trade with geographically distant partners for key inputs (far-shoring) compared to trade with geographically closer trade partners (near-shoring).   

  • Shifting far-shoring: In the US, there have been sharp declines in China’s share of manufactured imports since 2018 – which have typically coincided with rising import shares from dynamic Asian economies. This includes goods where the 2018 tariffs are still applied. Evidence of near-shoring is limited, with Mexico and Canada’s share of imports rarely rising in the same categories where China’s share has fallen.
  • Expanding far-shoring: in the EU, China’s weight in manufactured imports has continued to grow steadily. In contrast to the US, this has been alongside rising import shares for dynamic Asian economies. As for the US, there is limited evidence of near-shoring: the share of imports from other OECD countries in Europe has fallen, largely driven by changes in import shares from the United Kingdom.
  • Changes at the margin: In Japan, the shifts in import shares have been much smaller than in the US or Europe. Its trade with the wider Asian region has increased steadily, although increases have been larger for dynamic Asia than China. As in Europe, this has been accompanied by a decline in the share of imports from other advanced economies.

So far, these shifts in trade patterns have occurred whilst aggregate trade has continued to expand broadly in line with global activity. However, in a global economy with slowing long-term growth prospects the economic costs of more harmful trade policies may become more evident over time.


References:

OECD (2023), OECD Economic Outlook, Volume 2023 Issue 1, OECD Publishing, Paris, https://doi.org/10.1787/ce188438-en.


Policy changes to turn the tide

by Laurence Boone, OECD Chief Economist

For the past two years, global growth outcomes and prospects have steadily deteriorated, amidst persistent policy uncertainty and weak trade and investment flows. We now estimate global GDP growth to have been 2.9% this year and project it to remain around 3% for 2020-21, down from the 3.5% rate projected a year ago and the weakest since the global financial crisis. Short-term country prospects vary with the importance of trade for each economy though. GDP growth in the United States is expected to slow to 2% by 2021, while growth in Japan and the euro area is expected to be around 0.7 and 1.2% respectively. China’s growth will continue to edge down, to around 5.5% by 2021. Other emerging market economies are expected to recover only modestly, amidst imbalances in many of them. Overall, growth rates are below potential.

The mix between monetary and fiscal policies is unbalanced. Central banks have been easing decisively and timely, partly offsetting the negative impacts of trade tensions and helping to prevent a further rapid worsening of the economic outlook. Thereby, they have also paved the way for structural reforms and bold public investment to raise long-term growth, such as spending on infrastructure to support digitalisation and climate change. However, to date, other than a few countries, fiscal policy has been only marginally supportive, and not especially of investment, while asset prices have been buoyant.

The biggest concern, however, is that the deterioration of the outlook continues unabated, reflecting unaddressed structural changes more than any cyclical shock. Climate change and digitalisation are ongoing structural changes for our economies. In addition, trade and geopolitics are moving away from the multilateral order of the 1990s. It would be a policy mistake to consider these shifts as temporary factors that can be addressed with monetary or fiscal policy: they are structural. In the absence of clear policy directions on these four topics, uncertainty will continue to loom high, damaging growth prospects.

The lack of policy direction to address climate change issues weighs down investment. The number of extreme weather events is on the rise and insufficient policy action could increase their frequency. They may lead to significant disruptions to economic activity in the short term, and long-lasting damage to capital and land, as well as to disorderly migration flows. Adaptation plans are in their infancy, while mitigation, moving away from fossil fuels, through measures such as carbon taxes, has proved technically and politically challenging. Governments must act quickly: without a clear sense of direction on carbon prices, standards and regulation, and without the necessary public investment, businesses will put off investment decisions, with dire consequences for growth and employment.

Digitalisation is transforming finance, business models and value chains, through three main channels: investment, skills and trade. So far, only a small fraction of businesses appear to have successfully harnessed the strong productivity potential of digital technologies, which partly explains why digitalisation has been unable to offset other headwinds on aggregate productivity. Reaping the full benefits of digital technologies requires complementary investments in computer software and databases, R&D, management skills and training, which remains a challenge for too many firms. Digitalisation is also affecting people and work, because it confers a huge advantage to people whose main tasks require cognitive and creative skills, and penalises those whose work has a large routine element, and at the same time generates new forms of contractual arrangements that escape traditional social protection. But the policy environment to harness new technology – concerning skill upgrading, social protection, access to communication infrastructure, digital platform development, competition in digital markets and regulation of cross-border data flows – lags behind, making it difficult to reap the benefits of digitalisation in full.

The Chinese economy is structurally changing, rebalancing away from exports and manufacturing towards more consumption and services. Increasing self-sufficiency in core inputs for certain manufacturing sectors is reflecting a desire to move away from importing technology towards national production. A shift in energy utilisation to address pollution, and the rise in services also induce additional changes in Chinese demand for imports. China’s traditional contribution to global trade growth is set to slow and change in nature. While India is set to grow rapidly, its growth model is different and its contribution to global trade growth will not be enough to substitute for China as a global engine for traditional manufacturing.

Trade and investment are also structurally changing, with digitalisation and the rise of services, but also with geopolitical risks. The rise in trade restrictions is nothing new. About 1500 new trade restrictions have been implemented by G20 economies since the global financial crisis in 2008. Yet, the past two years have seen a surge in trade-restricting measures and an erosion of the rules-based global trading system, which is deep-rooted. Coupled with rising government support across a range of sectors, this induces disruptions in supply chains and reallocations of activities across countries that both exert a drag on current demand by reducing incentives to invest and undermine medium-term growth.
Against this backdrop, there is scope and an urgent need for much bolder policy action to revive growth. Reducing policy uncertainty, rethinking fiscal policy, and acting vigorously to address challenges raised by digitalisation and climate change, all have the potential to reverse the current slippery trend and lift future growth and living standards.

First, a clear policy direction for transitioning towards sustainable growth amidst digitalisation and climate challenges would trigger a marked acceleration of investment. Governments should focus not only on the short-term benefits of fiscal stimulus, but primarily on the long-term gains and to this end they should review their investment policy frameworks. The creation of national investment funds, focused on investing in the future, could help governments design investment plans to address market failures and take account of positive externalities for society as a whole. A number of governments already have dedicated funds of the sort, but their governance could be improved to ensure higher economic and social returns on investment.

Second, greater trade policy predictability and transparency could go a long way to reduce uncertainty and revive growth. For instance, there is a need to bring more transparency to the numerous forms of government support that distort international markets and to agree global rules on the transparency, predictability, reduction and prevention of such support.

Third, fiscal and monetary policies can be better activated, and to powerful effect if coordination prevails. There is scope to strengthen automatic stabilisers to preserve household income and consumption. Active coordination across the euro area would contribute to lift growth now. Moreover, should the outlook deteriorate more than we project, coordinated fiscal and monetary action across the G20, even allowing for the limited policy space some central banks have, could efficiently avert a recession, not least because coordination would bolster confidence.

The current stabilisation at low levels of economic growth, inflation and interest rates does not warrant policy complacency. The situation remains inherently fragile, and structural challenges – digitalisation, trade, climate change, persistent inequalities – are daunting. Rather, there is a unique window of opportunity to avoid a stagnation that would harm most people: restore certainty and invest for the benefit of all.

http://oecd.org/economic-outlook/


Growth is taking a dangerous downward turn

by Laurence Boone, OECD Chief Economist

For over 18 months, since the outbreak of trade hostilities, growth has been weakening, slowly but surely. In May 2018 the OECD, along with other organisations, was predicting global growth of around 4% for 2019, whereas our current forecasts are for growth of below 3%. In the first half of 2018, global investment was increasing at an annualised pace of nearly 5%, and trade over 4%. This year, the annualised growth rate of investment could slide to below 1%, with trade turning negative in the second quarter. Growth prospects have plummeted in the wake of trade and investment.

An urgent response is required, failing which we run the risk of finding ourselves stuck in a long period of low growth, the brunt of which will be felt primarily by the most vulnerable.

This is because the events of the last 18 months are not just a passing trend. The proliferation of tariffs and subsidies and the increasing unpredictability of trade policies have destroyed growth in international trade, triggering a sharp slowdown in industrial output and investments. When companies do not know what tomorrow will bring, they exercise their “wait-and-see option”. Given that an investment is a long-term commitment, they are waiting for this insidious trade war to settle down in order to know where to invest. However, when temporary uncertainty is recurrent and rooted, large amounts of investments are withheld, thereby affecting not just present day demand but also tomorrow’s growth potential and employment.

The investment gap created by this situation will have a long-term and structural impact on growth, all the more so as it will take time to clarify the new trade policy environment. This is clearly exemplified in the digital sector, given how the fastest investor always has a strong edge. But it is also the case for infrastructures, which are essential for business development. And at present, in addition to the digital sector, there is a global and structural need for infrastructure investment of nearly 7 trillion dollars per year, taking into account the energy transition in addition to traditional investment requirements. Paradoxically, the investment gap is growing at a time when governments can obtain long-term financing at very low, even negative, rates.

There is a therefore a danger of growth being bogged down for a long time. It is dangerous to use the good performance of the service sector as compared to the decline in industry as a justification for policy inaction given that the two are inextricably linked. It is equally risky to draw a distinction between countries with a large industrial sector and countries that are more service-based and therefore supposedly less at risk, given that integrated supply chains exist at both the regional and global level, and between services and industries.

The top priority is to remedy the drop in demand caused by the collapse in trade, which is affecting capital investments in particular. This can be achieved using a three-pronged economic policy, with a clear low rate policy, an infrastructure investment policy, and reforms to promote innovation. Monetary policy will struggle to halt the current downward spiral on its own, but it is detrimental to say that it has reached the limits of its capacity. Monetary policy may not be able to do everything, especially after years of providing support, but it still has a lot to offer. By providing long-term protection to the financing costs of both business and States, monetary policy creates the conditions required for private and public investment.

The euro area, for example, would already be in a much better position if it had turned to its budgetary tools, i.e. public investment, and carried out reforms to promote innovation much earlier! In our September Outlook, we demonstrate how annual public investments of around 0.5 percentage points of GDP in low-debt European countries, alongside reforms in favour of innovation in all the countries, would have allowed for a less aggressive monetary policy and encouraged short-term and long-term growth, without stretching public debt and while averting half of the increase in the price of financial assets over the past five years.

The second lever is to restore the confidence of businesses in their ability to find markets. It is now evident that trade tensions are not a temporary side-show. The international framework which governed trade has been permanently impaired, and the WTO as we know it will not come back.

Public recognition that global trade is experiencing a structural shift, that trade agreements going forward will no longer be global but perhaps more regional and more targeted, and that there is a commitment between like-minded countries to push ahead, would send a clear message to businesses to resume investment.

Growth is languishing, but there is a lot that public policy can do. This includes restoring confidence in the collective ability to establish trade rules which are clearer, more transparent, and afford more protection to citizens; and taking advantage of the predictable rates provided by monetary policies to boost investment, and with it growth and the jobs of tomorrow. It can be done. It urgently needs to be done.

More info: http://www.oecd.org/economy/outlook/


Unsatisfactory global growth:  A call to policy action!

CLM with credit press conference Interim Eco Outlook Feb 2016


by Catherine L. Mann

OECD Chief Economist and Head of the Economics Department


Welcome to the OECD Economics Department’s new ECOSCOPE blog !

Our Interim Economic Outlook launched today shows a troubling picture—world growth stuck at 3% in 2016, and only 3.3% in 2017, with substantial volatility in financial markets raising new risks.  The OECD’s mantra is “better policies for better lives”  and that is central to our assessment that a stronger policy response is urgently needed to get global growth out of this low-growth equilibrium.  Monetary stimulus alone cannot reverse many of the worrying trends seen in the Interim including weak trade, low investment and an apparent slowing of trend productivity.  Given very low interest rates, now is an opportune time for collective fiscal action, focusing  on investment spending that will raise growth in the near term and underpin long-term output potential.  Greater ambition on structural reforms to provide an environment conducive to private investment goes hand-in-hand. ( On 26 February, we will launch our annual Going for Growth assessment of structural policy needs and the progress countries are making towards achieving more productive economies with better quality jobs (details to be posted on this site)).   Monetary, fiscal, and structural policy tools are synergistic and all need to be deployed at this time.

Does the call for more fiscal action by the OECD represent a change of view ?

In a well-known phrase, Keynes wrote “When my information changes, I alter my conclusions. What do you do, sir?”.   So, what is new?

First, OECD governments have more fiscal space than they did in the immediate post-crisis period. The sovereign debt crisis has faded and the most severe banking problems have been addressed. Budget deficits have fallen in many countries following budgetary consolidation and falling interest costs. The long-term interest rate is far lower than it was 3-years ago with negative interest rates on government borrowing of a few years and the ability to raise money at longer horizons at a minimal cost.

Second, the persistent downgrade of forecasts across the economics profession in recent years raises deep questions about how the economy is operating. Some key mechanisms that drive economic recoveries seem to be not working:  wage pressures are exceptionally weak even in countries where unemployment has fallen; inequality is rising; business investment is not responding to the extraordinarily low cost of capital;  currency depreciations are not leading to robust exports;  inflation pressures seem non-existent across many economies despite exceptional monetary policy action; productivity growth and diffusion innovation appear to have slowed. The thread that runs through these disconnects is weak demand, hence the need to use all policy tools to full effect.

A scenario exercise in the Interim shows the potential growth gains, and fiscal sustainability benefits of a collective action on fiscal spending.

1st year effects of a 1/2 percent of GDP public investment stimulus by all OECD countries
Change from baseline

IEO_Slide18_Fig1_E_P2CL

There are many open questions about what are the key issues facing policymakers, and how they should balance both immediate and longer-term objectives.  This blog is an opportunity to debate these topics!

We hope that windows into research by OECD economists posted on this blog will share new insights about the evidence and the ‘’better  policies” we need to ensure the ‘’better lives’’.   Please join the conversation!

Background

Achieving prudent debt targets using fiscal rules

Interim Economic Outlook

The Future of Productivity