Enhancing labour-market integration of immigrants in Canada

by David Carey, Head of Canada Desk, OECD Economics Department

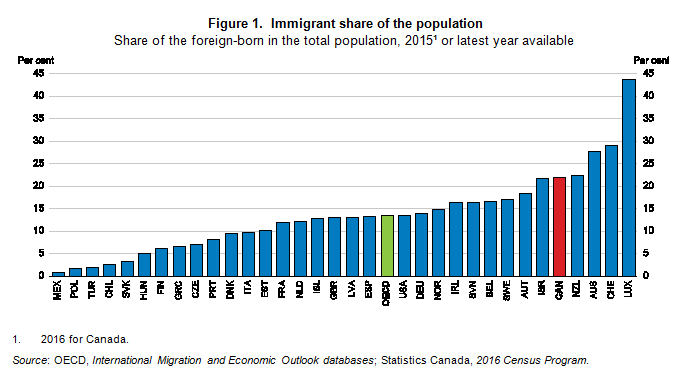
Canada has long taken in more immigrants relative to its population than most other countries. Immigration policy in Canada aims to promote economic development by selecting immigrants with high levels of human capital, to reunite families and to respond to foreign crises and offer protection to endangered people. Economic immigrants, who are selected for their skills, are by far the largest group. The immigration system has been highly successful and is well run. Outcomes are monitored and policies adjusted to ensure that the system’s objectives are met. Immigrants and their children are better integrated in Canada based on a variety of indicators than in most other countries. Immigrants selected for their skills earn substantially more than other immigrants, indicating that selection is succeeding in identifying immigrants with the greatest potential for labour market integration.
Canadaimmigrationblog 2018

A problematic development is that immigrants’ entry earnings fell sharply relative to those of the comparable native-born in recent decades. Important causes of the fall include weaker official language skills and a decline in the returns to pre-immigration labour market experience.

Canadaimmigrationblog2 2018

In response, immigration policy has been changed to select immigrants with better earnings prospects. More are selected for their human capital, and greater weight has been given to official language competence, age (inversely related to foreign work experience) and Canadian work experience. Recently, the selection system was overhauled with the introduction of Express Entry, which only invites candidates with the highest point scores to apply for permanent residence and gives employers a greater role in selection. The system would be still more effective if more weight were given to skilled Canadian work experience in selection and applications from candidates with skilled work experience and a relevant job offer were processed before others.

Canada also has an extensive array of programmes that facilitate integration. The Targeted Employment Strategy for Newcomers facilitates foreign-credentials recognition and helps immigrants gain Canadian work experience in their profession. Bridge programmes, which help with post-secondary credentials recognition in regulated occupations, and mentoring programmes, which help immigrants overcome underrepresentation in high-quality jobs by developing professional networks, have proved effective and should be expanded. The federal government’s settlement programmes are extensively used but it is not clear whether utilisation patterns reflect differences in needs or availability. There are large differences in efficiency of government language programmes, pointing to possibilities for reorganisation to improve outcomes.

References:

OECD (2018), OECD Economic Surveys: Canada 2018,  OECD Publishing, Paris.


An empirical investigation on the drivers of income redistribution across OECD countries

By Orsetta Causa, OECD Economics department

Income inequality has increased in most OECD countries over the past two decades. This has come about both because incomes before taxes and transfers have become more unequally distributed, and because the extent of redistribution through taxes and transfers has fallen (“Income redistribution through taxes and transfers across OECD countries”). A new OECD paper by Orsetta Causa, Anna Vindicis and Oguzhan Akgun provides an empirical investigation on the drivers of the widespread decline in income redistribution across OECD countries over the last two decades.

The results suggest that the size of the redistribution system plays a major role for income redistribution, in particular on the spending side, confirming previous OECD findings. Hence, the relatively widespread decline on cash transfers to the working-age population is found to have contributed to the decline in income redistribution to the working-age population.

On the revenue side, the empirical analysis uncovers an interaction between increased economic integration and the capacity of personal income taxes to reduce income inequality. Indeed, the results suggest that stronger trade ties across countries have made a given level of tax receipt through personal income taxes less effective at reducing income inequality. The estimated marginal effect of the personal income tax to GDP (PIT-to-GDP) ratio on redistribution thus depends on the degree of countries’ openness (Figure 1): for around half of OECD countries, the effect of the PIT-to-GDP ratio on redistribution is significantly positive but this effect declines with openness levels. For a country at the OECD average level of trade openness, a one percentage point increase in the PIT-to-GDP ratio is associated with a 2% increase in redistribution. For the countries for which such effect is statistically significant, it ranges from 3.7% (USA) to around 1.5% (Korea).

sizeofpitblogcausa1

For a given overall size of the tax and transfer system, the estimation results suggest that changes in specific tax and transfer instruments have contributed to the decline in redistribution. Most important among these are:

  • Reductions in the progressivity of personal income taxes, driven by a flattening of the tax schedule in the upper-part of the wage distribution as well as by a decline in top personal income tax rates and in the taxation of dividend income at the personal level.
  • Reductions in the generosity and duration of unemployment-related transfers, including cuts to social assistance for the long-term unemployed, which have often taken place in combination with increases in spending on active labour market policies. This finding is thus likely to reflect the effect of policy reforms to boost work incentives among target groups and to shift from passive to active support for the unemployed.

At the same time, not all policy changes went in the direction of reducing redistribution: the decline in redistribution has been partly mitigated by progressive family-friendly policies, such as widespread increases in spending on early education and childcare, as well as by tax cuts to low wage earners.

These estimates are used to simulate the income redistribution effect of selected tax and transfer reform scenarios, taking into account the countries’ relative starting point in each policy area. Transfer reform scenarios deliver larger effects than tax reform scenarios. The scenarios consistently point to major redistribution gains in countries where social spending on working-age population is relatively low and/ or weakly targeted to low-income households (Figure 2). Increases in long-term unemployed- related transfers to married couples deliver major redistribution gains where these transfers are low or non-existent  (e.g. Chile, Greece, Italy, Turkey and the United States)  The magnitude of these effects reflects the large implied size of the simulated reforms for these countries and should therefore be interpreted in light of alternative policy objectives, in particular efficiency objectives in terms of job search incentives, alongside budgetary constraints.  Still, those same countries that exhibit comparatively low passive support for the long-term unemployed tend to also exhibit comparatively low active support. As a result, policy packages that would combine more generous cash transfers with more effective activation and training for jobseekers would likely meet equity and efficiency objectives. The United States and Turkey would also boost redistribution by increasing spending on early education and childcare; and so would Mexico and Japan. This would not only increase redistribution but also help narrowing gender gaps and curbing child poverty. Reforms to enhance access to quality childcare for disadvantaged families are likely to maximise policy synergies between efficiency and equity.

sizeofpitblogcausa2

References: 

Causa, O., A. Vindics and O. Akgun (2018), “An empirical investigation on the drivers of income redistribution across OECD countries“, OECD Economics Department Working Papers, No. 1488, OECD Publishing, Paris, https://doi.org/10.1787/5cb47f33-en.


The Czech economy is thriving but labour shortages will limit growth

by Falilou Fall, Head of Czech Desk, OECD Economics Department

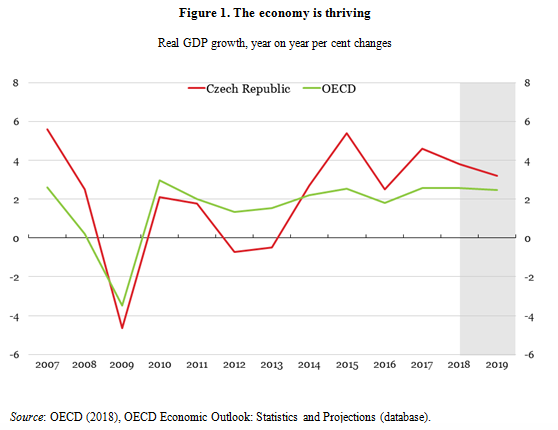
Growth, driven by both internal and external demand, has been accelerating since 2013 and at 4.6% in 2017 it was more balanced than in previous years. Household consumption is supported by income growth, a declining savings rate as confidence is high, and by rising credit. Going forward, private investment is projected to increase thanks to favourable credit conditions, and greater withdrawal of European Structural and Investment Funds. Moreover, the relative higher cost of labour than capital should stimulate physical capital investment.  Also, high housing demand and prices will continue to drive housing investment. However, growth will slow down in 2018 mainly due to labour supply constraints, but at 3.8%, growth will remain above its potential.

czech rep launch 2018 fig 1 blog

Inflation picked up strongly in 2017 reaching on average 2.5% after three years of being around 0.5%. Inflation will remain above the 2% target of the Central Bank, driven by high wage growth, strong household consumption and increasing oil prices. The current account has been positive in the last four years contributing to foreign reserve accumulation. However, after the exit from the exchange rate floor policy in April 2017, reserves (as a percent of GDP) started to decrease and the koruna to appreciate. As wages and inflation are rising, monetary policy should raise interest rates further at a gradual pace.

The fiscal position is strong but will be challenged by an ageing population. The primary balance increased to 2.3% in 2017 and has been in surplus for three years in a row. Therefore, debt-to-GDP is decreasing rapidly and at 35% of GDP in 2017 is one of the lowest in the OECD (Maastricht definition). According to new measures announced by the newly elected government, there is a risk of fiscal policy becoming pro-cyclical. In view of signs of overheating economy, fiscal policy should avoid being pro-cyclical. Some fiscal space is also needed to prepare for the rise in future ageing-related spending.

czech rep launch 2018 fig 2 blog

The lack of workers is becoming the main bottleneck to higher growth. The unemployment rate fell further in 2017 and at below 2.4% is among the lowest in the OECD. Until recently, labour shortages driven by demographic changes and high employment were partly offset by higher economic activity rates. However, the economy is facing constraints on the labour market and vacancies registered at employment offices increased more than seven-fold, from 30 803 in end 2010 to almost 267 000 in April 2018. Increasing labour productivity would sustain wage growth and help to cope with labour shortages. Providing workers with the right skills and training, as well as strengthening the effectiveness of R&D and innovation policies will be crucial to generate sustainable productivity gains and achieve inclusive growth.

References:

OECD (2018), OECD Economic Surveys: CZECH REPUBLIC 2018, OECD Publishing, Paris.


Improving the quality of business investment in Turkey

by Rauf Gonenc, Head of the Turkey Desk, OECD Economics Department

Turkey’s business sector exhibits one of the highest investment rates among OECD countries. However, the 2018 Economic Survey of Turkey (OECD, 2018) suggests that the quality of investment could be enhanced by overcoming the fragmentation of the business sector and by improving the current business environment. A comprehensive micro dataset allowed to distinguish four types of firms whose investment dynamics and challenges differ: i) small businesses with a high degree of informality, ii) medium-sized family firms, iii) large listed corporations, and iv) skilled young start-ups. There is room for increasing the share of knowledge-based and long-term investments – notably innovation, training, digitalisation and R&D investments – in all these types of firms at lower and internationally competitive investment costs.

The small informal businesses – which employ the largest share of Turkey’s labour force – have very  limited access to bank credits and no access to external equity capital as of today. Their ability to fund long-term knowledge-based assets is highly restricted. Medium-sized family firms which have played a central role in Turkey’s strong growth over the past decade are better endowed, and keener, to invest in long-term assets, but are over-leveraged vis-à-vis domestic banks, which restricts their additional investment capacity. Domestic bank loans are also typically of short maturity and entail roll-over risks for the financing of long-term investments. Even so, the majority of family firms refrain from reaching out to securities markets and to external shareholders. Large, listed firms have, in contrast, a good access to national and international debt and equity securities markets, but Turkey’s high risk premia increase their cost of financing above international competitors’. The last group of young skilled start-ups is backed by myriad government incentives at their phase of emergence, but need more risk-sharing and long-term private capital to continue to expand.

Turkeyinvestment2018

Cultivating Turkey’s equity eco-system would help these different types of firms to develop their long-term, knowledge-based, productivity-enhancing investments. Some obstacles include limited financial transparency of firms, incompatibilities between local and international governance standards, complex and frequently changing tax and subsidy systems, and too restrictive labour market rules which reduce the flexibility of firms and amplify investment risks in the formal sector. The modernisation of the business environment in all these domains would accelerate the emergence of more equity-specialised financial intermediaries, accounting experts, legal and financial advisors, research analysts and market makers. The development of this eco-system is essential for improving mutual confidence between all types of enterprises and potential investors from their local, national and international environments.

The modernisation of the business environment has been ranking high on the government’s agenda for some time. Domestic and regional geo-political circumstances have so far limited progress, and even led to setbacks in some areas such as the rule of law, judiciary independence or the fight against corruption. With the tempering of political uncertainties after the June 2018 elections, a window of opportunity opens for resuming the reform process. The OECD Survey suggests that a three-fold modernisation strategy emphasising i) the formalisation of informal and semi-formal businesses, ii) the introduction of more state-of-the-art management and digital skills in all types of firms, and iii) the rebalancing of financing structures from debt to equity would help the entire business fabric to upgrade the quality of capital formation. Progress would not only contribute to the rebalancing of growth through a more productive and internationally competitive business sector, but also to social inclusion and cohesion through the creation of high-quality formal sector jobs in the entire country.

Find out more:

OECD (2016), OECD Economic Surveys: Turkey 2016, OECD Publishing, Paris.

OECD (2018), OECD Economic Surveys: Turkey 2018, OECD Publishing, Paris.


Growth remains buoyant in Turkey but fundamentals need to be strengthened

by Volker Ziemann, Turkey Desk, OECD Economics Department

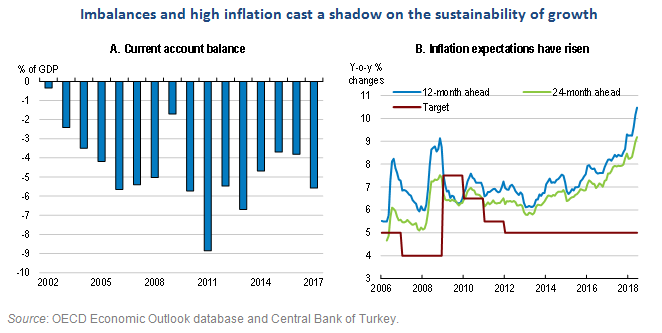
Despite numerous headwinds and adverse shocks, Turkey’s real GDP has grown by more than 34% over the past 5 years, faster than any other OECD country except for Ireland and only slightly less than China and India. The revision of national accounts in early 2017 not only pointed at higher than previously accounted growth since the global financial crisis, but also exhibited much higher shares for private consumption and investment, notably construction, in overall output underscoring long-lasting imbalances (e.g. OECD, 2016). Indeed, despite a significant rebound of exports in late 2017 and early 2018, growth still excessively relies on domestic demand amplifying the Turkish economy’s dependence on capital inflows (Panel A). Expansionary fiscal policy ahead of the June 2018 elections had further amplified these imbalances. The clear outcome of the polls should allow the government to implement fiscal restraint and realign its policies with the government’s Medium-Term Programme. It is essential to make progress with the transparency of general government accounts according to national accounting standards to preserve the hard-won credibility of public finances.

Turkey2018macro1

Inflation has been on the rise and remained in double-digit territory since early 2017 undermining confidence, international competitiveness and households’ purchasing power. Inflation expectations have continued to drift away from the 5% target (Panel B). Market participants increasingly questioned the central bank’s capacity to conduct a credible and forward-looking policy of inflation targeting amid doubts about its independence. Despite substantial increases in the central bank’s average funding rate, the mere fact of using the unorthodox late night liquidity window as a main funding tool spurred doubts about the commitment to maintain a tight stance over an extended period to re-anchor expectations and bring about disinflation. Against this backdrop, the simplification of monetary policy around a single standard interest rate in June 2018 is a welcome step towards re-establishing credibility. Going forward, a firm commitment from all stakeholders to the central bank’s independence would be supportive and help the bank to fulfil its mandate.

Alongside sound fiscal and monetary policy, the improvement of governance institutions and the reform of the banking sector were the main pillars of Turkey’s economic success over the past 15 years. While the banking sector still looks solid, a recent deterioration in the perceived quality of public governance and the stalling EU Accession process weigh on the business environment in general and the economy’s capacity to attract foreign direct investment in particular. The government’s goal to improve Turkey’s position in the Doing Business indicator is promising and should be used as an anchor to resume progress with respect to the rule of law, judiciary independence and the fight against corruption.

Find out more:

OECD (2016), OECD Economic Surveys: Turkey 2016, OECD Publishing, Paris.

OECD (2018), OECD Economic Surveys: Turkey 2018, OECD Publishing, Paris.


Fiscal decentralisation and inclusive growth?

by Sean Dougherty, Senior Advisor, OECD Fiscal Network

Fiscaldecentral2018Over the last decade or more, many countries have experienced slowing productivity growth and a rising concentration of income. Concerns about these developments have motivated a broadening of the policy discussion about how to ensure that economic growth is made more inclusive and multidimensional. One important channel for addressing these concerns is through intergovernmental fiscal relations. By providing the “right” incentives and improving rules and practices in policy making, these institutions can shape fiscal policy and multidimensional outcomes at all government levels. The OECD Fiscal Network has recently published a volume covering these topics.
Design of decentralisation, reform options and the impact on outcomes

Earlier work published in the Fiscal Federalism Studies has shown that the stage of economic development and political economy constraints play important roles in determining the success of fiscal decentralisation. Rather than rely on unique prescriptions, policymakers should consider the importance of institutional complementarities to reap the full potential of fiscal decentralisation. The volume reinforces this message, and demonstrates the importance of considering country specificities in addition to policy design principles when reforming intergovernmental institutions and transfer systems.

Several chapters therein address the basic design of fiscal federalism and associated reforms. One overarching finding is that balanced decentralisation – that is, when the various policy functions are decentralised to a similar extent – is conducive to growth. Similarly, the efficiency of public service delivery in education and health is found to be conditional on sufficient political and institutional capacity. Balanced decentralisation allows sub-national governments to better co-ordinate policy and to reap economies of scale and scope across functions. Moreover, a country’s scope for achieving growth that is also inclusive varies widely depending on its characteristics and its public finance mix.

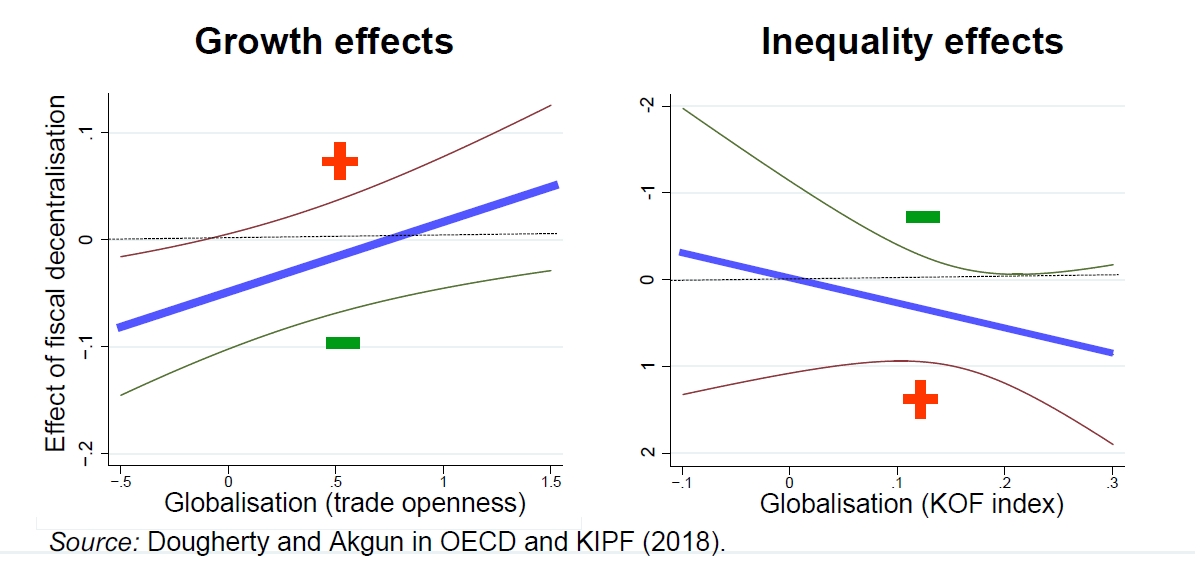
Spending and revenue decentralisation tends to boost economic growth for economies that have a relatively higher degree of globalisation, based on the analysis in this book. Fiscal decentralisation has a more ambiguous effect on inequality than on growth, especially for economies with a higher degree of openness. Moreover, for some countries, there is an apparent trade-off between growth and equity, when it comes to the “optimal” degree of spending and revenue decentralisation.

fiscdecjuly2018

A potential trade-off between efficiency and inequality is also examined in an analysis of education financing decisions, which looks at the link between local education funding and inequality. However, a range of country-specific policies tend to offset potential trade-offs.

“Design is in the details”

Given the complexity of cross-country results, the chapters include detailed examinations of various aspects of intergovernmental relations in Korea, the Netherlands, India and the United Kingdom. These analyses broadly mirror the cross-country findings, yet they also qualify them in terms of the difficulties in achieving various objectives. For instance, the analysis of Korea’s education financing system finds that it could benefit from more decentralised financing, both in terms of overall outcomes and equity. Empirically, heightened inequality tends to induce more spending on educational opportunitites for lower income populations. This analysis also finds that lower-scoring populations benefit the most from enhanced public educational investment.

Modelling of the Netherlands’ tax system shows that the design of local revenue collection, such as on immovable property, can have substantial distributional effects. Policy scenarios in which the tax burden is shifted towards immovable property show that the tax shift can yield a moderately positive impact on employment, minimising the distributional effects.

Empirical estimates of India’s transfer system suggests that special transfers do not achieve the objective of providing a more comparable level of public services across states at different income levels. While special purpose transfers are intended to ensure a minimum standard, the analysis finds that there are too many specific purpose transfers, and these are poorly targeted. A reform of the fiscal transfer system is suggested.

In a simulation of the UK’s local finances, not only the mix of funding sources matters for incentives, but the rules around tax and fee policy matter. Even if revenues are initially fully equalised relative to assessed spending needs, significant fiscal disparities can re-emerge in just a few years. Examining the trade-offs between equalisation and incentives inherent in sub-national finance reveals the importance of design choices.

The volume includes both cross-country studies and insights into reforms from individual countries, with several chapters written by experts closely involved in both institutional reform and the day-to-day operation of fiscal relations. The studies show how much the design of policy and institutions matters, even if reforms often happen slowly. The book is a sequel to Institutions of Intergovernmental Fiscal Relations: Challenges Ahead (OECD and KIPF, 2015), broadening and deepening the issues covered there. It also provides insights and experiences from academics and practitioners on key aspects of intergovernmental fiscal relations and how they contribute to inclusive growth. Discussions were fostered by the annual meetings of the OECD Network on Fiscal Relations Across Levels of Government.

References:

OECD and KIPF (2018), Fiscal Decentralisation and Inclusive Growth, OECD Publishing, Paris.


To shorten or to lengthen debt maturity to lower debt servicing costs?

By Alessandro Maravalle and Lukasz Rawdanowicz, OECD Economics Department

Low interest rates prevailing in many advanced economies in recent years have already helped to lower the debt servicing burden, but government debt and interest payments remain large in many OECD countries. Could a further reduction in interest payments be attained by “locking-in” current low interest rates?

The answer is not straightforward as it depends on the future evolution of yield curves and budget balances, which are difficult to predict, and initial conditions related to the level and maturity structure of public debt.

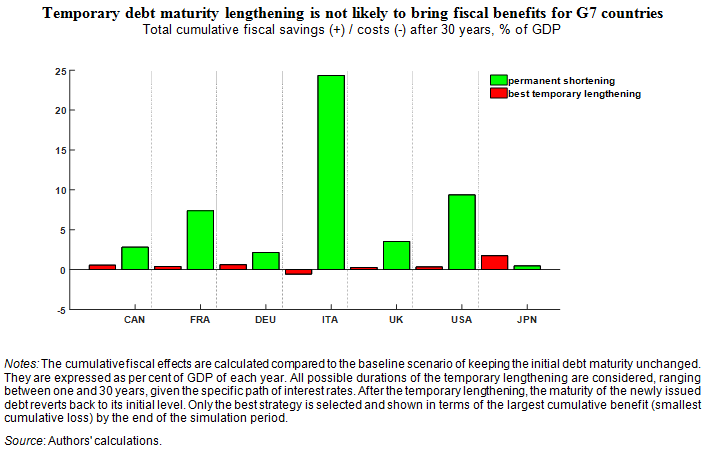
To shed some light on potential debt servicing effects of changing debt maturity, we undertook country‑specific stylised simulations over the next 30 years with different assumptions about the maturity of new debt (Maravalle and Rawdanowicz, 2018). We analyse in principle two alternative debt strategies: temporary lengthening of the debt maturity of newly issued debt, i.e. up to a few years only, and permanent shortening, i.e. for 30 years. In both cases, the average debt maturity of newly issued debt changes by one year compared with the initial country-specific average remaining debt maturity.

The simulations are calibrated to reflect several key characteristics of G7 economies, in particular the current debt maturity structure and fiscal positions. We assume that interest rates will increase and the yield curve will steepen gradually during the first five years and then stabilise afterwards. Such a stylised assumption reflects the expected normalisation of monetary policy.

It turns out that, with the assumed increase in interest rates, a temporary lengthening of the debt maturity would not bring any reduction in debt servicing costs (figure below). The assumed initial increases in interest rates and in the slope of the yield curve are not gradual enough to reap the benefit of locking-in low interest rates. As debt matures gradually over time, the yield curve must remain low and flat for a prolonged period to reduce the overall debt servicing costs in the long term when interest rates will be higher. However, even with a more gradual and protracted interest rate normalisation, such potential fiscal benefits would be still negligible. Nevertheless, lengthening of debt maturity could be motivated by reducing rollover risks or accommodating demand from investors.

In contrast, shortening debt maturity could have non-negligible fiscal benefits for most G7 countries (figure below), but this would come at the cost of higher rollover risks. Gains could be particularly large for countries with high debt and relatively steep yield curves.

debt maturity lukazjuly2018

Whatever the change in debt maturity and the scenario for the evolution of the yield curve, fiscal gains would materialise only after the first decade, not helping much to lower current budget deficits.

Reference

Maravalle, A. and L. Rawdanowicz (2018), “To shorten or to lengthen? Public debt management in the low‑interest rate environment”, OECD Economics Department Working Papers, No. 1483, OECD Publishing, Paris,


Korea needs a paradigm shift to sustain its convergence to the highest-income countries

By Randall S. Jones, Korea Desk, OECD Economics Department

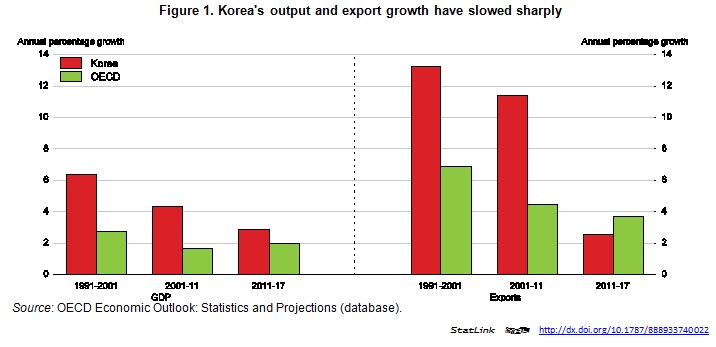
Korea’s transformation from one of the poorest countries in the world in the 1950s to a major industrial power and member of the OECD was exceptionally rapid, reflecting good policies, notably sound fiscal and monetary policy, high levels of investment in human and physical capital and an outward orientation that increased its share of world trade. Per capita income increased from 14% of the OECD average in 1970 to 86% in 2016. However, the traditional growth model seems to be losing effectiveness, as income growth has slowed toward the OECD average. Although economic growth typically slows as countries approach the high-income economies, the sharp deceleration from an annual rate of 6.4% over 1991-2001 to 2.9% since 2011 (Figure 1), raises concerns. Moreover, export volume growth slowed from a double-digit annual pace over 1991-2011 to 2.6% since 2011, lagging behind global trade.

Korea xport July2018

Korea’s real per capita income was one-third below the top half of OECD countries in 2016 (Figure 2). The large income gap reflects low labour productivity, which is 46% below the top half in the OECD. Low labour productivity is offset by very long working hours, at the expense of well-being and female employment. The decline in the working-age population beginning in 2017 year will put downward pressure on labour inputs and per capita income growth. Removing obstacles to the employment of women and youth, whose employment rates are below the OECD average is essential to mitigate the impact of demographic factors. In addition, there is large scope to raise Korea’s labour productivity, given its large investments in education and R&D, which is the second highest in the OECD area as a share of GDP. To take full advantage of its investment in innovation, Korea needs to shift from its traditional growth model to a more balanced approach that promotes inclusive growth through reforms to raise productivity in both the large business groups and SMEs.

Koreafig2July2018

References:

OECD (2018), OECD Economic Survey of Korea, OECD Publishing, Paris.


Lithuania: A fast-growing economy needs to boost inclusiveness

Lithuania2018surveyby Hansjörg Blöchliger and Vassiliki Koutsogeorgopoulou, Lithuania Desk, OECD Economics Department

Lithuania is one of the fastest growing economies in the OECD. After a strong rebound in 2017, growth is set to average more than 3% over this year and the next led by buoyant investment. Falling unemployment and rapidly increasing wages support consumption, although a shrinking labour force weighs on growth. Export growth remains solid, although below last year’s peak. Following 10 years of deficits and rising debt, the budget moved to a small surplus in 2016 and has remained positive since then. Lithuania is considered one of the most open and business-friendly economies in the OECD, and financial markets are stable.

Important challenges remain. Productivity is still about 30 percent below the OECD average, even if some recent pick up is encouraging. Export performance has improved but exports are concentrated in low-medium value-added activities and integration into global value chains is weak. Skills often do not match needs by businesses and collaboration between firms and research institutions is weak. Most disquieting, emigration – mostly of the young – continues, depriving the country of its most dynamic people and contributing to skills shortages.

Lithuania fig 2

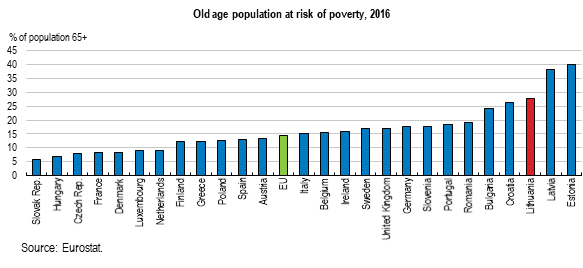
Inequality and poverty are high reflecting widespread labour informality and a pension system that leaves many elderly with low incomes.


Lithuania fig 3

The “New Social Model” is Lithuania’s most impressive achievement of the past few years to enhance productivity and inclusiveness. The reform made the labour market more flexible, protects better the unemployed, and ensures sustainability of the pension system. The New Social Model is “inclusive” in the best sense of the word. The reform is also a showcase on how to achieve a large reform with a difficult political process, by creating a win-win situation.

Lithuania should continue its reform vigour to boost productivity and inclusiveness further. Reforms should focus on improving the business environment and making firms more dynamic, including through a more efficient insolvency regime, and by making the education system more responsive to labour market needs. More and better-quality jobs in the formal sector are key to well-being and reducing poverty. More effective support for those in need and active labour market programmes would also help combat poverty. Finally, easing the rules for highly skilled immigrants could help address the negative consequences of emigration, as could strengthening social and economic ties with the Lithuanian diaspora. These issues and policies to address them are analysed in the 2018 Economic Survey of Lithuania.

Further reading

OECD (2018), OECD Economic Surveys: Lithuania 2018, OECD Publishing, Paris.


Brexit and Dutch Exports: Fewer glasshouses, more glass towers as agri-food shrinks and finance gains.

by Donal Smith, OECD Trade Directorate and Economics Department

netherlands economic survey 2018The Netherlands is likely to be one of the European countries that is going to be significantly affected by the United Kingdom’s planned departure from the European Union (Brexit). As an open economy with strong trade and investment links to the United Kingdom, the Netherlands is exposed to increases in barriers to trade between the United Kingdom and EU (Vandenbussche et al., 2017). New OECD simulations show the potential extent of this impact, as well as the different sectors of the Dutch economy likely to be affected.
The sector-level impacts will depend on differing UK trade exposures, tariff rates and non-tariff measures (NTMs) applied to different products; varying degrees of global value chain integration of the sectors; and differences in sectors trade diversification opportunities. On trade exposure for example, the agri-food sector has a comparatively high UK exposure. This sector accounts for 23% of the total exports of the Netherlands to the UK while the UK market makes up 12% of total Dutch agri-food exports (OECD 2018).[1]

An illustrative worst-case Brexit scenario – assuming the UK leaves the EU without any trade agreement – is simulated using the OECD METRO model (OECD, 2015).[2] The key advantage of this analysis is that it accounts for changes in both tariff and non-tariff barriers. The scenario assumes that trade relations between the EU and UK default to the World Trade Organisation’s (WTO) Most-Favoured Nation (MFN) rules, that is, the most basic trade relationship. Relative to current arrangements, this corresponds to an increase in tariffs on Dutch trade with the United Kingdom of between 0 and 12  per cent.


mourublog1nether2018

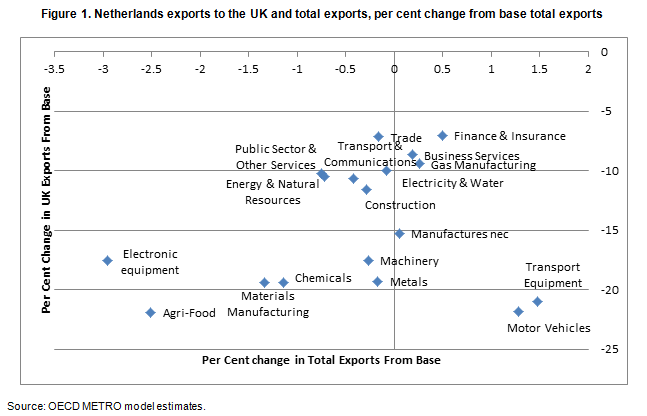
Simulation results show that Dutch exports to the UK would fall by 17%in the medium-term. The Dutch agri-food sector is estimated to experience a 22% fall in its UK exports (Figure 1). This is driven by a substantial 35% decline in exports in the meat products sector. Smaller materials manufacturing sectors such as wood and leather products and textiles would see a 20% fall in their UK exports. The 2% fall in production in agri-food contributes to a 7% decline in the value of agricultural land. Four of the five sectors that record the largest declines in employment following production falls are in the agri-food sectors.

Of all the non-agri-food sectors, electronic equipment would see the largest decline in total exports at 3% and the largest decline in production at 2.4% in the scenario. Access to supply chains for intermediate imports from the UK for Dutch sectors is also curtailed; intermediate imports from the UK would fall by over 40% in the finance and insurance sector in the scenario.

There are a few sectors which have export gains under this scenario. These include motor vehicles, finance and insurance and transport equipment, these sectors show increases in exports to the rest of the EU as well as the United States. The gas sector expands slightly, but this translates into relatively larger gains of gross exports of 6% (to EU) and 10% (to US).

[1] OECD METRO model data.

[2] This shock implies a scenario could be the result of a disorderly conclusion to negotiations and can be considered something close to a worst case outcome and does not consider the impact via investment.

References

OECD (2018), OECD Economic Surveys: Netherlands 2018, OECD Publishing, Paris.

OECD (2015), “METRO v1 Model Documentation”, TAD/TC/WP(2014)24/FINAL.

Vandenbussche, Hylke and Connell Garcia, William and Simons, Wouter, Global Value Chains, Trade Shocks and Jobs: An Application to Brexit (September 2017). Available at SSRN: https://ssrn.com/abstract=3052259 or http://dx.doi.org/10.2139/ssrn.3052259