The need for speed: Putting the World Economy on the Fast Track out of the COVID-19 crisis

by Laurence Boone, OECD Chief Economist

This is no ordinary economic crisis. When you walk down the street of a big city like Paris, its hard not to miss the usually lively restaurants, bars and museums. Travel and activity restrictions – completely unfamiliar to most of us just one year ago, have now become a part of our daily lives. In early March 2020, the OECD warned that COVID-19 could have devasting effects on the world economy. One year later, amid high uncertainty, a global recovery is in sight.

We have upgraded our growth projections

The good news is that the world economy is doing better than what we expected only three months ago. Countries are learning to better address the health situation, some are rolling out vaccines and are gradually lifting restrictions to mobility. People and firms have also adapted: producing, trading and consuming differently in this new world of restrictions.

Undeniably, policy support helps. The exceptional fiscal and monetary support that countries have deployed to protect firms and people is working – supporting jobs, incomes and firms. In addition, the massive foreseen US stimulus (USD 1.9 trillion in addition to USD 900 billion in December 2020) will boost the US economy in 2021 and add a full percent to world output in our projection as discussed in our recent post on the American rescue plan.

As a result, we project global growth of 5.6% in 2021 (Table 1), up from 4.2% in our December projections. Most countries are bouncing back, but activity levels remain far behind where we expected them to be in our November 2019 projections before the pandemic. Moreover, divergence in economic performance across and within countries is set to increase.


The best economic policy to exit this global pandemic is rapid vaccination, worldwide

Differences in health management and vaccine rollout, and consequently restrictions, as well as sectoral specialisation in hard-hit sectors such as tourism and policy support are driving the increase in divergence. Several emerging market economies, as well as European ones, are lagging behind in the recovery (Figure 1).

To speed up the rollout of vaccines, policymakers need to get on a wartime footing with vaccine production and distribution. Production is currently being scaled up thanks to voluntary licensing, but more can be done. Governments should encourage the maximum use of existing manufacturing vaccine facilities and distribution networks, while fast-tracking consents for new facilities where necessary. This means using government purchasing leverage to foster private sector licensing, transfer of technology deals and a cooperative effort across firms that would normally be competitors. Regarding the distribution of vaccines, this means governments requiring and funding vaccination centres to operate seven days per week and long hours.

To be effective, vaccine rollout needs to be not only fast, but also global. This is the only way to win the race against virus mutations and to fully reopen sectors such as travel and tourism, which accounts for over 20% of GDP in some countries. As long as the virus is raging somewhere, the risk of new virus variants is high, which will mean that we will need to keep some borders shut, restraining activity. A coordinated and multilateral approach to licensing and technology transfers, as well as purchasing, notably through increasing funding to COVAX, is the most efficient way of scaling up production and distribution worldwide, and especially in emerging markets.

Fiscal support has been key in preserving the economic and social fabric

Widespread vaccination will also make fiscal and monetary support more effective. The countries that are able to combine fast vaccination with supportive macroeconomic policies are the ones expected to benefit from faster recoveries (Figure 2). As our economies re-open, many entertainment hotel and restaurant workers can hope to get back to work. But, prospects are not the same for everyone. Following the Global Financial Crisis, young people struggled to find employment and policy was too slow to react – it took a decade for the employment prospects of graduates to “normalise” (Figure 3). To avoid such a negative outcome and the scarring effects of unemployment this time around, fiscal policy needs to be better targeted at supporting young people, for example by introducing wage subsidies to help firms expand apprenticeship and in-firm training programmes. It also needs to make use of the opportuntity to pave the way forward for a better future – fixing the massive digital divide exposed by the pandemic and directing investment to support environmental sustainability.

With the arrival of vaccines, the world economy will eventually fully re-open for business. But how the recovery is going to shape up is in the hands of policymakers: swift vaccination, targeted fiscal support and ramping up investment in new and green technologies can make a difference. Many challenges lie ahead but this crisis has taught us the importance of resilience: our ability to both avoid and respond to shocks. And, without multilateral co-operation the global recovery in growth and the jobs that go with it are at risk. There is no time to waste!  

Reference:

OECD (2021), OECD Economic Outlook, Interim Report March 2021, OECD Publishing, Paris, https://doi.org/10.1787/34bfd999-en.


Technology, Labour Market Institutions and Early Retirement: Evidence From Finland

by Naomitsu Yashiro*, Tomi KyyräƗ, Hyunjeong Hwang* and Juha Tuomalaǂ

@ Shutterstock/ SpeedKingz

Across OECD countries, promoting longer working lives is an important policy agenda for mitigating fiscal pressures from increasing pension and healthcare expenditures. There are, however, two significant barriers to increasing employment of older workers, especially in the context of digitalisation. First, workers engaged in codifiable, routine tasks are prone to being displaced by computers and robots (Gentile et al., 2020), a trend that may have been accelerated by the COVID-19 pandemic (Baldwin, 2020; Chernoff and Warman, 2021). Older workers are particularly exposed to this risk because, with shorter remaining working lives, they have weaker incentives to acquire new skills that would allow them to switch to tasks that are less likely to be automated. They may instead choose to retire early when facing rapid technological change (Ahituv and Zeira, 2011; Hægeland et al., 2007). Second, a number of OECD countries have in place institutions that encourage early retirement, such as exceptional entitlements for older workers or looser criteria for unemployment and disability benefits than for other workers. These two factors reinforce each other in pushing older workers out of employment: older workers who are more exposed to new technologies are more likely to exit the labour market when they have access to institutional pathways to early retirement; and older workers who have access to early retirement pathways are more likely to use them when they are more exposed to technological change. 

Our paper explores such complementarity for Finland, a country renowned for its intensive use of digital technologies but also with a considerably lower employment rate for older individuals than in other Nordic countries (OECD, 2020). The latter is driven importantly by early retirement through the so-called unemployment tunnel, which is the combination of the entitlement to unemployment benefit of up to 500 working days and the extension of unemployment benefit until the retirement age reserved for the unemployed aged 61 or over who have exhausted their regular unemployment benefit entitlements. From an empirical analysis exploiting a rich Finnish employee-employer database and the OECD data capturing exposure to digital technologies, we find that: 

  • An individual aged 50 or above in occupations exposed to a standard deviation higher than the average risk of automation (computed by Nedelkoska and Quintini, 2018) faces a 1.1 percentage point higher probability of exiting employment every year, if he or she does not have access to the unemployment tunnel. 
  • This probability is 2.2 percentage points higher if the individual has access to the tunnel. 
  • Gaining access to the unemployment tunnel increases the exit probability of an individual exposed to an average level of automation risks by 1.8 percentage points. 
  • The overall impact of higher automation risks and the unemployment tunnel therefore amounts to 4 percentage points, which implies an 80% increase in the probability of exiting employment for individuals aged 57-58. 

We obtain similar results when using other indicators to capture the exposure to digital technologies, such as intensity in routine tasks (Marcolin et al., 2016) or ICT skills (Grundke et al., 2017). Using the estimated coefficients, we simulate the impact of reforms that tighten access to the unemployment tunnel. Figure 1 illustrates that such reforms extend substantially the working lives of older workers exposed to high automation risks, but have little effect on individuals exposed to low automation risks.

This paper underscores the importance of labour market reforms that tighten access to institutionalised early retirement pathways in ensuring the inclusion of older workers in the future of work. While previous policy discussion often emphasised boosting lifelong learning opportunities, older workers will only have weak incentives to take up such opportunities if these early retirement pathways are left open. The recent decision by the Finnish government to abolish extended unemployment benefit by 2025 for persons born in 1965 or after is likely to encourage older workers relatively exposed to technological change to work longer and participate in upskilling opportunities. This, however, calls for targeted measures to increase the employability of groups most affected by this reform, namely low- and middle-skilled male workers in occupations exposed to high automation risks, involving more routine tasks and less use of ICT skills. Highly tailored training programmes as well as effective schemes for identifying the training needs of these older workers and certifying their acquired skills are important for boosting their upskilling efforts (OECD, 2020; 2019). Policy makers should also step up measures for getting older workers displaced by new technologies back into employment. In the case of Finland, such measures may include strengthening the capacity of the employment service to provide these workers with more personalised counselling and better monitoring of their activation requirements (OECD, 2020), as well as enhancing the role of social partners in facilitating job transitions even before dismissals take place, as in Sweden (OECD, 2016). 

*OECD Economics Department / ƗVATT Institute for Economic Research and IZA Institute of Labour Economics / ǂVATT Institute for Economic Research

Further reading

Naomitsu Yashiro, Tomi Kyyrä, Hyunjeong Hwang, Juha Tuomala (2021) “Technology, labour market institutions, and early retirement” VoxEU.org, 12 March 2021.

Yashiro N., Kyyrä, T., Hwang, H. and J. Tuamola (2021), “Technology, labour market institutions and early retirement: evidence from Finland”, OECD Economics Department Working Papers 1659.

OECD (2020), OECD Economic Surveys: Finland 2020, OECD Publishing, Paris.

OECD (2019), Working Better with Age, Ageing and Employment Policies, OECD Publishing, Paris.

Reference

Ahituv, A. and J. Zeira (2011), “Technical progress and early retirement”, Economic Journal, 121, 171–193.

Baldwin, R. (2020) “Covid, hysteresis, and the future of work” VoxEU.org, 29 May

Chernoff, A. and C. Warman (2021) “Down and out: Pandemic-induced automation and labour market disparities of COVID-19” VoxEU.org, 2 February. 

Gentile, E., S. Miroudot, G. De Vries and K. M. Wacker (2020) “Robots replace routine tasks performed by workers” VoxEU.org, 8 October.

Grundke, R. et al. (2017), “Skills and global value chains: a characterisation”, OECD Science, Technology and Industry Working Papers, 2017/05.

Hægeland,T., D. Rønningen and K. Salvanes (2007), “Adapt or withdraw? Evidence on technological changes and early retirement using matched worker-firm data”, NHH Dept. of Economics Discussion Papers, No. 22/07.   

Marcolin, L., S. Miroudot and M. Squicciarini (2016), “The routine content of occupations: new cross-country measures based on PIAAC”, OECD Science, Technology and Industry Working Papers, 2016/02.

Nedelkoska, L. and G. Quintini (2018), “Automation, skills use and training”, OECD Social, Employment and Migration Working Papers, No. 202.

OECD (2020), OECD Economic Surveys: Finland 2020, OECD Publishing, Paris.

OECD (2019), Working Better with Age, Ageing and Employment Policies, OECD Publishing, Paris.

OECD (2016), Back to Work: Finland: Improving the Re-employment Prospects of Displaced Workers, OECD Publishing, Paris.


Canada: Ensuring sustainable economic recovery

by Philip Hemmings, OECD Economics Department

Canada’s economic support averted an even larger downturn in 2020. The latest OECD Economic Survey of Canada underscores that the economic policy response to the crisis has been rapid, entailing one of the biggest support packages of OECD countries. Even with this support, the economic activity fell by over 12% between Q4 2019 Q2 2020.

Economic recovery is in sight. Although the latest round of containment measures has slowed the rebound in activity, the easing of restrictions as vaccination progresses will see the recovery gather momentum. Following a shrinkage in output of 5.4% in 2020, the Survey sees growth of 4.7% for 2021 and 4% in 2022.

Substantial risks and uncertainties surround the economic outlook:

  • Many households accumulated sizable savings during lockdowns. How fast consumer confidence, and therefore spending, will rebound is uncertain—implying risks to the projection.
  • On the upside, the boost from US stimulus could be larger than expected.
  • On the downside, high household and corporate debt contributes to macro-financial vulnerabilities.

The economy still needs macroeconomic support while the economy is fragile:

  • Monetary policy should continue to be geared towards supporting the recovery.
  • The targeted fiscal support to people and businesses should evolve as the recovery progresses to ensure assistance focuses support policies for workers in hard-hit sectors and youth and viable companies.

Fiscal policy needs to look ahead. After the pandemic subsides, it will be necessary to stabilise public debt and find ways to accommodate additional spending commitments. Canada’s significant policy support also means the public debt has increased substantially. Furthermore, the ageing-related spending pressures present before the pandemic will continue. There is need for a clear and transparent roadmap in fiscal policy that ensures the public debt burden does not spiral out of control.

Structural reform is also needed to reach a stronger and greener growth in the post-covid era. Businesses need conditions that will help them adapt to the future:

  • Stronger incentives for business to become greener are also needed to help drive decline in greenhouse gas emissions—Canada has a long way to go to achieve its goals. The report supports the recent federal government proposals for substantial carbon-price increases, announced as part of a strengthened climate plan. It also suggests Canada could expand its use of environmental taxes more generally, which are low relative to other countries’.
  • The economy would benefit from lower barriers to inter-provincial trade and better high-speed Internet infrastructure.
  • Evidence points to a need to re-examine insolvency procedures to ensure that viable companies running into difficulty have an opportunity to recover.

The crisis has exacerbated socio-economic inequalities. Job losses have been greatest in low-wage sectors that employ substantial numbers of young people and women. The crisis has also highlighted disadvantages among ethnic minorities and Indigenous groups, who tend to fare poorly in terms of income, life expectancy, housing and health, even in normal times. It has also exposed shortcomings in areas like long-term care for the elderly, health policy and the provision of affordable housing. The recovery should be used to address these vulnerabilities. These issues are covered in the Survey’s in-depth chapter on well-being.

Reference:

OECD (2021), OECD Economic Surveys: Canada 2021, OECD Publishing, Paris, OECD Economic Surveys: Canada 2021 – OECD.Kappa https://doi.org/10.1787/16e4abc0-en


The Covid-19 Crisis and the Automotive Industry in Central and Eastern Europe: Risks and Opportunities

By Caroline Klein, OECD Economics Department

In many Central and Eastern European (CEE) countries, including the Czech Republic, Hungary, Poland, Slovenia, Slovakia and Romania, the automotive sector plays an important role in economic growth and employment. The industry has been hit hard by the Covid-19 pandemic (Figure 1). Lockdown measures in spring 2020 forced factories to close down or to operate at a fraction of their normal capacity. Demand for motor vehicles plunged and is likely to be subdued for longer, reflecting income losses and heightened uncertainty. 

A recent OECD paper discusses the industry’s outlook in the CEE region and shows it will mainly hinge on foreign demand and the ability to seize new opportunities as the industry adapts and transforms.

The economic outlook is highly uncertain, but, after a sharp recovery in the third quarter of 2020, activity in the industry will likely remain subdued in the short to medium run. The Covid-19 crisis is expected to have a long-lasting impact on economic growth in CEE countries’ main trading partners (OECD, 2020). In 2021, demand for cars manufactured in Europe is projected to remain below its pre-crisis level, based on OECD Economic Outlook projections and an estimated relationship between car sales and GDP growth. 

The impact of the COVID-19 crisis on car demand will vary by market segment. Consumers tend to buy smaller cars during economic downturns, which can benefit countries specialised in mass-market segments. At the same time, while sales of fossil-fuel powered cars have plunged, demand for electric cars has remained high. This shift might not benefit car producers in CEE countries, as alternative cars still account for a low share of total production in the region.

There have been concerns that the pandemic could cause supply chains disruptions with large negative impact on the automotive industry because of its high degree of integration into global value chains. Until now, supply disruptions have played a more limited role in crisis transmission mechanisms than the shock to demand. At the same time, bankruptcy risks among sub-contractors, especially the smaller ones, have increased and shortages of semi-conductors have affected car production. 

In the longer term, the crisis could leave lasting scars in the industry, by stalling investment and upgrading to knowledge-intensive activities. This is worrisome, as investment is needed to adapt to structural transformations, especially the shift to alternative powertrains and digitalisation. Besides, it is unclear if the pandemic might trigger a shortening of the supply chains, offering CEE countries opportunities to tighten the links between multinational car producers and domestic suppliers. 

Policies to improve the investment climate and strengthen resilience of viable firms can help the recovery. Addressing labour shortages and adapting skills to fast-changing manufacturers’ needs will be key to maintain competitiveness of the CEE region in the automotive industry.

Further reading

Klein C., J. Høj, and G. Machlica, (2021), “The impacts of the COVID-19 crisis on the automotive sector in Central and Eastern European Countries” OECD Economics Department Working Papers, No.1658, OECD Publishing, Paris.


Preparándose para tiempos mejores: las prioridades de Chile para una recuperación inclusiva

By Paula Garda and Nicolas Ruiz, Economics Department 

Durante los últimos 20 años, Chile ha logrado un tremendo progreso hacia una mayor prosperidad económica, más que duplicando su ingreso per cápita y sacando a muchos chilenos de la pobreza. Esos logros se estancaron durante 2020, ya que Chile se ha enfrentado a dos choques sin precedentes: las protestas sociales de finales de 2019 y el brote de COVID-19. Esos choques han sumido a Chile en una recesión de una magnitud no vista desde la crisis monetaria de 1982. Las políticas de reacción a la pandemia han sido rápidas y audaces para amortiguar un impacto sin precedentes para los hogares y las empresas. Sin embargo, a medida que Chile se encamina hacia una recuperación gradual de la pandemia, existe una necesidad imperiosa de transformaciones económicas y sociales más profundas para lograr una recuperación compartida por todos, colocando a Chile en una senda de crecimiento más inclusivo y sostenible. 

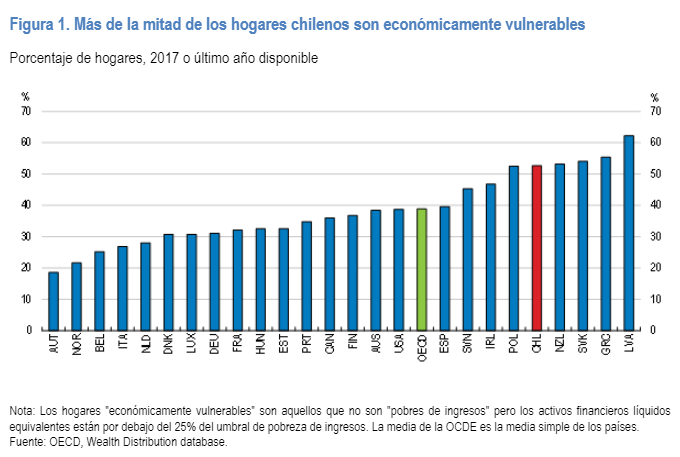
Chile debe llenar sus dos faltantes del medio: una clase media decaída y la falta de empresas medianas dinámicas. Más de la mitad de los hogares chilenos son económicamente vulnerables. Esos son hogares que no son pobres, pero están en riesgo de pobreza, debido a los bajos ingresos y la falta de riqueza mínima suficiente para hacer frente a un impacto negativo sobre los ingresos (Figura 1). Es posible que muchos de estos vulnerable hayan caído en la pobreza durante 2020. Al mismo tiempo, Chile exhibe una división persistente entre una pequeña cantidad de empresas grandes y productivas y una larga cola de empresas pequeñas y medianas con un desempeño de productividad considerablemente menor (Figura 2). Esta polarización de la productividad tiende a sostener una clase media vulnerable: la escasez de empleos de mayor productividad y de salarios más altos genera empleos informales y precarios, asociados con una baja protección social, ingresos bajos e inestables, amplificando el riesgo de volver a caer en la pobreza en recesión o en caso de crisis sanitaria. 

Este estudio identifica las prioridades para una recuperación exitosa y construir una clase media fuerte y próspera en Chile. Las medidas y áreas de reforma incluyen: 

  • Intensificar la eficiencia del sistema tributario y de transferencias: el sistema tributario y de transferencias apenas reduce las desigualdades. La base del impuesto sobre los ingresos de las personas físicas es demasiado estrecha y ampliarla después de que la recuperación esté en marcha generaría ingresos que pueden destinarse a la creación de un impuesto negativo a los ingresos, lo que aseguraría a cada hogar e individuo una protección básica. 
  • Promover el acceso a una educación de calidad para todos: El acceso a una buena educación sigue fuertemente vinculado al estatus socioeconómico de la familia. Se debe intensificar el gasto en educación y dar prioridad a la educación de alta calidad de primera infancia, primaria y secundaria, como requisito base para elevar los niveles de competencias y ampliar la educación terciaria. Si bien los efectos de estas políticas se sentirán solo a largo plazo, constituye una palanca fundamental para combatir ahora las consecuencias que COVID-19 podría grabar en la inclusión y la desigualdad de oportunidades. 
  • Aumentar la relevancia y calidad del sistema de capacitación: El acceso de los trabajadores vulnerables a la capacitación es insuficiente y muchos de sus perfiles laborales pueden cambiar en el futuro o desaparecer con el riesgo de automatización. Los programas de formación deberían revisarse para aumentar la calidad y la pertinencia y dirigirse a aquellos que más lo necesitan, asegurando que todos los trabajadores, en particular los más vulnerables, tengan oportunidades adecuadas para capacitarse y encontrar trabajos de buena calidad.  
  • Generalizar los procedimientos de concesión de licencias cero (“zero licensing”): el entorno regulatorio inhibe la competencia y la expansión de las empresas. La generalización del “zero licensing” que involucre a los municipios en el diseño, podría facilitar la entrada y formalización de empresas, lo que podría contribuir a reducir las desigualdades a lo largo del tiempo al crear empleos mejor remunerados. 
  • Impulsar la transformación digital: La crisis puso de relieve disparidades en las habilidades digitales y el acceso y uso de estas tecnologías entre estudiantes, trabajadores y empresas chilenas. Uno de los mayores desafíos es el acceso a Internet de banda anche de alta velocidad, en particular en las zonas rurales. Barreras de entrada más bajas en el sector de las comunicaciones podrían acelerar el despliegue de redes tanto fijas como móviles y mejorar el acceso a servicios de banda de alta velocidad a precios competitivos. Intensificar las competencias digitales y la adopción de herramientas digitales por parte de las empresas, principalmente las PYMES, ayudaría a los trabajadores y las empresas en la transición para una recuperación más rápida e incluyente. Se necesita una mejor integración de las habilidades digitales en la escuela y mejorar la formación de los profesores que son los propulsores de cambio. Programas públicos específicos para las PYMEs de adopción de herramientas digitales y mecanismos de financiamiento, diseñados en estrecha colaboración con el sector privado, les permitirían emprender el camino digital. 

Más información: 

http://oe.cd/chile-sp 

OECD (2020), OECD Economic Surveys: Chile 2020, OECD Publishing, Paris, https://doi.org/10.1787/79b39420-en. 


Public Health and Federalism amidst the Coronavirus Pandemic

by Sean Dougherty (@econecho) & Pietrangelo De Biase, OECD Fiscal Network

The rapid global spread of the Coronavirus caught authorities by surprise one year ago. In a matter of weeks, a virus outbreak that initially seemed to affect only China and a few neighbouring countries spread to virtually all countries around the World. Time was short to digest the impact of the outbreak, while little was known about the mortality rate of the virus, nor about the effectiveness of various containment measures and treatments.

Public health is often managed by multiple levels of government, which poses special coordination challenges for quickly designing and imple­menting a harmonised response. The OECD’s Fiscal Network and Joint Health Network have shown that subnational governments (SNGs) are often responsible for managing health inputs and budgeting, while central governments define policy and carry out oversight (James et al., 2020). Many decisions related to healthcare are shared across levels of government. Consequently, intergovernmental coordination is crucial.

A wide range of coordination mechanisms have been deployed, yet there still exists substantial uncertainty regarding what does and doesn’t work. Alternative mechanisms have widely varying advantages as well as implementation challenges, and no single approach can be considered superior to all others. Notably, there are successful cases of both centralised and decentralised responses, although centralised responses were twice as frequent as decentralised ones in a survey of policy responses to the first wave of the pandemic (Dougherty et al., 2020).  

More decentralised responses give more autonomy to regional and/or local governments to change the substance, process and timing of the measures recommended by the central government. For instance, in the United States, northeastern states imposed relatively strict lockdowns, while states such as Texas, Florida and more rural states were more hesitant to enforce strict lockdowns affecting their jurisdictions. In contrast, France’s more centralised policies, such as the enforcement of lockdowns and prohibition of public gatherings, entered into force at the same time throughout the entire country.

Both a centralised and a decentralised approach can be appropriate (de Biase and Dougherty, 2021). Centralisation can be justified by the fact that responses to the outbreak have substantial spillovers and the crisis requires a national effort to implement a country-wide response. On the other hand, since there is uneven impact across regions, and containment measures are immensely costly for the economy and well-being more broadly, subnational autonomy can be important for each region to select the policies that target the preferences and needs of its local citizens.

It is worth highlighting that there is evidence that a prompt timing of policy actions can significantly affect the contagion curve and fatality rates through the adoption of less invasive measures, including lessening the fiscal impact at the subnational government level. The early use of test-and-trace accompanied by comprehensive contact tracing with effective isolation of those infected – combined with the support of other public health policies, such as mandating mask-wearing in public environments, limiting visits to care homes and stay-at-home recommendations for the most vulnerable – have helped reduce the spread of the virus in a number of jurisdictions without resorting to strict lockdowns (Égert et al., 2020).

Institutional mechanisms

The necessary involvement of actors from different levels of government with their own interests poses challenges for intergovernmental coordination. Authorities may call into question the existing balance of power and narrative regarding the measures that they are supposed to take together, potentially leading to political deadlocks. In order to avoid such political deadlocks and foster cooperation, different institutional mechanisms were put to use.

Countries have been re-orienting or creating new institutions to improve intergovernmental coordination (especially centres of government). These bodies have been holding regular meetings (primarily virtually), involving representatives from multiple levels of government and policy areas, as well as scientists and public health experts. While some countries (e.g. Chile, France) created new institutions with the sole purpose of handling emergencies, others adapted existing structures to tackle this specific crisis (e.g. Belgium, Italy).

In the executive federalism approach, mayors, state governors and the prime minister/president (executive branches of multiple levels of government) establish frequent meetings, formal and/or informal, to define and monitor responses. It requires agreement among authorities since, there is no legal mechanism that mandates the implementation of certain measures. Australia offers an example of the use of such mechanism. In light of significant subnational autonomy, a re-oriented centre of government (known as the National Cabinet) was used to create consensus and coordinate responses.

State-of-emergency laws typically centralise decision-making power in the hands of the executive branch of the central government. Although they can be effective to avoid political deadlocks, the absence of a multi-level governance structure may jeopardise local capabilities to implement central government decisions. A myriad of countries declared state-of-emergencies, leading to a temporary increase in centralised power to tackle the crisis. Notable examples are Germany, Italy, Spain and Switzerland.

Especially in countries that have been implementing a decentralised response, the emergence of new horizontal coordination arrangements among regions has been common (OECD, 2020). The main drivers for this emergence are the existence of strong links among the authorities prior to the crisis, bipartisanship and territorial policy diffusion.

Lessons for the future

Waves of infections are a common pattern seen in virus pandemics, which occur partly due to changes in human behaviour and government responses over the course of an outbreak. Thus, subsequent COVID-19 waves are likely to have a different dynamic than the first. Early evidence from Israel suggests that the introduction of vaccines can lead to a drastic reduction in contamination. Nevertheless, the process of introducing vaccines is complex and will probably advance gradually, while the virus is mutating, creating new strains that might be more resistant to existing antibodies.

Another area of uncertainty lies in the interaction between COVID-19 and the democratic process. First, many countries have taken extraordinary invasive measures that may be questioned democratically in the future. The Swiss population, for instance, will vote in June on a referendum to limit the government’s ability to unilaterally impose lockdown measures. There have also been protests over responses to confront the outbreak in many western countries, such as Germany and the Netherlands. Second, the impact of the virus and the measures already taken may aggravate structural inequalities regarding access to education, healthcare and social protection.

In summary, there is vast uncertainty with regards to the future of the crisis, its political impacts and the effectiveness of country policy responses. We need to incorporate lessons from the first waves and remain hyper-vigilant. The crisis is far from over, and cooperation across levels of government will remain crucial.

References:

De Biase, P. and S. Dougherty (2021), “Federalism and Public Health Decentralisation in the Time of COVID-19”, OECD Working Papers on Fiscal Federalism, No. 33, January, http://oe.cd/il/pubhealth-ff

Dougherty, S., Vammalle, C., De Biase, P., & Forman, K. (2020), “COVID-19 and fiscal relations across levels of government”, OECD Tackling Coronavirus (COVID-19), July, http://oe.cd/il/COVID-FF.

Égert, B., Y. Guillemette, F. Murtin and D. Turner (2020), “Walking the tightrope: avoiding a lockdown while containing the virus”, OECD Economics Department Working Papers, No. 1633, December, https://doi.org/10.1787/9cc22d8c-en

James, C., I. Beazley, C. Penn, L. Phillips and S. Dougherty (2019), “Decentralisation in the health sector and responsibilities across levels of government: Impact on spending decisions and the budget”, OECD Journal on Budgeting, OECD Publishing, Vol. 19(3), https://doi.org/10.1787/c2c2058c-en

OECD (2020), “The territorial impact of COVID-19: Managing the crisis across levels of government”, OECD Tackling Coronavirus, November, http://oe.cd/il/TerrCov.


Reducing regional gaps in Bulgaria would support a more inclusive recovery

© Shutterstock.com/RossHelen

By Mikkel Hermansen, Bulgaria desk, OECD Economics Department

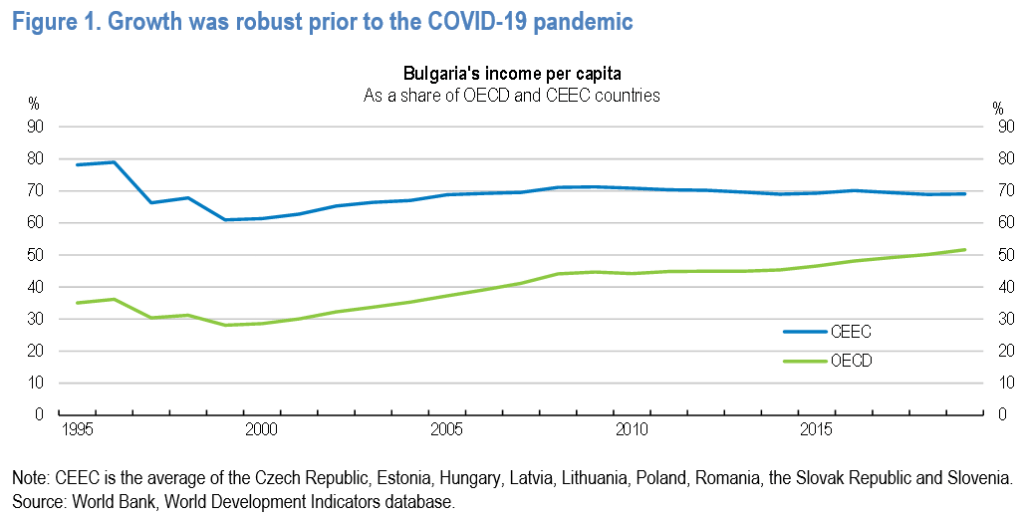
Bulgaria had several years of robust economic growth prior to the COVID-19 pandemic. Income per capita reached half of the OECD average (Figure 1), but did not catch up on faster-growing Central and Eastern European peers. The structural reform agenda has been substantial in recent years. Even so, the 2021 Economic Assessment of Bulgaria (OECD, 2021) calls for continued efforts to modernise the economy and enhance inclusion. This is all the more important as vaccinations accelerate and a recovery looms ahead.

A key challenge for Bulgaria is a fast-shrinking and ageing population (Figure 2). This has increased regional income differences that are now larger than in most OECD countries. Regions without larger cities are lagging behind and are facing multiple challenges from depopulation, high unemployment and widespread poverty. Increasing investments in infrastructure and housing reform would help to boost mobility and strengthen regional linkages to national and international supply chains. Many rural regions are strongly dependent on agriculture, while tourism plays a big role in coastal regions by the Black Sea. Bulgaria has taken several measures to cushion workers, notably in tourism, from the pandemic shock. This is welcome and should be followed by policies to facilitate sustainable local economic development in the longer term. For instance, from upgrading tourism and agricultural activities and products.

Improving living standards across all regions will require better coverage and access to public services. Health and long-term care needs to be strengthened in particular. Hospital capacity is high and helped to mitigate the ongoing pandemic crisis. Nonetheless, access to health care is restricted in many regions due to low numbers of general practitioners, and gaps in health insurance coverage remain significant. To address the pandemic, the government made treatment of COVID-19 available to all. Going forward, priorities should be given to increase effectiveness of public healthcare spending by gradually consolidating the hospital sector and reducing out-of-pocket payments for low-income groups.

References

OECD (2021), OECD Economic Surveys: Bulgaria 2021: Economic Assessment, OECD Publishing, Paris, https://doi.org/10.1787/1fe2940d-en.


The role of online platforms in weathering the COVID-19 shock

By Mauro Pisu, Hélia Costa, Hyunjeong Hwang, OECD Economics Department

While the COVID-19 pandemic has forced many businesses, big and small, around the world to shut down and fire or furlough workers, others thrived. Online platforms that allow people and firms to buy and sell product and services through the internet and without physical contact boomed. A prime example is Amazon, whose revenues in the second quarter of 2020 increased by around 40% on a yearly basis while GDP plummeted worldwide. Likewise, transaction volumes and revenues of digital payment processing companies, such as Paypal and Square, jumped to new highs and their market capitalisation surpassed that of most retail and investment banks.

Understanding the shift of economic activities to online marketplace during the COVID-19 is important as there is no close parallel in recent history to draw insights from. On the one hand, online platforms might have helped to mitigate the negative economic impacts of COVID-19 by allowing firms and people to keep producing and working during lockdowns, thus strengthening resilience to shocks disrupting traditional economic activities. On the other hand, the shift towards online platforms may have helped to strengthen and consolidate their market share, heightening concerns about unfair competition, data privacy and non-standard forms of work. The shift could also outlast the COVID-19 shock as people and businesses build new habits.

A new OECD Policy Brief sheds light on the use of online platforms during the first half of 2020 using a new comprehensive dataset of about 1 400 online platforms active in OECD and G20 countries in nine activity areas. The analysis shows that, during lockdowns, businesses and people increasingly turned to online platforms to pursue economic activities. This was especially the case in activity areas requiring little or no physical proximity for product and service delivery (such as mobile payments, marketplace to consumers, professional services and restaurant delivery) (Figure 1). In these areas, online platform use, as proxied by Google Trends data, increased by about 20% in the first half of 2020. However, in activity areas requiring physical proximity (such as accommodation, restaurant booking and transport), platform activity declined markedly (by around 90% in the first half of 2020), reflecting the generalised economic disruption caused by the COVID-19 pandemic.

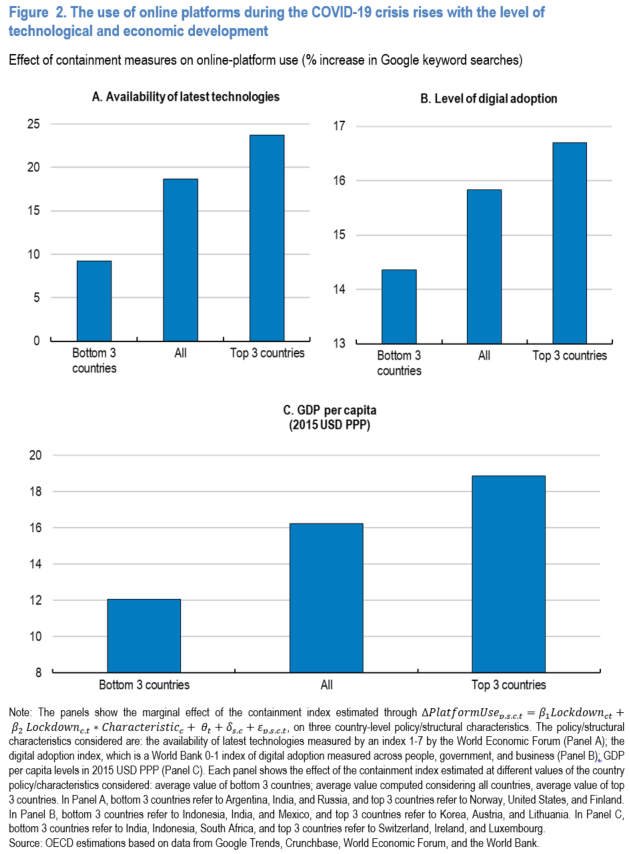
The analysis also reveals that the increase in online-platform use varied across countries depending on pre-existing structural conditions and policies. The increase tended to be larger in more developed and technologically-advanced countries, those with easier access to infrastructure and connectivity, higher skill levels, and more widespread use of the Internet (Figure 2). These results highlight the varying degree of countries’ digital preparedness. When COVID-19 hit, some countries were better prepared than others and in these countries people and businesses may have found it easier to shift activities towards online platforms.

The COVID-19 shock has added urgency to policies aiming at accelerating the digitalisation of public and private sector activities. During the crisis many OECD and G20 countries implemented a range of such policies including, for instance, improving broadband connectivity, helping firms adopt online business models, promoting online payments, and enhancing digital skills (G20, 2020; OECD, 2020a; OECD, 2020b).

This new urgency is welcome but a coordinated approach is needed to exploit synergies across policy areas. For instance, to make the investment in digital infrastructure effective, complementary investment in skills is necessary. Moreover, policies to protect the privacy of personal data and strengthen cybersecurity can enhance trust in digital technologies and online platforms, accelerating their adoption. Designing or updating Industry 4.0 plans in view of the new challenges the COVID-19 has created would be a good way to build such a coordinated approach.

For more details see:

OECD (2020), “The role of online platforms in weathering the COVID-19 shock”, OECD Policy Responses to Coronavirus (COVID-19), OECD Publishing, Paris, https://doi.org/10.1787/2a3b8434-en.

References:

OECD (2020), Policy Options to Support Digitalisation of Business Models during COVID-19, Annex, http://www.oecd.org/sti/policy-options-to-support-digitalization-of-business-models-during-covid-19-annex.pdf

OECD (2020a), Keeping the Internet up and running in times of crisis, http://www.oecd.org/coronavirus/policy-responses/keeping-the-internet-up-and-running-in-times-of-crisis-4017c4c9/ (accessed on 9 October 2020).

OECD (2020b), The potential of online learning for adults: Early lessons from the COVID-19 crisis, http://www.oecd.org/coronavirus/policy-responses/the-potential-of-online-learning-for-adults-early-lessons-from-the-covid-19-crisis-ee040002/ (accessed on 9 October 2020).


Upgrading Turkey’s macroeconomic policy institutions to boost the recovery after the COVID-19 shock

by Dennis Dlugosch and Rauf Gönenç

Past OECD Economic Surveys of Turkey had underscored that Turkey’s transition towards more transparent and rule-based macroeconomic  – fiscal, monetary and macrofinancial – and structural – product, labour and capital market- policy frameworks would better mobilise the potential of the economy and Turkish people and deliver stronger and more sustainable growth.

In the aftermatch of the COVID-19 shock, the 2021 Survey emphasises that the need to strengthen policy institutions and frameworks remains central to facilitate the recovery from the pandemic and to support the transition to a less volatile economy.

To support the economy during the pandemic, the government has some fiscal space to take necessary measures, at least in the short-term. However, so far, policymakers have relied almost entirely on quasi-fiscal channels like public bank lending and government credit guarantees (see Figure 1). This helped to minimise the immediate fiscal bill of the pandemic, but at the cost of transparency of the subsidy and its targeting to the businesses and households most in need. Further costs for public finances may also come in the form of contingent liabilities of a yet undetermined magnitude. The 2021 OECD Economic Survey recommends that future support related to the pandemic should be provided in a more transparent and coherent fiscal policy framework. Such a coherent policy framework should encompass fiscal, quasi-fiscal but also monetary and financial policies. The publication of a regular Fiscal Policy Report would contribute significantly to increase the transparency of all public financial liabilities.

The pandemic has amplified Turkey’s longstanding monetary policy challenges. Inflation had remained well above target for many years before the pandemic. The OECD Survey recommends to restore a strong institutional basis for monetary policy by restoring the independence of the Central Bank, including with the help of legislative measures reinforcing the inamovibility and extending the tenure of its management.  Establishing an active communication system on various aspects of its foreign reserve position would address information needs of domestic and international investors for a more detailed net reserves gauages.

Despite significant progress in the prudential regulation of Turkish banks following good international practices since the 2000s, the economic implications of the COVID-19 shock are adding to pressures on credit quality, already weakened by the turning of the credit cycle in recent years. One concern relates to the large weight of banking and credit channels in financial intermediation, with a resulting significant increase in debt leverage in the business sector. Further, the role of government-owned financial institutions and capital allocation regulations considerably expanded. Related risks in the overall operation of the financial system increased with the Covid-19 shock, as government support was mainly provided through credit instruments further increasing firms’ and households’ indebtedness. Public banks gained a large weight in credit markets, and prudential leniency mesures delayed the reporting of bad loans and adjustments in bank balance sheets. The OECD Survey recommends to reinforce the institutional basis of macrofinancial policies, with policymakers communicating actively on how they evaluate and address the risks of deterioration in banks’ asset quality, publishing the results of the stress tests of individual banks and of the banking system as a whole, and involving the Turkish Competition Authority to ensure a level playing field between public and private banks, as well as between public and private borrowers in access to finance.

Strengthening Turkey’s macroeconomic policy institutions would increase policy credibility, reduce risk-premia, encourage long-term capital inflows and help to boost the recovery. As a result, improved domestic and international confidence, lower risk premia and thus lower long-term interest rates would provide a more favourable foundation for strong and sustainable growth. Building on the remarkably entrepreneurial and young population and a very dynamic business sector, a strong macroeconomic foundation would allow well-designed structural policies to lift employment rates of women and men, job quality, household incomes and well being. A priority should be to address informal and semi-informal practices, for example by reducing high employment costs and rigid employment rules but also to remove any remaining regulatory barriers to the upscaling of smaller firms. Increasing the provision and quality of early child education would allow for more inclusive employment opportunities. Improving the eco-system for equity financing, for example through incentives in the corporate tax system, would provide the business sector with additional means to grow in the aftermath of the pandemic.

Reference
OECD (2021), OECD Economic Surveys: Turkey 2021, OECD Publishing, Paris.
https://doi.org/10.1787/2cd09ab1-enCD


Financial inclusion: challenges in OECD countries

By Fozan Fareed, Patrick Lenain, Enes Sunel and Douglas Sutherland, OECD Economics Department

Access to financial services is taken for granted by most people. Amenities such as bank accounts, credit cards, cash dispensers, consumer credit and mortgage loans – all essential to our daily lives – are widely available in OECD countries. When individuals face financial hardship, having access to savings set aside in a bank, or obtaining a consumer credit, is particularly useful. Also, digital payments have proved essential during the COVID-19 pandemic to observe safe distancing rules.

However, not everybody enjoys this kind of financial access. Worldwide, about 1.7 billion people did not have access to basic formal financial services in 2017. In OECD countries, many vulnerable people have insufficient knowledge to go beyond rudimentary transactions or are unable to accumulate savings. Not having access to money management can be a serious problem. People facing emergencies, like a large healthcare bill, may not be able to come up with the funds and remain untreated for their illness. Being unable to make online payments and contactless transactions will be a growing problem in the post-pandemic world. Governments often use electronic payments to make rapid social transfers during recessions (Duenwald et al., 2020), such as the US$1,200 payment sent to all U.S. citizens during the first wave of COVID-19, but may be unable to reach some people. The literature finds that financial inclusion matters for access to employment and income generation (Bruhn and Love, 2014), entrepreneurship creation (Fareed et al., 2017) and women empowerment (Karlan et al. 2017; Pitt et al. 2006). This blogpost highlights several insights from our recent research on three countries: Costa Rica [1] (Sunel, 2020), Mexico (Fareed et al, 2017) and the United States (Azzopardi et al. 2019).

Costa Rica: almost one third of adults without financial access

Despite progress made during the past decade, more than 30% of Costa Ricans aged over 15 do not have an account with a financial institution. Insurance penetration is also very limited and stagnant. This low level of financial access is partly explained by the high cost of banking services, which act like a tax on financial transactions. The lack of competition between banks has impaired the reduction of banking costs and intermediation margins seen in other countries, and Fintech have not been allowed to operate fully to provide low-cost solutions to (especially underbanked) consumers.

To get a sense of regional disparities, we built an index summarising the prevalence, at the level of counties, of financial access points, credit operations, bank accounts and financial transactions (Figure 1). Access to financial services is typically low in counties where the population is not dense, but some highly-populated counties, such as Alajuelita and Desamparados in the province of San José and San Rafael and San Pablo in the province of Heredia, also display very low financial inclusion scores. For micro-entrepreneurs, this makes business operations very challenging, especially for women entrepreneurs. Priority groups such as Indigenous people also suffer more than others from financial exclusion. In response, the authorities have launched a National Financial Education Strategy to boost financial literacy of vulnerable populations and linked conditional cash transfer programme beneficiary accounts to debit card accounts to increase financial account ownership.

Figure 1: Financial inclusion disparities in Costa Rica

Source: Banco Central de Costa Rica; Instituto Nacional de Estadística y Censos; and Superintendencia General de Entidades Financieras.

Mexico: over half of Mexicans without a formal bank account

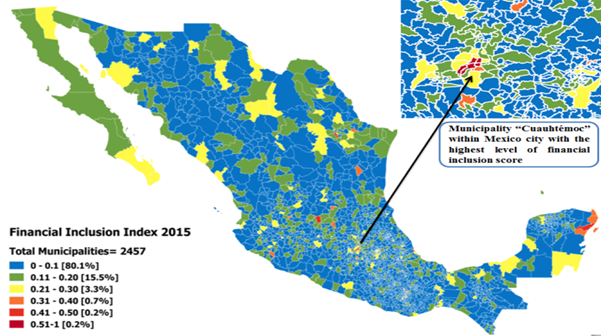
Financial inclusion is even lower in Mexico: more than half of Mexicans aged 15 and over do not have a formal bank account. The penetration of credit, insurance and mobile banking also remains low as compared to regional peers. About 7 million people (6% of the country’s population) live more than 4 miles from the nearest financial access point such as a bank or an ATM according to the financial regulator CNBV. Outside large urban areas, access to financial services is limited and there are prominent regional disparities as highlighted by our financial inclusion index (Figure 2). This is a particular problem for women, who lack access to the banking system and therefore face challenges to launch an entrepreneurship project.

Lack of trust in banks, financial literacy and product design are significant barriers for the many unbanked in Mexico. High commissions and interest rates and poor financial infrastructure are highlighted as some of the main reasons that impede financial inclusion. Addressing these challenges would enable Mexicans, especially women entrepreneurs, to gain access to formal financial services and therefore benefit from new economic opportunities. The authorities have launched a number of actions to address these challenges, for instance the National Financial Inclusion Strategy (NFIS) provides a roadmap to accelerate access to financial services for the currently unbanked segment of the population.

Figure 2: Financial inclusion disparities in Mexico

Source: Author’s Calculations based on CNBV’s data at the municipality level.
Note: Financial inclusion index ranges from 0 (low) to 1 (high). See Fareed et al. (2017) for details.

United States: 28% of Americans are financially vulnerable

Although financial inclusion is high in the United States, financial vulnerability remains a severe problem for many people, especially low-income households, racial groups, and remote locations. Instead of using an arbitrary definition of financial vulnerability or a single indicator, such as indebtedness, we apply a hierarchical ascending clustering (HAC) and K-means clustering analysis to the Federal Reserve’s Survey of Consumer Finance. The analysis identifies clusters of households with high financial vulnerability: about 28% of the households in 2016 can be classified as financially vulnerable.

Our econometric estimates show that Black and African Americans and Hispanics are financially more vulnerable than non-Hispanic white Americans, after controlling for other characteristics. A higher education level of the household head also appears to be statistically significant and is negatively linked with financial vulnerability. On average, having a college degree decreases the probability of being financially vulnerable. Financial literacy is also an area of concern: only 57% of adults in the United States can be considered financially literate according to the Global Financial Literacy Survey. Moreover, an increase in the age of the household head decreases the chances of being financially vulnerable. Such large differences among clusters of households reflect on the social disparities that affect the U.S. population.

Conclusion

Financial inclusion disparities exacerbate existing wealth inequalities and make it extremely difficult for the financially vulnerable to catch up, threatening social cohesion. Our research on Costa Rica and Mexico shows that access to financial services remains a challenge for many people, while large groups of U.S. households can be characterized as financially vulnerable. Since our research was conducted, it is possible that the COVID-19 pandemic has worsened these difficulties: many households have lost their jobs and micro-entrepreneurs have been impacted by government shutdown orders, increasing their financial difficulties. Because low-income households are being hit the hardest, it is more important than ever to facilitate access to financial instruments and encourage money management skills. Our findings suggest that the focus needs to be on closing gender and racial gaps, improving financial literacy, using Fintech responsibly to reach out to financially excluded people, and conducting further research to understand why some households are more at risk than others.


[1] Costa Rica was invited to join the OECD as its 38th member in May 2020.

REFERENCES

Azzopardi, D., F. Fareed, P. Lenain and D. Sutherland (2019), “Assessing Household Financial Vulnerability: Empirical evidence from the U.S. using machine learning”. https://dx.doi.org/10.1787/75c63aa1-en

Bruhn, M. and I. Love (2014). “The Real Impact of Improved Access to Finance: Evidence from Mexico”. Journal of Finance, 69 (3): 1347-1376.

Fareed, F., M. Gabriel, P. Lenain and Julien Reynaud (2017), “Financial Inclusion and Women Entrepreneurship : Evidence from Mexico”, OECD Economics Department Working Papers, No. 1411, OECD Publishing, Paris, https://dx.doi.org/10.1787/2fbd0f35-en.

Karlan, D., Savonitto, B., Thuysbaert, B., and Udry, C. (2017). “Impact of savings groups on the lives of the poor”. Proceedings of the National Academy of Sciences, 114(12), 3079-3084.

Mathai, K., Duenwald, C., Guscina, A., Bukhari, H., Chaudry, A., El-Said, M., Fareed, F., Gerling, K., et al. (2020), “Social Spending for Inclusive Growth in the Middle East and Central Asia” IMF Departmental Papers. No. 20/12.

Pitt, M. M., Khandker, S. R., and Cartwright, J. (2006). “Empowering women with micro finance: Evidence from Bangladesh”. Economic Development and Cultural Change, 54(4), 791-831.

Sunel, E. (2020), “Boosting access to credit and ensuring financial inclusion for all in Costa Rica”, OECD Economics Department Working Papers, No. 1623, OECD Publishing, Paris, https://doi.org/10.1787/86037778-en.