Addressing Switzerland’s housing challenges

Finding affordable housing has become more difficult in Switzerland. Recent OECD work has identified a number of policy reforms that could help ensure that housing supply grows in line with rising demand, and that existing residential areas and dwellings can be used more effectively.

by Priscilla Fialho, OECD Economics Department


Switzerland has one of the highest per-capita incomes of the OECD, but housing has increasingly become a source of concern for many Swiss households. Like elsewhere, urban centres have suffered a shortage of affordable housing. Housing has risen to the top of voters’ concerns and is starting to play an important role in the political debate. House prices have risen faster than in the OECD average in recent years, and the Swiss National Bank has estimated that prices may now be 15 to 40% above levels suggested by fundamental indicators. For an average household, saving enough to buy a property is a long exercise in patience: first-time home buyers in Switzerland are, on average, 47 years-old, compared to an average of 31 years-old in the European Union. Rents have also soared: For renters at the bottom of the income distribution, housing absorbs close to 40% of disposable income. For young people in particular, renting has become increasingly unaffordable and buying increasingly distant.

Switzerland’s housing problem is essentially a problem of supply

While housing demand has clearly increased over the years, that is only half of the story. The pertinent question is why supply has been so slow to respond. The number of apartments offered for rent has fallen since 2015, while residential construction has barely budged in the face of stronger demand. The result is predictable: rising housing costs. Without policy action, housing demand will likely continue to outpace supply, making affordable housing even harder to come by in the future.

Mountains, lakes and protected areas impose genuine physical constraints, but Switzerland has not yet used up its reserves of buildable land, nor has it exhausted its potential for denser development. Estimates suggest that unused reserves within existing building zones could supply housing for an additional 1.6 million people. In some areas, more than 20% of existing building zones are still completely undeveloped. Almost 80% of undeveloped buildable land in urban municipalities has at least average access to public transport, and 32% of the built-up area in existing building zones has potential for densification. The greatest potential for densification was found in larger cities, including Zurich and Geneva where the housing market is particularly strained.

Building in Switzerland is surprisingly complicated

The revised Spatial Planning Act of 2014 was designed to limit urban sprawl and encourage development within existing built-up areas, but its implementation has been slow. In 2024, only about 43% of municipalities had adapted their land-use plans to the new requirements. Challenges in the implementation of the revised Spatial Planning Act have created significant uncertainty, potentially discouraging new housing construction investment. Further support to cantons and municipalities in the form of technical expertise to complete an inventory of underused land, or to streamline urban design standards, could help.

Densification is hardly an easy sell anywhere. In Switzerland, where residents can challenge local projects and direct democracy is woven deeply into political life, it can be particularly complicated. Creating ample consensus for urban densification and addressing concerns will therefore be key for success, and this will require building ample opportunities for public participation into all stages of the planning process. Increasing the share of mixed-used zoning could also help to gather local support and reconcile different interests.

Switzerland’s construction costs have been persistently higher than in European neighbours. One reason is the country’s remarkable patchwork of diverse construction standards across cantons and municipalities. These complex local rules limit the scope for economies of scale and competition and may explain why the construction industry is dominated by small firms. Strengthening the harmonisation of building codes across cantons could reduce construction costs. Setting cross-cantonal standards could involve intergovernmental conferences, with inputs from private-sector experts.

Then comes the paperwork. On average, it takes 140 days to obtain a building permit. In Geneva, it takes 497 days and in Zurich, 214. Across Switzerland, permit delays have increased by 67% over the past decade. Even after the construction permit is obtained, legal appeals can still be lodged and delay the start of construction works. Around 10% of construction projects remain on hold despite having obtained a building permit. Delays can have a considerable impact on costs and profit margins. Uncertainty surrounding potential legal appeals can affect budgeting and bidding for projects, inflating construction costs. Switzerland could build on its high level of technological sophistication and make greater use of electronic permitting. California, for example, has experimented with an AI-powered system that checks building applications against zoning and construction codes. Automating routine checks allows officials to concentrate on cases that require human judgement.

Switzerland may have more unused housing reserves than meets the eye

The share of under-occupied dwelling space in Switzerland is high compared to European countries. Under-occupancy, defined by comparing the number of rooms to occupants, is particularly frequent among older households. Households above 65 have, on average, a surplus of two rooms. Making better use of the available dwelling stock would help increase housing supply and alleviate pressure on housing costs.

Rent controls are intended to make housing more affordable, but they could be generating a counter-productive side effect. Most rents are regulated once a tenancy begins. This protects sitting tenants from sharp increases, but it also creates a growing gap between the rents paid by existing tenants and those faced by households who sign new contracts. This gap can discourage people from moving, even when their current dwelling becomes larger than their needs. These lock-in effects contribute to increased floor-space consumption per capita and exacerbate the housing shortage, besides making it less attractive to build to rent. Closing the regulatory gap between ongoing and new rental contracts and harmonising rules concerning the updating of rents could be considered to reduce such distortions. For example, rents in ongoing contracts could be adjusted based on local average rents for new leases of comparable dwellings. Further clarifications on what defines an abusive rent, based on objective criteria, could also be helpful.

Tax policy can also play a role to create incentives for renting out available properties, renting out spare rooms, and building on available land. Switzerland could consider increasing recurrent taxes on immovable properties, which are low in international comparison. Such taxes create incentives for owners to use their housing space up to its maximum potential.

Switzerland has always been very good at making the most of its scarce resources. Addressing the country’s housing shortage should not be different. The current housing challenge is not so much about how to find new construction land but rather a question of making better use of existing residential areas.

Reference:

OECD (2026), OECD Economic Surveys: Switzerland 2026, OECD Publishing, Paris, https://doi.org/10.1787/48b03aff-en.


It’s not just about income. So who gets energy price relief?

Policymakers are looking beyond household income and firm size as criteria to better target energy support measures. Mobility needs, energy vulnerability, and sector-based exposure are factors that can help direct support to those most in need.

by Cassie Castle and Eugenia Brotons Batista, OECD Economics Department


Disruptions to energy supplies passing through the Strait of Hormuz have pushed up global energy prices for the past several months, placing sustained pressure on households and firms. Yet the impact is unequally distributed. Households and firms differ considerably in their exposure to higher energy costs and their ability to absorb them (Blake & Bulman, 2022).

Policymakers aim to provide financial support in a timely manner and often the quickest way to deliver relief is through broad-based measures. Broad-based measures apply to a wide share of the population; they can be implemented swiftly through existing systems and bypass the administrative burden of identifying eligibility. For example, VAT reductions on transport fuels have been a popular broad-based measure during the current energy crisis.

However, broad-based measures have some drawbacks. First, they provide support irrespective of need or exposure to shocks which can make them more fiscally costly than targeted measures. Second, while measures that reduce the cost per unit of energy can shield consumers from higher prices, they can also weaken incentives to cut consumption. And in a supply shock, maintaining price signals is desirable to help moderate demand and improve market efficiency.

OECD analyses have emphasised that government intervention to support households and firms, should be targeted towards vulnerable households and otherwise viable firms that are particularly exposed to the shock (OECD, 2026; Hemmerlé & et al., 2023). Doing so can help contain spending at a time when fiscal space is increasingly constrained. This blog provides examples of how policymakers can target support to the most burdened groups while preserving incentives to reduce energy consumption.

The OECD Energy Support Measures Tracker 2026 records policies introduced by governments to mitigate the impact of the current energy crisis on their economies in a publicly available online database. Of the 248 measures captured in the Tracker, about half are targeted, meaning that they are designed to support specific groups of households or firms rather than all consumers.

Identifying households exposed to high energy prices

Governments are using a range of criteria to better identify vulnerable households. These go beyond income alone and include factors like driving needs, energy source dependence and other exposure factors, such as age and family composition (Figure 1).

Mobility needs

Households may have different exposure to energy price shocks depending on their mobility needs. This is the most common targeting factor identified in the Tracker, accounting for about one third of targeted household measures. With benchmark diesel prices nearly doubling since February 2026, households that depend on private vehicles for commuting or work face higher costs, especially where public transport alternatives are limited.

Several countries have used existing administrative data and observable travel needs to identify these vulnerable households. France introduced a scheme allowing lower-income workers who meet commuting-distance or annual-mileage thresholds to apply for a one-off fuel payment, with income eligibility assessed using existing tax information. New Zealand targeted relief for teachers assigned to small, rural and isolated schools by temporarily increasing their mileage reimbursements to offset higher fuel costs. Denmark also temporarily increased commuting tax deductions for 2026, using travel distances to determine eligibility and providing additional relief to lower-income commuters.

Energy-source exposure

Households can also be more exposed to higher energy prices if they rely on more price-affected fuels for cooking and heating, such as natural gas, heating oil or LPG. Around one fourth of targeted household measures take this exposure into account. Portugal temporarily increased bottled-gas discounts to households eligible for the social electricity tariff, targeting a fuel widely used by low-income families for cooking and heating. The United Kingdom provides support to financially vulnerable households reliant on heating oil, many of whom live in rural areas without access to the gas grid and with few heating alternatives.[1] The Netherlands takes a broader approach through its Energy Emergency Fund, using both income and energy expenditure as a share of income to identify households facing particularly high energy costs.

Not all firms are equally exposed to the energy shock

For firms, governments have focused support on sectors most exposed to higher energy costs. Targeted measures have concentrated on freight and passenger transport operators, energy-intensive industries and firms reliant on crisis-affected intermediate or indirect inputs (Figure 2). In these sectors, fuel accounts for a large share of production cost and firms often have limited scope to reduce consumption without cutting back operations. Sharp increases in energy prices can therefore threaten the viability of otherwise competitive firms (André & et al., 2023). Support for firms should be temporary and targeted at those viable firms particularly affected by the shock to avoid distorting competition and impeding the efficient reallocation of resources (Hemmerlé & et al., 2023).

While most measures targeted at firms in the Tracker rely on sector-based eligibility, some countries use additional information to target and deliver support. Peru requires eligible passenger and freight operators to demonstrate fuel purchases through electronic receipts linked to registered vehicles. Ireland sets different compensation ceilings for fishing vessels based on characteristics such as engine power and fishing gear; they also require invoices to verify gasoil purchases. Korea goes a step further and covers 50% of price increases (relative to pre-conflict levels) for naphtha and petrochemical-feedstock imports; this measure links support directly to price exposure.

Looking ahead

Looking ahead – both for fine-tuning existing support as well as introducing future measures – effective targeting requires looking beyond income and firm size to assess exposure to energy price shocks. The Tracker provides some evidence that governments are moving in the right direction, increasingly targeting measures using criteria other than income. However, in many countries there is still scope to strengthen data systems and administrative capacity. Digitalising delivery systems, collecting timely and comprehensive data on vulnerability indicators beyond income, and scaling up social protection mechanisms can help governments identify those most affected so they can deliver timely, targeted support in future shocks (OECD, 2026).

References

André, C. et al. (2023), “Rising energy prices and productivity: short-run pain, long-term gain?”, OECD Economics Department Working Papers, No. 1755, OECD Publishing, Paris, https://doi.org/10.1787/2ce493f0-en.

Blake, H., & Bulman, T. (2022), “Surging energy prices are hitting everyone, but which households are more exposed?” OECD EcoScope, https://oecdecoscope.blog/2022/05/10/surging-energy-prices-are-hitting-everyone-but-which-households-are-more-exposed/.

Hemmerlé, Y. et al. (2023), “Aiming better: Government support for households and firms during the energy crisis”, OECD Economic Policy Papers, No. 32, OECD Publishing, Paris, https://doi.org/10.1787/839e3ae1-en.

OECD (2026), “Energy prices are spiking again: New relief measures, old lessons”, OECD Publishing, Paris, https://doi.org/10.1787/a68e5c37-en.


[1] Households off the gas-grid and prices for alternative fuels – House of Commons Library


How large is the long-term fiscal challenge in OECD countries?

OECD governments face growing long-term fiscal pressures from high debt and deficits, rising financing costs, ageing populations and the increasing cost of public services. New estimates from the OECD Long-Term Model assess the scale of the fiscal adjustment needed.

by Yvan Guillemette, OECD Economics Department


Most OECD governments face significant long-term fiscal challenges. Many have higher debt than a decade ago, sizeable budget deficits, rising financing costs and growing spending pressures from population ageing and the increasing relative cost of government-provided services. An indication of the scale of the challenge is provided by new estimates of long-run fiscal adjustment needs from the OECD Long-Term Model (LTM). These are presented in a new paper that describes the methodology used in detail and incorporates recent improvements, including the addition of defence expenditure as a source of fiscal pressure.

The fiscal adjustment needed to stabilise the debt-to-GDP ratio close to its current level over a chosen horizon is estimated using a long-run fiscal gap. This considers the current fiscal position as well as projected growth, interest rates and expenditure pressures. Such estimates are not forecasts but illustrate the pressures that could emerge in the absence of offsetting policy action.

Long-run fiscal gaps are sizeable

For the median OECD and accession country, the long-run fiscal gap is 4.7 percentage points (pp) of GDP at the 2060 horizon (Figure 1). In ten countries, it exceeds 8 pp. The gap is marginal (less than 0.5 pp) or negative in only three countries: Denmark, Iceland and Ireland. This reflects relatively strong initial fiscal positions and low or negative net public debt, as well as, in Denmark’s case, statutory retirement ages that are linked to life expectancy. The main sources of these long-run fiscal gaps are weak initial fiscal positions relative to those needed to keep debt-to-GDP ratios stable (contributing 0.9 pp of GDP in the median country), and population ageing, which raises public expenditure on both pensions (2.2 pp) as well as health and long-term care (1.8 pp). Higher defence spending adds to these pressures in many countries.

Governments have choices about how and when these pressures are met, but the pressures will become greater and more urgent the longer such choices are delayed. The appropriate policy mix will differ across countries and could include revenue measures, expenditure restraint, pension and health reforms, policies to raise employment and productivity, and, in some cases, additional debt financing. If governments do not act to address fiscal pressures, debt will rise. If higher spending on pensions, health, long-term care, defence and debt interest is met entirely through additional borrowing rather than by other budgetary offsets, net government debt could rise by 43 pp of GDP by 2045 in the median country and much more in some individual countries (Figure 2).

Growth helps, but how it is generated matters

Recent work at the OECD has highlighted the importance of favourable cyclical conditions for sustained debt reduction (Pina, Hitschfeld and Miyahara, 2025). The LTM analysis shows that stronger growth can help, but it is not necessarily a fiscal panacea and dependent on policy choices by governments. A reform-driven 10% increase in potential output by 2060 has surprisingly little effect on the median fiscal gap if it comes entirely from higher labour productivity. Higher productivity raises GDP, but it also tends to increase wages and therefore the cost of labour-intensive public services, as well as benefits if these are linked to wages rather than prices.

The picture is different if higher output comes from increased employment. Achieving the same 10% increase in potential output through higher employment reduces the median fiscal gap by around 2½ pp of GDP. Having more people in work increases the number of contributors relative to beneficiaries, generating a substantially larger fiscal dividend.

This makes policies that expand employment particularly valuable from a fiscal perspective. Higher migration can also help when it makes the population younger. A scenario in which annual net migration gradually rises by 0.1% of the baseline population reduces the median fiscal gap by about 0.6 pp of GDP by 2060. Similarly, increasing statutory retirement ages by one year reduces the gap by around 0.4 pp.

Changes in pension generosity could have much larger fiscal effects but would also involve more difficult trade-offs. Switching from wage to price indexation of pension benefits could reduce the median long-run fiscal gap by around 4½ pp of GDP. However, maintaining price indexation over a long period would progressively reduce pensions relative to wages, creating a widening disparity between the incomes of workers and retirees.

References

Guillemette, Y. (2026), “Illustrating long-run fiscal challenges using the Long-Term Model”, OECD Economics Department Working Papers, No. 1877, OECD Publishing, Paris, https://doi.org/10.1787/421bf86f-en

OECD (2025), “OECD global long-run economic scenarios: 2025 update”, OECD Economic Policy Papers, No. 36, OECD Publishing, Paris, https://doi.org/10.1787/00353678-en.

Pina, Á., M. Hitschfeld and T. Miyahara (2025), “Drivers of public debt reductions: Lessons from past episodes in OECD countries”, OECD Economics Department Working Papers, No. 1841, OECD Publishing, Paris, https://doi.org/10.1787/89a45c05-en


Should central banks tier reserves?

Monetary policy tightening after QE has led to central bank losses, largely because of higher interest payments on reserves (deposits held by commercial banks at the central bank). As a response, some central banks have tiered reserves, ceasing to remunerate part of them.

by Masatoshi Ando and Álvaro Pina, OECD Economics Department


Monetary policy tightening after QE has led to central bank losses

The balance sheet of central banks is mainly composed of securities such as government bonds on the asset side, and reserves plus currency on the liability side. Central bank profits consist primarily of interest receipts from securities held less interest payments on reserves. In recent years there have been sizeable swings in the net interest income of central banks (Figure 1), with several central banks reporting negative net interest income and financial losses. Such central bank losses have weighed on the public finances, with fewer or no dividends paid to governments and, in some jurisdictions, central banks requiring compensation or recapitalisation. These developments have raised the question as to whether central banks should move to paying interest on only a part of their reserve holdings.

A key factor behind the decline in central bank net interest income after the pandemic was the increase in policy interest rates. This raised interest payments substantially, as commercial bank reserves held at the central bank are typically remunerated at an interest rate equivalent or close to the policy rate. In contrast, there was no commensurate increase in central bank interest income, since most bonds held in 2022-23 were purchased during quantitative easing (QE) episodes when bond yields were extremely low. There has been some improvement since 2024, reflecting policy rate reductions, balance sheet reductions through quantitative tightening and, in some jurisdictions, the acquisition of higher yielding government bonds using the proceeds from maturing low-yield bonds. Nonetheless, low profitability persists and may do so for some time.

Several central banks have taken steps to lower the costs of reserve remuneration

The high costs of reserve remuneration have prompted debate about ways to reduce them, and in particular the possible use of tiered systems (De Grauwe and Ji, 2023; Tucker, 2022; Buetzer, 2022; Whelan, 2021). One option is for a certain amount of reserves to remain (or be made) mandatory and remunerated at a lower rate, possibly zero. These are typically called required reserves, though terminology may vary across countries. Central banks could then steer money market interest rates by remunerating reserves beyond the mandatory amount (termed excess reserves) at or close to the policy rate.

A number of central banks have implemented some form of tiered remuneration of reserves, often with the stated intention of reducing the costs of monetary policy implementation:

  • Iceland: The Central Bank of Iceland made a subset of required reserves unremunerated in 2018. The unremunerated reserve ratio was raised from 1% of eligible bank liabilities (e.g. certain deposits) to 2% in June 2023, and to 3% in April 2024, while the remunerated reserve ratio was lowered from 1% to 0% in March 2020 (Central Bank of Iceland, 2018, 2024).
  • Euro area: The ECB lowered the remuneration rate of required reserves in two steps, first in December 2022 from the main refinancing operations rate to the deposit facility rate, and then to zero in September 2023 (ECB, 2023).
  • Czechia: Required reserves, previously remunerated at the main policy rate (two-week repo rate), ceased to earn interest in October 2023. In addition, from January 2025 the required reserve ratio was raised from 2% to 4% (Czech National Bank, 2023, 2024).
  • Switzerland: The SNB stopped remunerating required reserves from December 2023 and increased their amount from July 2024, by increasing the respective reserve ratio from 2.5% to 4% and by expanding the range of financial institution liabilities subject to the reserve requirement (SNB, 2023, 2024).
  • Sweden: Legislative changes enacted in January 2025 allow the Riksbank to require credit institutions to hold unremunerated deposits when its equity falls below a certain target level, as is now the case. The Riksbank has been making use of this provision since end-October 2025 (Riksbank, 2024, 2025, 2026).
  • Japan: In contrast to the central banks above, some others, including the Bank of Japan, have had a longstanding policy of not remunerating required reserves. Together with tiering for excess reserves, this Bank of Japan policy benefitted commercial banks when the policy rate was negative. Since 2024, when the policy rate became positive, excess reserve tiering has been dropped (Bank of Japan, 2024) and unremunerated required reserves have instead delivered a financial gain to the Bank of Japan.

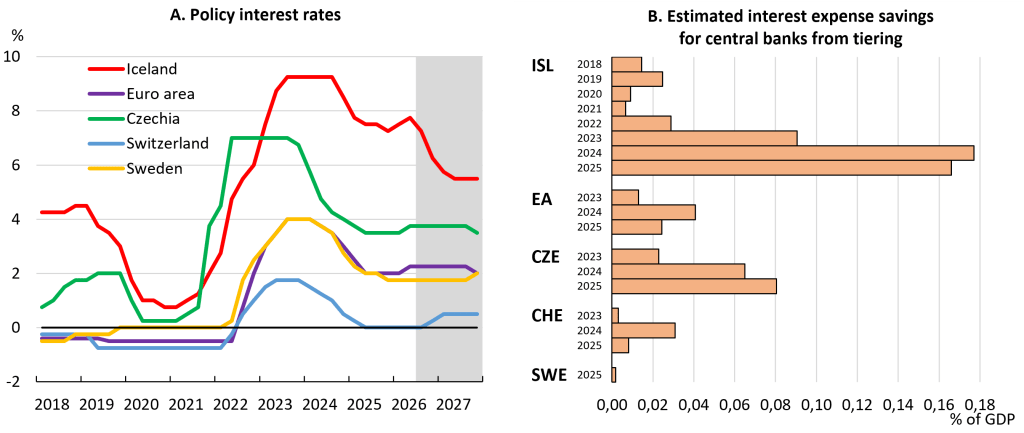
Tiering reserves reduces central bank interest payments, with the savings greater the higher the policy rate is (Figure 2). For example, estimated savings amounted to nearly 0.2% of GDP in 2024 in Iceland. In the other economies displayed, where policy rates were lower, savings were smaller. The reduction in central bank interest payments is also limited by the relatively low share of unremunerated required reserves in central bank liabilities (often under 10%).

Figure 2. Tiering reserves reduces central bank interest payments

Graph showing policy interest rates from 2018 to 2027 for Iceland, Euro area, Czechia, Switzerland, and Sweden, with trends in percentages.

Note: Interest expense savings in Panel B are estimated as the difference between interest expenses without and with tiered remuneration. In the scenario without tiering, required reserves are assumed to be remunerated at the same rates as excess reserves.
Source: Central Bank of Iceland; Czech National Bank; European Central Bank; Sveriges Riksbank; Swiss National Bank; OECD Economic Outlook 119 database; and OECD calculations.

The tiering of reserves poses complex trade-offs

Raising the share of reserves that receive zero or below-policy rate remuneration could potentially yield more substantial interest expense savings, but is not straightforward. Even if a system could be found to ensure that commercial banks would continue to hold excess reserves, potential trade-offs include the possible behavioural responses of commercial banks and their clients, and the impact on future monetary policy choices.

The non-remuneration of required reserves can be regarded as an implicit tax on commercial banks, especially if those reserves are large. (Equally, remuneration of reserves may be an implicit subsidy in some circumstances.) Non-remuneration may incentivise banks to reduce their deposit base (to lower the amount of reserves they are required to hold) and potentially affect credit creation. Deposit relocation could also be substantial (McCauley and Pinter, 2024a), though it could be pre-empted by a history-based reserve requirement rather than one based on current balance sheet quantities (Tucker, 2022). The extent of pass-through to higher lending rates or lower deposit rates would also need to be considered, and it would depend on the degree of competitive efficiency of the banking system and on the mobility and price-responsiveness of different groups of bank customers. Such factors could affect the economic incidence of the implicit tax, making it fall more on companies and households than on banks.

Non-remuneration or lower remuneration of (part of) excess reserves held at the central bank is a further option, but this could also generate changes in commercial bank behaviour. Liquidity regulations are one reason why many commercial banks may hold excess reserves at the central bank (Duffie, 2026). Such incentives will remain, but tiering of the rates paid on such reserves might lead commercial banks to reallocate their assets from central bank reserves to other liquid assets (such as Treasury bills).

Large-scale tiered reserve remuneration might also affect decisions and incentives about the future use of QE, as the downside of central bank losses and their ensuing fiscal impacts when policy rates rise would be minimised. However, commercial banks might also become more reluctant to sell bonds to central banks (and concomitantly increase their reserves), which could make it more difficult for central banks to implement QE smoothly (McCauley and Pinter, 2024b).

References

Bank of Japan (2024), Changes in the Monetary Policy Framework, https://www.boj.or.jp/en/mopo/mpmdeci/mpr_2024/k240319a.pdf.

Buetzer, S. (2022), “Advancing the Monetary Policy Toolkit through Outright Transfers”, IMF Working Paper No. 2022/87, 6 May 2022. https://www.imf.org/en/Publications/WP/Issues/2022/05/06/Advancing-the-Monetary-Policy-Toolkit-through-Outright-Transfers-517641

Central Bank of Iceland (2018), Change in credit institutions’ minimum reserve requirements, 5 June 2018. https://cb.is/news-and-publications/article/2018-06-05-Change-in-credit-institutions-minimum-reserve-requirements

Central Bank of Iceland (2024), Monetary Policy Committee Statement on changes to credit institutions’ minimum reserve requirements, 4 April 2024. https://cb.is/news-and-publications/article/2024-04-04-Monetary-Policy-Committee-Statement-on-changes-to-credit-institutions-minimum-reserve-requirements-4-April-2024

Czech National Bank (2023), CNB ends remuneration of minimum reserves, 8 September 2023. https://www.cnb.cz/en/cnb-news/press-releases/CNB-ends-remuneration-of-minimum-reserves

Czech National Bank (2024), CNB increases minimum reserve requirement, 10 October 2024. https://www.cnb.cz/en/cnb-news/press-releases/CNB-increases-minimum-reserve-requirement

De Grauwe, P. and Y. Ji (2023), “Monetary policies with fewer subsidies for banks: A two-tier system of minimum reserve requirements”, VoxEU.org, 13 March 2023. https://cepr.org/voxeu/columns/monetary-policies-fewer-subsidies-banks-two-tier-system-minimum-reserve-requirements

Duffie, D. (2026). “The Payment System Puts a Floor on the Fed’s Balance Sheet.” BPEA Conference, Spring 2026. https://www.brookings.edu/wp-content/uploads/2026/03/3_Duffie_unembargoed.pdf

ECB (2023), ECB adjusts remuneration of minimum reserves, 27 July 2023. https://www.ecb.europa.eu/press/pr/date/2023/html/ecb.pr230727~7206e9aa48.en.html

McCauley, R. and J. Pinter (2024a), “Unremunerated reserves in the Eurosystem, part 2: Tax incidence and deposit relocation risks”, 16 January 2024. https://cepr.org/voxeu/columns/unremunerated-reserves-eurosystem-part-2-tax-incidence-and-deposit-relocation-risks

McCauley, R. and J. Pinter (2024b), “Unremunerated reserves in the Eurosystem, part 1: Heads I win, tails you lose”, 15 January 2024. https://cepr.org/voxeu/columns/unremunerated-reserves-eurosystem-part-1-heads-i-win-tails-you-lose

Riksbank (2024), The Riksdag has adopted Amendments to the Sveriges Riksbank Act, 18 December 2024. https://www.riksbank.se/en-gb/press-and-published/notices-and-press-releases/notices/2024/the-riksdag-has-adopted-amendments-to-the-sveriges-riksbank-act

Riksbank (2025), Riksbank decides on interest-free deposits for credit institutions, 11 June 2025. https://www.riksbank.se/en-gb/press-and-published/notices-and-press-releases/notices/2025/riksbank-decides-on-interest-free-deposits-for-credit-institutions

Riksbank (2026), The Riksbank has decided on interest-free deposits of almost SEK 35 billion, 8 May 2026. The Riksbank has decided on interest-free deposits of almost SEK 35 billion | Sveriges Riksbank

SNB (2023), SNB adjusts remuneration of sight deposits, 30 October 2023. https://www.snb.ch/en/publications/communication/press-releases/2023/pre_20231030

SNB (2024), SNB raises minimum reserve requirement for banks, 22 April 2024.
SNB raises minimum reserve requirement for banks

Tucker, P. (2022), “Quantitative easing, monetary policy implementation, and the public finances”, IFS Green Budget 2022 Chapter 7, 14 October 2022. Quantitative easing, monetary policy implementation, and the public finances | Institute for Fiscal Studies

Whelan, K. (2021), “Are Central Banks Storing Up a Future Fiscal Problem?”, Blog posted on 16 July 2021. https://karlwhelan.com/blog/?m=2021


Can devolution help close regional productivity gaps in the UK?

The UK is pursuing one of its most ambitious devolution programmes in decades. Yet the success of devolution will depend not only on which responsibilities and decision-making powers are transferred to local governments, but also on whether local institutions have the capacity to use them effectively.

Daniela Glocker, OECD Economics Department


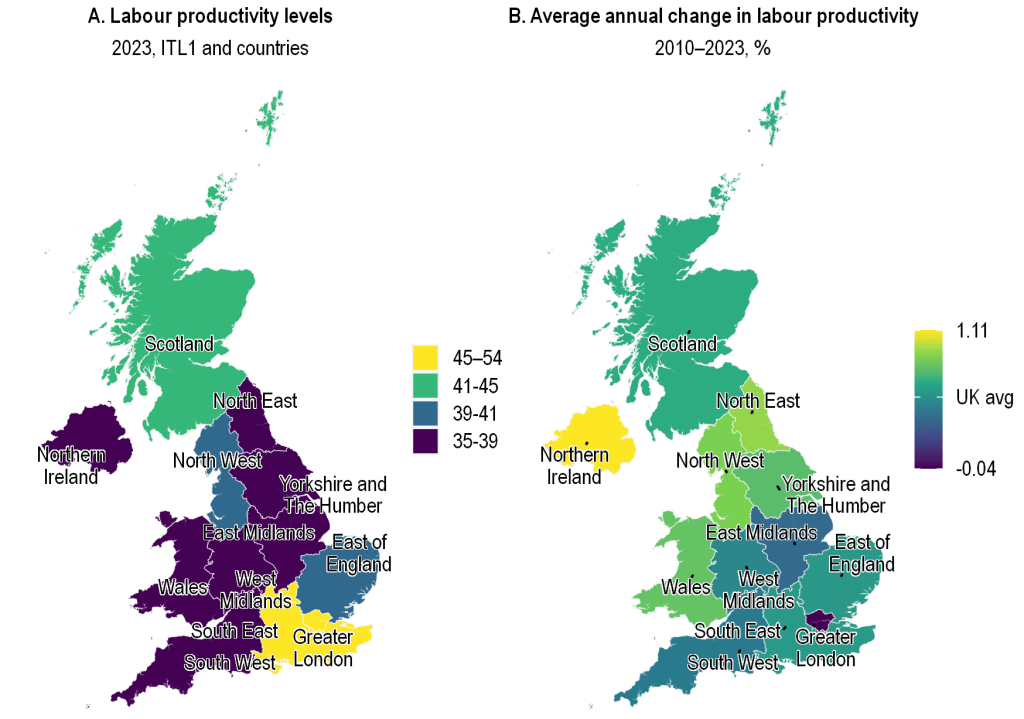
The United Kingdom faces a long-standing productivity challenge. Productivity remains considerably higher in London and parts of the South East than in many other parts of the country, contributing to substantial differences in wages, employment opportunities and living standards. At the same time, productivity growth has slowed across much of the country, including in some traditionally high-performing regions (Figure 1).

Figure 1. Labour productivity varies widely across UK regions

Map showing labour productivity levels across the UK in 2023, with regions color-coded by productivity range.

Note: Labour productivity measured as GVA per hour worked.
Source: ONS Local Indicators -Experimental (database).

Successive governments have therefore sought ways to strengthen economic performance across all regions. The current government’s Growth Mission places devolution at the centre of this effort, with new Strategic Authorities being created across England and additional powers being transferred to local governments. But can devolution itself deliver stronger growth?

The local dimension of productivity growth

The latest OECD Economic Survey of the United Kingdom argues that devolution can support productivity growth because many of the factors shaping economic performance are inherently local. Skills shortages differ across labour markets, innovation ecosystems are built around local networks of firms and universities, and infrastructure priorities vary widely between places. Local governments are therefore often better placed than central government to identify growth bottlenecks and coordinate policy responses. But devolution changes who makes decisions, not necessarily a government’s ability to deliver them.

Responsibilities alone are not enough

The UK’s devolution debate is often framed around the question of which economic responsibilities should be transferred from central to local government. Yet the effectiveness of devolution depends as much on local capacity as on the responsibilities themselves.

Some authorities have developed sophisticated economic analysis capabilities, strong delivery mechanisms and well-established partnerships with businesses and universities. Others face significant constraints related to staffing, expertise and financial resources. These differences matter because productivity-enhancing policies typically require sustained commitment and coordination. Success depends on whether local institutions possess the capacity and resources required to develop and implement long-term economic strategies.

Fiscal devolution raises the stakes

Capacity is becoming increasingly important as the government considers shifting some revenue-raising powers to the local level. Local governments remain considerably more dependent on central government funding than their counterparts in many other OECD countries. Following the Global Financial Crisis, spending restraint, fragmented funding arrangements and repeated changes to grants contributed to a decline in local governments’ real spending power (Figure 2). This often made long-term planning difficult, limited the ability of many authorities to build and retain expertise and develop long-term economic strategies. The government has begun to address some of these challenges. Recent reforms aim to simplify local government funding, provide greater funding certainty and strengthen local autonomy. These are welcome steps. More predictable funding and greater flexibility can help local authorities align policies more closely with local needs and opportunities.

https://public.flourish.studio/visualisation/30455245/

However, strengthening institutional capacity takes time. As local governments take on greater responsibilities and potentially greater fiscal autonomy, differences in institutional capacity become increasingly important. Greater autonomy can support growth by allowing policies to reflect local economic conditions and priorities, but it also raises the stakes of institutional quality. If local governments differ substantially in their ability to design, implement and evaluate policies, more devolution could inadvertently widen regional disparities rather than reduce them. Areas with stronger institutions may be better placed to translate additional powers and resources into better economic outcomes, while those with weaker capacity risk falling further behind. Strengthening local capacity is therefore essential to ensure that greater fiscal responsibility translates into stronger growth across all regions, rather than only those with the strongest institutions.

Making devolution work

Building stronger institutions therefore needs to be viewed as an economic priority. The Survey highlights the importance of:

  • prioritising training and staffing;
  • strengthening analytical capacity of local government;
  • improving policy evaluation;
  • providing greater funding certainty;
  • encouraging learning across departments and levels of government.

The UK has launched one of the most ambitious devolution programmes in years, but its productivity challenge will not be solved by devolution alone. National reforms to strengthen investment, innovation and skills remain essential. But effective devolution can help ensure that these reforms are adapted to local circumstances and translated into stronger outcomes on the ground.

The key challenge is not simply how many powers are devolved, but whether local governments have the capacity and resources needed to use those powers effectively. Devolution is most likely to succeed when greater local responsibility is matched by stronger local institutions. If this balance can be achieved, devolution can become more than a governance reform. It can help ensure that productivity gains spread more broadly across the country, rather than becoming concentrated in places that are already performing well.

References:

OECD (2026), OECD Economic Surveys: United Kingdom 2026, OECD Publishing, Paris, https://doi.org/10.1787/aa997c6e-en.


Strengthening the capacity of Latvia’s public administration

Despite recent progress, the perceived effectiveness of the public administration remains low. To reduce the administrative burden and raise public spending efficiency it is key to further simplify and digitalise administrative procedures and improve data sharing and policy impact evaluation.

by Enes Sunel, Robert Grundke


Over the past decade, Latvia has implemented significant reforms that have strengthened the rule of law and improved the business environment. The establishment of the Economic Court in 2021 has improved the efficiency of judicial proceedings. A comprehensive anti-corruption and anti-money laundering framework as well as strict party financing and conflict-of-interest rules have bolstered institutional integrity. However, overlapping functions, weak coordination and skill shortages continue to weigh on government efficiency and increase administrative burdens (Figure 1). Despite improved digitalisation of public services, limited data sharing across the public administration still complicates the implementation of one-stop shops for administrative procedures. Improving public procurement and infrastructure delivery and strengthening municipal capacities is also key for raising spending efficiency.

How can Latvia improve public administration capacity to support fiscal sustainability and economic growth? The 2026 Economic Survey of Latvia identifies four priorities:

1.     Improve the organisation of the public sector to strengthen administrative capacity

Overlapping functions among ministries and public agencies create administrative burdens and raise fiscal costs. Compensation of government employees remains above the OECD average as a share of GDP, which partly reflects relatively high wages for lower-skilled public employees and rising public employment (Figure 2). High turnover, particularly for skilled professionals and managers, and low digital and management skills have weakened institutional memory and the quality and effectiveness of public policies. Conducting thematic and cross-sectoral functional audits with a view to consolidate public bodies would help identify overlaps and reduce the public wage bill. To reduce operational costs and improve service quality, the planned shared service centre of the central government should be implemented, and its use should be made mandatory, with facilitated access for municipalities. Continuing to improve compensation for mid‑level managers and professionals and expanding training opportunities would help attract and retain talent and adapt to changing skill needs.


2.     Further leverage digitalisation to reduce administrative burdens, strengthen policy impact evaluation and improve spending efficiency

Latvia has made important progress in digitalising public services for firms and households, simplifying business registration and certain licencing and permitting procedures. However, fragmented IT systems and weak data sharing across the public administration create administrative burdens, lead to repeated information requests and hinder the implementation of one-stop shops. Reporting requirements for firms and households remain substantial, while inspections are often not risk based. Accelerating the implementation of the central data exchange platform by improving data quality, and strengthening policy impact analysis are key for reducing administrative burdens and improving spending efficiency. Better use of data could also help target inspections and ensure that reporting requirements are proportionate to risk. Improving stakeholder engagement to review, simplify and reduce existing regulations and administrative procedures should be another key priority to reduce administrative burden for all firms.

3.     Improve public procurement and infrastructure planning procedures

Well-functioning public procurement is key for delivering high-quality public services, ensuring efficient use of public resources and supporting competitive markets. Latvia’s public procurement spending as a share of GDP exceeds the OECD average (Figure 3). Given rising spending pressures from defence, health, education and social protection, raising the efficiency of public procurement is key to strengthen public finances. Procurement of many standardised goods and services remains decentralised, despite significant potential efficiency gains from centralised procurement. Consolidating purchasing bodies and extending the list of goods and services that have to be procured centrally should be combined with measures to reduce the administrative burden involved in procurement procedures, raise transparency and foster competition. Moreover, weak infrastructure planning, including limited stakeholder participation, and risk management have led to significant cost overruns and delays in major infrastructure projects, such as Rail Baltica. Using cost-benefit analysis for all major infrastructure projects and improving risk management in infrastructure procurement would support the cost-efficient planning and implementation of large infrastructure projects.


4.     Improve the administrative and financial capacity of local governments

In Latvia, municipalities are responsible for a wide range of public services, including the issuance of commercial permits and licenses, law enforcement, utilities, public transport, housing and local economic development (OECD, 2025). Skilled labour shortages and financial constraints have weakened administrative capacity and public service quality in many municipalities, prompting an administrative-territorial reform in 2021. Despite the reform, capacity constraints persist in sparsely populated and remote areas, especially as additional tasks were delegated to municipalities in 2026. Improving cooperation across municipalities and transferring administrative tasks that require less local counselling to the central government would help strengthen local administrative capacity. Moreover, revenue from recurrent taxes on immovable property, allocated to municipalities, remains low. Updating cadastral values with market values and raising property tax revenue, while continuing to provide tax deferrals to cash-poor homeowners, would strengthen municipal finances and help reduce income and wealth inequality.

References

OECD (2026), OECD Economic Surveys: Latvia 2026, OECD Publishing, Paris, https://doi.org/10.1787/34d15460-en.

OECD (2025), Government at a Glance 2025, OECD Publishing, Paris, https://doi.org/10.1787/0efd0bcd-en.


Finances publiques françaises : réduire la dette sans compromettre la croissance

La dette publique approche 120 % du PIB, au-dessus de son pic de 2021 et en forte hausse depuis fin 2023. Pour préserver ses marges de manœuvre, la France doit rétablir sa soutenabilité budgétaire par une meilleure maîtrise des dépenses, complétée à court terme par davantage de recettes.

Aussi disponible en anglais.

par Lilas Demmou, Département des affaires économiques de l’OCDE


Le niveau élevé de la dette française s’accompagne d’une dynamique de plus en plus défavorable. Elle a crû fortement après la Grande Récession de 2008, en passant d’environ 65 % du PIB en 2007 à environ 100% dans les années 2015-2019. Puis elle a bondi à plus de 115% pendant la seule année 2020, à la suite de la crise du Covid. Après être redescendue à 110% fin 2023, elle a repris un rythme de hausse très rapide et pourrait, sans ajustement, atteindre 200 % en 2050.

Après des années de taux très faibles, la France se finance désormais autour de 4,5 % sur certaines maturités, tandis que l’écart de taux avec l’Allemagne est au plus haut depuis 2012. La charge d’intérêts est passée de 1,2 % du PIB en 2000 à 2,2 % en 2025 et pourrait approcher 5 % en 2050, malgré la longue maturité de la dette, soit quasiment le budget de l’éducation nationale.

Cette évolution réduit les marges de manœuvre budgétaire, freine l’investissement et la croissance en renchérissant les coûts de l’emprunt, et rend la dette encore plus difficile à stabiliser.

Engager une consolidation ambitieuse et soutenable

Une consolidation trop rapide ou mal ciblée peut néanmoins être contre-productive. Lorsque l’activité est faible, des réductions brutales de dépenses ou des hausses d’impôts sur le travail et l’investissement réduisent la demande, l’emploi et les recettes publiques. Le ralentissement du PIB peut alors limiter, voire annuler, l’amélioration du ratio d’endettement.

La consolidation doit donc suivre une trajectoire pluriannuelle crédible, ambitieuse mais adaptée à la conjoncture. Elle doit cibler les dispositifs inefficaces et privilégier les mesures les moins défavorables à la croissance. Les réformes structurelles et les objectifs pluriannuels de dépenses renforcent davantage la confiance que des mesures temporaires reconduites.

L’effort nécessaire pour stabiliser la dette est estimé à plus de 100 milliards d’euros. Les dépenses publiques représentent environ 57 % du PIB, soit 7,4 points de plus que la moyenne de la zone euro. Les prélèvements obligatoires atteignent près de 44 % du PIB et figurent parmi les plus élevés de l’OCDE. L’ajustement devra donc reposer principalement sur une meilleure maîtrise des dépenses, même si les recettes devront également y contribuer, au moins transitoirement.

Réduire les dépenses en améliorant leur efficacité

Les retraites, la santé et les affaires économiques expliquent une grande partie du niveau et de la progression des dépenses publiques. Des économies sont possibles dans ces domaines sans remettre en cause leurs objectifs essentiels.

Note : Le terme « Sécurité » fait référence à la catégorie « Ordre et sécurité publics » de la Classification des fonctions des administrations publiques (CFAP), « Culture » à la catégorie « Loisirs, culture et culte », « Famille » à la catégorie « Famille et enfants », « Maladie » à la catégorie « Maladie et invalidité », et « Services publics » à la catégorie « Services généraux des administrations publiques.
Source : Calculs de l’OCDE fondés sur la base de données des comptes nationaux de l’OCDE

Équilibrer durablement le système de retraite et mieux répartir le coût du vieillissement

Face aux pressions exercées par le vieillissement sur le système de retraite par répartition, trois instruments peuvent être mobilisés : allonger la durée d’activité, réduire les prestations ou augmenter les cotisations. En France, malgré les réformes passées, l’âge effectif de départ à la retraite reste faible et les prestations élevées par rapport aux pays similaires, tandis que les taux de cotisation sont élevés. En conséquence, il importe d’agir principalement sur les deux premiers leviers.

Cela suppose de reprendre la mise en œuvre la réforme des retraites, aujourd’hui suspendue, afin de porter l’âge légal de départ à la retraite à 64 ans, puis d’envisager ultérieurement de l’indexer, au moins partiellement, aux gains d’espérance de vie. Cette réforme renforcerait l’emploi des seniors, tout en renforçant la croissance potentielle et les recettes fiscales. Les réformes passées ont montré leur efficacité sur la participation des 55-59 ans, mais le taux d’emploi des 60-64 ans en France restait encore inférieur de 12,2 points à la moyenne de l’OCDE en 2025. La réforme devra s’accompagner de mesures favorisant l’emploi des seniors par l’adaptation des compétences, l’ergonomie des postes, l’aménagement du temps de travail et une meilleure gestion des carrières.

Avec un niveau de vie des retraités comparable à celui des actifs, et élevé en comparaison internationale, combiné à un patrimoine plus élevé, une modération du niveau moyen des prestations pourrait être envisagée. Plusieurs leviers sont possibles : sous-indexation temporaire des pensions, tout en protégeant les pensions plus modestes ; rapprochement de leur fiscalité de celle des actifs ou remplacement de l’abattement fiscal de 10 % pour frais professionnels par un montant forfaitaire.

Améliorer l’efficience du système de santé et renforcer la prévention

Le système de santé français obtient de bons résultats, mais des écarts d’efficience subsistent par rapport aux pays affichant de meilleurs indicateurs de mortalité évitable pour un niveau de dépenses plus élevé.

Des économies durables peuvent être obtenues par un recours accru aux médicaments génériques et biosimilaires, ainsi que par une réduction des coûts administratifs, notamment grâce à une meilleure articulation entre assurance maladie obligatoire et complémentaires. Un pilotage pluriannuel de l’ONDAM améliorerait la prévisibilité des dépenses. Enfin, la France dépense insuffisamment en prévention, notamment pour le dépistage du cancer, alors que cela contribuerait à maîtriser les coûts futurs et à améliorer l’espérance de vie en bonne santé.

Concentrer les transferts sociaux sur ceux qui en ont le plus besoin

La France assure une forte redistribution grâce à un volume élevé de transferts, mais leur ciblage peut être amélioré. Certaines prestations familiales ou aides au logement pourraient davantage tenir compte du revenu, de la composition du ménage et, lorsque cela est pertinent, du patrimoine.

Mobiliser les recettes en limitant leurs effets sur la croissance

Le redressement budgétaire ne pourra probablement pas reposer exclusivement sur les dépenses. La contribution des recettes doit cependant éviter une hausse générale des prélèvements sur le travail et l’investissement.

La priorité devrait être de réduire les dépenses fiscales les moins efficaces, économiquement comparables à des dépenses budgétaires, mais souvent moins transparentes et moins évaluées. La suppression progressive de certains taux réduits de TVA (par exemple sur la restauration ou les travaux de rénovation) dont l’efficacité économique n’a pas été démontrée ou de composantes du crédit d’impôt recherche bénéficiant aux grandes entreprises permettrait d’élargir les assiettes sans relever les taux.

Les exonérations de cotisations sociales représentent environ 80 milliards d’euros par an. Leur efficacité est établie pour les bas salaires, mais moins clairement pour les rémunérations intermédiaires. Un recentrage pourrait dégager des ressources pour réduire les impôts de production et financer la formation, qui affectent plus directement la croissance et la compétitivité.

La fiscalité pourrait être progressivement rééquilibrée du travail vers des assiettes plus larges, notamment la consommation, par la suppression graduelle des réductions sectorielles de TVA les moins efficaces ; les externalités environnementales, via une tarification des émissions complétée, à plus long terme, par une fiscalité fondée sur la congestion et les kilomètres parcourus ; ainsi que certains éléments du patrimoine, au moyen d’une rationalisation des nombreux abattements et régimes préférentiels applicables aux successions et aux plus-values latentes.

Redresser les finances publiques sans compromettre l’avenir

La consolidation budgétaire ne doit pas conduire à une baisse des dépenses d’avenir, c’est-à-dire les dépenses publiques qui favorise une croissance soutenable, comme les dépenses consacrées à la santé, à l’innovation, à l’éducation ou à la transition climatique. Une stratégie budgétaire ambitieuse, pluriannuelle et s’appuyant sur des revues de dépenses pour préserver celles les plus efficaces peut ainsi restaurer la soutenabilité de la dette tout en préservant la capacité de la France à financer durablement ses priorités.

Référence:

OCDE (2026), Études économiques de l’OCDE : France 2026, Éditions OCDE, Paris, https://doi.org/10.1787/65cc698e-fr.


France’s public finances: Reducing debt without compromising growth

Public debt is approaching 120% of GDP, above its 2021 peak and a sharp rise since the end of 2023. To preserve fiscal room for manoeuvre, France must restore fiscal sustainability through tighter control of public spending, complemented in the short term by additional revenue measures.

Also available in French

by Lilas Demmou, OECD Economics Department


France’s high public debt is on an increasingly unfavourable trajectory. It rose sharply after the 2008 Global Financial Crisis, increasing from around 65% of GDP in 2007 to about 100% between 2015 and 2019. It then surged to more than 115% in 2020 alone following the COVID-19 crisis. After falling back to 110% at the end of 2023, it began rising very rapidly again and without policy adjustment, could reach 200% by 2050.

Following years of very low interest rates, France now borrows at around 4.5% at some maturities, while the spread with German government bonds is at its highest level since 2012. Interest expenditure increased from 1.2% of GDP in 2000 to 2.2% of GDP in 2025 and, despite the long average maturity of public debt, could approach 5% of GDP by 2050. This would be almost equivalent to the current education budget.

These developments are narrowing fiscal space, weighing on investment and growth by raising borrowing costs, and making public debt increasingly difficult to stabilise.

Pursuing ambitious and sustainable fiscal consolidation

Overly rapid or poorly designed consolidation could nevertheless be counterproductive. When economic activity is weak, abrupt spending cuts or increases in taxes on labour and investment reduce demand, employment and public revenue. The resulting slowdown in GDP can then limit or even offset the improvement in the debt-to-GDP ratio.

Consolidation should therefore follow a credible multi-year path that is ambitious but responsive to economic conditions. It should target ineffective programmes and prioritise measures with the smallest adverse effects on growth. Structural reforms and multi-year expenditure objectives are more likely to strengthen confidence than temporary measures that are repeatedly extended.

The adjustment needed to stabilise public debt is estimated at more than EUR 100 billion. Public expenditure accounts for around 57% of GDP, 7.4 percentage points above the euro-area average. France’s tax-to-GDP ratio is almost 44% of GDP and is among the highest in the OECD. The adjustment should therefore rely primarily on better expenditure control, although revenue will also need to contribute, at least temporarily.

Reducing spending while improving its effectiveness

Pensions, healthcare and economic affairs account for a large share of both the level and growth of public expenditure. Savings can be achieved in these areas without undermining their core objectives.

Note: Safety stands for “Public order and safety and for Recreation”, Culture for “Recreation, culture and religion”, Family for “Family and children”; Sickness for “Sickness and disability”; Public services for “General public services”.
Source: OECD Calculations based on OECD National Accounts database.

Putting the pension system on a sustainable footing and sharing the cost of ageing more fairly

Three main instruments are available to address the pressures that an ageing population places on the pay-as-you-go pension system: extending working lives, reducing benefits or increasing contributions. In France, despite previous reforms, the effective retirement age remains low and pension benefits are relatively high compared with peer countries, while contribution rates are already elevated. Policy action should therefore focus primarily on the first two instruments.

This would require resuming implementation of the currently suspended pension reform to raise the statutory retirement age to 64. France could then consider linking the retirement age, at least partly, to gains in life expectancy. Such reforms would increase employment among older people, strengthen potential growth and raise tax revenue. Previous reforms have successfully increased the labour force participation of people aged 55 to 59. However, in 2025, France’s employment rate of people aged 60 to 64 remained 12.2 percentage points below the OECD average.

Reforming the pension system should be accompanied by measures to promote the employment of older workers, including skills adaptation, improved workplace ergonomics, more flexible working-time arrangements and better career management.

The living standards of pensioners are comparable to those of the working-age population and are high by international standards. Pensioners also hold greater wealth on average. Some moderation in average pension benefits could therefore be considered.

Several options are available, including temporarily indexing pensions below inflation while protecting lower pensions, bringing the tax treatment of pensions closer to that of labour income, or phasing out the 10% tax allowance for pensioners.

Improving the efficiency of health spending while strengthening prevention.

The French healthcare system achieves good outcomes. However, efficiency gaps remain as France achieves lower rates of mortality that could be prevented compared to best performing countries, despite higher levels of spending.

Long-lasting savings could be achieved through greater use of generic and biosimilar medicines and through lower administrative costs, notably by improving co-ordination between statutory health insurance and complementary health insurance schemes. A multi-year framework for the national health insurance expenditure target, ONDAM, would improve expenditure predictability.

France also spends too little on prevention, including cancer screening. Increasing well-targeted preventive expenditure could help contain future healthcare costs and improve healthy life expectancy.

Targeting social transfers more closely at those most in need

France achieves substantial redistribution through a high volume of social transfers, but their targeting could be improved. Some family benefits and housing allowances could take greater account of household income, household composition and, where appropriate, wealth.

Raising revenue without undermining growth

Fiscal consolidation is unlikely to be achieved through spending measures alone. However, the contribution from revenue should avoid broad-based increases in taxes on labour and investment.

A priority should be to reduce the least effective tax expenditures. These are economically comparable to direct public spending but are often less transparent and subject to less evaluation. Tax bases could be broadened without increasing statutory rates. This should include by gradually eliminating reduced VAT rates whose economic effectiveness has not been demonstrated, including those applying to restaurants or renovation work, and by removing components of the research and development tax credit (CIR) that benefit large companies but generate limited additional research activity.

Exemptions from social security contributions amount to around EUR 80 billion annually. Their effectiveness is well established for low-paid workers, but less clearly demonstrated for workers on intermediate wages. Better targeting these exemptions could release resources to reduce production taxes and finance training, which have a more direct impact on growth and competitiveness.

The tax system could gradually be rebalanced away from labour and towards broader tax bases. Options include:

  • increasing consumption taxation by gradually removing the least effective sector-specific VAT reductions;
  • pricing environmental externalities more effectively through more comprehensive emissions pricing, complemented in the longer term by taxation based on road congestion and distance travelled; and
  • reforming the taxation of wealth by rationalising the numerous allowances and preferential regimes applying to inheritance and unrealised capital gains.

Restoring the public finances while safeguarding the future

Fiscal consolidation should not lead to cuts in spending for the future. This includes public expenditure that supports sustainable growth, particularly spending on health, innovation, education and the climate transition.

An ambitious multi-year fiscal strategy, supported by systematic spending reviews that identify and protect the most effective programmes, could restore debt sustainability while preserving France’s capacity to finance its long-term priorities and strengthen potential growth.

References:

OECD (2026), OECD Economic Surveys: France 2026, OECD Publishing, Paris, https://doi.org/10.1787/e88a1716-en.


A boost from Artificial Intelligence in ageing societies?

Demographic headwinds are set to weaken economic growth in OECD countries over the coming decades. At the same time, artificial intelligence (AI) provides opportunities for productivity gains, potentially alleviating labour shortages and boosting economic growth.

By Christophe André and Matthias Schief, OECD Economics Department


Population ageing and AI adoption across a growing number of economic activities are affecting growth prospects in opposite directions. While population ageing could reduce real per capita income growth by up to 0.8 percentage points per year in some OECD countries over the coming decades (André et al., 2024), AI could boost it by up to one percentage point per year over the next ten years, assuming an adoption speed similar to that of previous ICT technologies, such as computers and the internet (Filippucci et al., 2026). However, little is known about the interactions between these two megatrends. 

In a new paper (André and Schief, 2026), we provide early insights on how exposure to AI varies over the life cycle and what this may imply for AI deployment in ageing societies. In recent years, several studies have assessed occupation-level and task-level exposure to AI in the United States (Felten et al., 2021; Eloundou et al., 2024). Other studies (Georgieff and Hyee, 2021; Lewandowski, Madoń and Park, 2025) have used the OECD Survey of Adult Skills (PIAAC) to derive AI-exposure indicators for broad sets of countries. The PIAAC dataset contains rich information on respondents, which allows relating AI exposure to demographic and socio-economic characteristics, including age. The detailed description of tasks performed by respondents also allows distinguishing jobs exposed to automation, where AI may directly replace workers, from jobs exposed to augmentation, where AI complements workers’ abilities to make them more productive.   

We construct a new index of AI exposure at the individual level, using the latest vintage of PIAAC data. We distinguish between individuals that are exposed to AI (types II and III) and those that are not (type I) using information about two broad aspects of their job: the presence of a strong physical component and the daily use of computers or other electronic devices (Table 1). Responses indicating the degree to which work is proceduralised versus context dependent are used to differentiate between exposure to automation versus augmentation. Proceduralised work refers to activities whose essential functions can be codified into relatively stable and well-defined sequences of actions performed within a relatively rigid production process (for example, standard insurance claim processing or legal document drafting). By contrast, context dependent work is not fully specified ex ante, and the sequence of tasks must often be adapted in real time to changing circumstances, involving human judgement (for example, project management under changing constraints).

Table 1. A classification of AI exposure

  Proceduralised work Non-proceduralised work
Strong physical component or no computer use Not exposed to AI (Type I) Not exposed to AI (Type I)
No strong physical component and daily computer use Exposed to automation (type II) Exposed to augmentation (type III)

While our classification has the merit of parsimony and transparency, it is also somewhat coarse, as it relies on a limited number of job characteristics and classifies all workers in only three categories, which cannot fully capture the wide variety of occupations in the economy. Nevertheless, our classification correlates strongly at the occupation level in the United States with the respective exposure measures in Felten et al. (2021) and in Eloundou et al. (2024), which are derived from more detailed information on work tasks and AI capabilities. The distribution of automation and augmentation exposure within industries is also consistent with early evidence on adoption and employment patterns across economic sectors.

Our overall (automation and augmentation) exposure to AI indicator exhibits an inverted U-shaped pattern across age groups (Figure 1, left panel). However, this pattern is less pronounced when controlling for education, occupation and country, pointing to the role of differences across cohorts in education and occupational choices in explaining differences in AI exposure between age groups. Exposure to automation is highest in younger age groups and declines rapidly with age, with middle-aged and older workers less exposed to substitution as their experience tends to complement AI (Figure 1, right panel). Exposure to automation remains similar when controlling for education, occupation and country, suggesting only minor influence of cohort effects. The strong exposure of youth to automation is in line with the weak entry-job creation in AI-exposed sectors observed recently in several OECD countries, even though evidence on the role of AI remains mixed.

With AI more likely to complement middle-aged and older workers than replace them, ageing societies may receive a boost from AI. The technology could help lengthen working lives, if it improves job quality by reducing repetitive tasks and facilitating skills updating. This would alleviate potential labour shortages and is key to preserving growth potential and fiscal sustainability (Koutsogeorgopoulou and Morgavi, 2025). Productivity gains would also contribute to mitigating the demographic drag on GDP per capita.

Nevertheless, these potential benefits do not come without challenges. As a general-purpose technology, AI is bound to be disruptive, imposing significant changes in work processes. Even workers with skills that complement AI may need to change jobs in response to changing demands for their competences and need reskilling and upskilling to efficiently use AI. This may prove more difficult in ageing societies, as job mobility and occupational transitions fall sharply with age (Figure 2) and older workers tend to receive less training than younger ones, which could lead to skill obsolescence as technological change accelerates. In addition, the intergenerational transmission of knowledge may be hampered if a shortage of entry jobs reduces opportunities for young people to learn on the job.  

Furthermore, business dynamism and innovation may weaken in ageing societies, which could slow the diffusion of AI and hold back productivity gains. Weakening workforce growth has been linked to declining firm entry rates in the United States (Karahan et al., 2024), but studies on other OECD countries remain scarce.

To sum up, AI may offer opportunities for ageing societies to at least partly offset the demographic drag on economic growth. However, this will require overcoming major challenges in lifelong learning, labour reallocation and business dynamism and innovation. Furthermore, while demographic headwinds will persist for decades, it is unclear whether AI will lead to a level shift in productivity or to persistently higher growth, for example through continuous development in robotics or fast progress towards AGI (Artificial General Intelligence).

A modern office setting showing individuals working at computers, with a humanoid robot seated among them, discussing the macroeconomic effects of artificial intelligence.

References

André, C. and M. Schief (2026), “A boost from AI in ageing societies? Early insights”, OECD Economics Department Working Paper, No. 1870, OECD Publishing, Paris.

André, C., P. Gal and M. Schief (2024), “Enhancing productivity and growth in an ageing society: Key mechanisms and policy options”, OECD Economics Department Working Papers, No. 1807, OECD Publishing, Paris, https://doi.org/10.1787/605b0787-en.

Eloundou, T., S. Manning, P. Mishkin and D. Rock (2024), “GPTs are GPTs: Labour market impact potential of LLMs”, Science, 384 (6702), 1306-1308.

Felten, E., M. Raj and R. Seamans (2021), “Occupational, industry, and geographic exposure to artificial intelligence: A novel dataset and its potential uses”, Strategic Management Journal, 42(12), 2195-2217.

Filippucci, F., P. Gal, K. Laengle, M. Schief and M.A. Yildirim (2026), “AI meets trade: Global linkages and the cross-country distribution of the gains from AI”, OECD Artificial Intelligence Papers, No. 57, OECD Publishing, Paris, https://doi.org/10.1787/13081644-en.

Georgieff, A. and R. Hyee (2021), “Artificial intelligence and employment : New cross-country evidence”, OECD Social, Employment and Migration Working Papers, No. 265, OECD Publishing, Paris, https://doi.org/10.1787/c2c1d276-en.

Karahan, F., B. Pugsley and A. Şahin (2024), “Demographic Origins of the start-up Deficit”, American Economic Review, 114(7), 1986-2023, https://doi.org/10.1257/aer.20210362.

Lewandowski, P., K. Madoń and A. Park (2025), “Workers’ exposure to AI across development”, IBS Working Paper, 02/2025, Institute for Structural Research (IBS), Warsaw, https://ibs.org.pl/wp-content/uploads/2025/03/Workers_AI_exposure_across_development_IBS_WP_202502.pdf.


Switzerland: Navigating through uncertainty

As a small, open economy, Switzerland has been highly exposed to recent global developments including swings in external demand, major changes in international trade policies and geopolitical uncertainty. The economy has weathered these shocks well: Inflation and unemployment are low and public finances are sound. But growth has been below trend since 2024, falling short of the annual average growth rate of 1.8% of the previous decade. Bolstering growth and resilience will hinge on building stronger ties with key trading partners, but also on forging new trade partnerships. This will lay the grounds for diffusing productivity growth beyond export-oriented sectors and firms.

by Priscilla Fialho and Adolfo Rodriguez-Vargas, OECD Economics Department


Strengthening ties with trading partners and expanding potential export markets

The Swiss economy is very open to international trade and its exports amount to 78% of GDP, compared with an OECD average of 30%. Major destinations for Swiss goods exports include the European Union, the United States, and China.

Switzerland’s European policy is based on bilateral sectoral agreements, given that the country is not a member of the European Union (EU). This has given it access to parts of the single market while maintaining a degree of discretion and autonomy for the adoption of EU law. Over the past 50 years, there have been more than 120 such bilateral deals. But maintaining single market access in the future will hinge on a more rigorous application of evolving EU rules and procedures. The new Swiss – European Union package of agreements is set to implement this and preserve single market access for Swiss firms. This will enhance the stability and predictability of Switzerland-EU relations, boost investment and expand cooperation into new areas such as electricity markets, improving energy affordability and ensuring reliable supply.

Upgrading the current free trade agreement with China could provide further opportunities. The existing agreement eliminated most tariffs for Swiss good exports, but some products like watches and pharmaceuticals still face significant tariffs. Switzerland could also gain from better conditions for services exports to China. Ratifying the recent EFTA agreements with MERCOSUR, Malaysia and Thailand, and pursuing efforts to update the terms of the agreement with Mexico, would also open new opportunities and spread risks. Closer ties with the United Kingdom, including the negotiated upgrade of the 2019 free trade agreement on 13 July 2026, are also welcome and the mutual recognition of financial supervisory arrangements can boost financial services trade between both countries. But such agreements can be very technical and not all of the opportunities that they entail are evident to firms. More could be done to explain how the private sector can harness existing Free Trade Agreements to diversify export markets and improve the resilience of Switzerland’s position in global value chains.

Boosting broad-based productivity growth

Switzerland’s productivity is among the highest in the OECD. However, productivity growth has not been homogeneous across all sectors and firms. In recent decades, it has been mostly driven by large, high-value-added, and export-oriented firms in the sector of pharmaceuticals. Increasing productivity spillovers from these firms to smaller and domestically oriented firms would lift overall productivity and improve the resilience of the economy to external shocks.

Access to high-quality and affordable telecommunications and energy, for example, would help boosting the performance of downstream firms in all sectors of the economy. Currently, only large users can freely choose their retail electricity or gas supplier or sell excess own-produced electricity to third parties. Regional monopolies continue to dominate retail electricity markets, which may well be a lost opportunity to achieve lower prices. Similarly, high state participation in the telecommunications sector weakens competition. In professional services like notaries or healthcare professionals, it is excessively tight cantonal regulations that hamper competition. Navigating the complex system of licenses and permits across different jurisdictions drives up the costs for firms, disproportionally affecting smaller businesses. Boosting competition in these sectors would help increase spillovers towards less productive sectors and firms. Concrete examples for policy action in services sectors include harnessing the new electricity agreement with the European Union to boost competition; separating the management, operations and accounting of large state-owned companies in telecommunications, and opening more ancillary operations to private participation. Implementing the silence-is-consent principle for licensing low-risk activities could also ease administrative burdens.

Labour shortages still affect many sectors of the Swiss economy, particularly in manufacturing and construction, where more than a quarter of firms report severe recruiting difficulties, and among smaller companies. Information and Communication Technologies specialists and scientific technicians are often hard to find, which may impair technology spillovers to less productive firms. More generally, enhancing skills could bring significant benefits for the wider diffusion of productivity gains in a skill-intensive economy like Switzerland. Ensuring appropriate provision of affordable childcare would allow more women to participate in the labour market and address skill gaps. Facilitating switches between academic and vocational tracks of education could ease these gaps in technical fields.

Although Switzerland ranks among the world’s most innovative countries, innovation activity has been slowing, particularly in smaller firms. Enhancing innovation support for SMEs can increase their engagement in R&D activities. Switzerland has instruments tailored to SMEs, like Innosuisse’s innovation cheques to fund preliminary studies and tests with external experts, but more could be done to make firms aware of these and similar opportunities.

References

OECD (2026), OECD Economic Surveys: Switzerland 2026, OECD Publishing, Paris, https://doi.org/10.1787/48b03aff-en.