What’s holding back competition in energy markets?

Electricity and natural gas markets power modern economies. They fuel industrial production and transportation services, enable digital infrastructure, and meet households’ everyday energy needs. Because electricity and gas are inputs needed in almost every economic activity, how these markets perform matters beyond the energy sector itself.

By Cassie Castle, OECD Economics Department

Lire en français/French version


A large body of evidence shows that well-designed, competitive energy markets can discipline prices, strengthen investment incentives, and support innovation. Competition forces firms to improve efficiency, adopt new technologies and respond to consumer needs. When competition is weak, those pressures fade (OECD, 2022). The result is not only higher energy bills, but wider consequences for businesses, households and economic performance.

According to a new OECD working paper based on the OECD Product Market Regulation (PMR) indicators, countries have already undertaken significant reforms to support competition. For much of the 20th century, electricity and natural gas sectors were mostly organised as vertically integrated state-owned monopolies, with limited incentives for efficiency or innovation. A major wave of liberalisation reforms, particularly during the 1990s, transformed this model. Many countries made significant steps to unbundle monopoly networks, regulate third-party access to infrastructure and open generation and retail markets to new entrants.

Despite this progress, important gaps remain. The new OECD working paper examines the current state of the regulatory framework in the electricity and natural gas markets across 50 countries. It evaluates the extent to which these frameworks support competition by lowering entry barriers, ensuring non-discriminatory access to monopoly network services and reducing switching costs across the supply chain. Drawing on the latest update of the OECD PMR indicators, the paper shows that while legal liberalisation is widespread, key regulatory shortcomings continue to limit the full benefits of competition (see Figure).

The PMR Sector Indicator for Energy: Latest results

Four issues stand out:

First, in some countries the monopoly network infrastructure — transmission and distribution grids — remains weakly separated from competitive activities like generation, storage and retail supply. In electricity, around 10% of surveyed countries impose only accounting separation or no separation at all. In natural gas, this rises to around 16% of countries. Where vertical integration persists, firms have both the incentive to favour their own affiliates and restrict rivals’ access to essential networks. Stronger forms of unbundling, such as legal or ownership separation, provide more robust safeguards and are widely recognised as best practice.

Second, a number of countries continue to restrict households and small businesses from choosing their retail energy supplier and maintain broad retail price regulation beyond targeted support for vulnerable households. This is usually the case when the market is not yet fully competitive. Where entry barriers persist, switching costs are high, or wholesale markets do not function effectively, premature liberalisation can lead to poor outcomes for consumers. However, concerns about price volatility may offer an additional explanation for why regulated retail tariffs remain in place, sometimes alongside market-based offers, particularly following the 2021-2023 energy crisis. Sharp price swings prompted some countries to extend or maintain retail price regulation for small consumers, even in otherwise well-developed markets. The paper explores this tension further. While price controls can provide stability in periods of stress, open-ended measures risk distorting price signals, weakening competitive pressures over time and reducing the benefits of open markets.

Third, even where consumers are free to choose, many lack the tools to engage effectively in retail markets. Retail competition can only deliver meaningful benefits if consumers have access to the information needed to make informed decisions when choosing their supplier. Most countries require suppliers to provide detailed consumption and cost data in monthly bills, but only a few also offer independent price comparison tools. The low rate of roll-out of smart meters also limits the information available to consumers to understand their patterns of consumptions and select the most suitable tariff. Without active support to help consumers make informed choices, the time and effort required to compare offers and change supplier acts as a barrier, even when cheaper offers exist. Lowering these switching costs is essential to making competition work in practice.

Fourth, in electricity markets, demand-side flexibility is increasingly important for grid stability and cost efficiency, helping manage peak demand and integrate variable renewables. However, explicit demand response is not universally available. Around 21% of the countries surveyed do not allow these programmes, and among those that do, roughly one-third restrict participation to industrial users, leaving smaller consumers, in particular households, largely excluded. Expanding household participation requires smart meter deployment to enable time-of-use and dynamic tariffs, alongside regulatory frameworks that permit dynamic pricing and aggregator participation. When these conditions are in place, households can shift consumption away from peak periods, reducing their energy bill, while limiting system costs and strengthening grid stability.

These findings point to an unfinished reform agenda. Legal liberalisation has advanced considerably, yet structural gaps still limit countries from enjoying the benefits of effective competition. Closing these gaps is becoming more urgent as energy systems shift toward higher shares of renewable and decentralised generation. Integrating variable supply requires greater flexibility through responsive demand and clear price signals. Competitive markets are key to delivering these adjustments efficiently. Completing the reform process is therefore not only about improving outcomes within the energy sector, but about supporting a more resilient energy system that underpins productivity and growth across the wider economy.

References

Castle, C. and C. Varriale (2026), “Building competitive energy markets: Regulatory insights from the OECD PMR indicators”, OECD Economics Department Working Papers, No. 1863, OECD Publishing, Paris, https://doi.org/10.1787/f47862f5-en.

OECD (2022), “Competition in Energy Markets”, OECD Roundtables on Competition Policy Papers, No. 290, OECD Publishing, Paris, https://doi.org/10.1787/e2e1b9be-en.

For more information, please visit the OECD Product Market Regulation (PMR) webpage: https://www.oecd.org/en/topics/product-market-regulation.html



Wired for power: The energy behind the AI revolution

Artificial intelligence is fast becoming a defining driver of electricity demand in Europe. As AI deployment accelerates, the key constraint is shifting from computing power to the capacity of electricity grids to absorb large, continuous and localised loads. This blog examines how updating and modernising grid planning, connection rules and energy regulation are emerging as important enablers of AI’s future in the EU.

By Ruben Maximiano and Wouter Meester, OECD Economics Department.


AI’s energy reality

Dieser Blog ist auch auf Deutsch verfügbar: Strom – die treibende Kraft der KI-Revolution

AI is often discussed as though it operates independently of physical systems. In practice, AI depends on vast amounts of electricity. Its future will be determined not only by advances in algorithms and computing power, but also by kilowatt-hours – by the ability of electricity systems to deliver power reliably and at scale.

Training and running frontier models requires continuous and increasingly large volumes of power. According to the IEA, a typical AI-focused data centre already consumes as much electricity as 100 000 households, whilst the largest new facilities could require 20 times more, placing them on par with the consumption of small countries (IEA, 2025).

As a result, an important binding constraint on AI deployment is no longer generation alone. It is increasingly the capacity of electricity systems to absorb, transport and manage large, continuous and geographically concentrated loads without conflicting with other usages. As the recent OECD Diagnostic Tool for Reducing Regulatory Barriers to Solar, Wind and Pumped Hydro Storage in the EU report shows, tackling these also involve better regulations.

The importance of energy to AI roll-out is visible in corporate energy sourcing strategies. Big Tech companies now account for the majority of Corporate Power Purchase Agreements (PPAs) in Europe (see figure 1). Yet the scale and speed of AI deployment are already outpacing what traditional PPAs can guarantee. Hyperscalers are turning to direct investment in generation, including solar, wind and nuclear, to secure long-term supply.

Taken together, these developments point to the conclusion that the next frontier of AI policy is not only about how much electricity is produced, but also about how grids are planned, reinforced and that to a significant extent depends on how grid investment and grid connection rules are regulated.

To address such barriers systematically in the EU, the OECD report Diagnostic Tool for Reducing Regulatory Barriers to Solar, Wind and Pumped Hydro Storage in the EU, identifies the regulatory bottlenecks that slow deployment of renewables in the EU and constrain grid availability, with clear parallels for policymakers seeking to adapt energy rules to enable AI deployment. As this blog is based on this work it refers mainly to EU practices and energy mix.

Global AI and local grids

While global electricity demand from AI remains moderate (expected to reach 3% globally by 2030 and 4.5% in the EU)(IEA 2025, Ember 2025), its impact is highly concentrated. Data centres cluster in locations offering robust fibre connectivity, favourable cooling conditions, low electricity prices, and fast, reliable grid access. This concentration amplifies pressure on local grids and exposes the limits of existing planning and connection frameworks.

Ireland illustrates these risks. In 2023, data centres accounted for around 21% of electricity consumption in 2023 up from 5% in 2015. Much of this has been concentrated around Dublin, where data centres consume roughly half of electricity produced. The resulting strain on the network raised security-of-supply concerns and led to the Transmission System Operator stop accepting applications for new data centres in Dublin until 2028 (Ember, 2025, CRU, 2025). In response, the national regulator is introducing a number of regulatory changes, including requirements for new data centres to install dispatchable generation or storage facilities on site.

The countries with more abundant and affordable electricity and stronger grids have a comparative advantage for the location of data centres. For instance, the Nordic countries have become attractive AI destinations due to abundant energy, strong grids and low-carbon baseload (Ember 2025). More broadly, IEA analysis suggest that jurisdictions offering significantly faster grid-connection timelines could capture up to 20% more data-centre growth by 2030 (IEA, 2025).

How AI stresses electricity systems

These pressures materialise across three interconnected timescales. In the long term, large AI campuses require transmission and distribution networks with sufficient hosting capacity, yet grid expansion and permitting often take 5 to 10 years. This makes anticipatory planning and co-ordination between data-centre siting, grid investment and local generation essential. Just as important is grid optimisation: improving system efficiency through digitalisation and AI-based system management.

In the medium term, inefficient connection rules have become a binding constraint. Long queues, speculative applications and first-come, first-served rules delay viable projects and distort planning. In real time, AI workloads introduce rapid power swings – far faster than traditional industrial loads -challenging frequency stability and voltage control.

Addressing these pressures requires regulatory frameworks that enable not only physical grid reinforcement, but also optimisation through digitalisation, flexibility procurement and stability services, and that allow system operators to invest in software and operational solutions alongside traditional capital assets.

The Diagnostic Tool shows that key elements of the regulatory system that contribute to address these pressures, would include:

  • Anticipatory grid investment supported by clear cost-recovery rules.
  • Criteria-based connection queues to prioritise ready and system-beneficial projects.
  • Hosting-capacity maps to guide efficient siting.
  • Flexible access arrangements, including non-firm and hybrid connections.
  • Tariff and market design that value flexibility and stability services.

How countries are responding

Countries are increasingly adapting electricity regulation to manage the highly localised grid impacts of AI-driven demand. Governments are experimenting across different parts of the power system. In Europe, Italy is improving locational planning through detailed hosting-capacity maps; Portugal is reallocating unused capacity and simplifying storage licensing; the UK is reforming connection queues by prioritising projects that are “first ready, first connected”; the Netherlands is deploying congestion-management zones and prioritisation criteria; and Finland is integrating data centres into heat-recovery and clean-power strategies.

Despite this diversity, common policy lessons seem to emerge. Grid access can no longer be treated as a simple administrative queue and requires prioritisation based on readiness. Locational transparency is critical to guide efficient investment. Flexibility and digital optimisation must complement traditional grid reinforcement. Finally, grid planning and permitting need to become anticipatory rather than reactive. Countries applying these principles are better positioned to accommodate AI-scale demand while preserving reliability and affordability.

Powering the age of intelligence

AI is reshaping electricity demand at a scale that is now central to economic strategy. Ensuring reliable, affordable and low-carbon supply is becoming a prerequisite for attracting and sustaining digital investment. In the age of AI, competitiveness, autonomy and resilience will increasingly be determined not only by data and algorithms, but by the rules that govern the compute infrastructure and their electricity systems.

The OECD–EU Diagnostic Tool offers governments a practical roadmap to modernise regulatory frameworks and align them with the needs of an electricity-intensive digital economy.

*We will be launching the Diagnostic Tool today, 29th January. You may register here.

References

CRU, “Large Energy Users connection policy”, December 2025, https://cruie-live-96ca64acab2247eca8a850a7e54b-5b34f62.divio-media.com/documents/CRU2025236_Large_Energy_User_connection_policy_decision_paper.pdf

Ember, 2025, Grids for data centres: ambitious grid planning can win Europe’s AI race, https://ember-energy.org/app/uploads/2025/06/Grids-for-data-centres-in-Europe.pdf

IEA, 2025, Energy and AI, World Energy Outlook Special Report

OECD, 2025, OECD–EU Diagnostic Tool for Reducing Regulatory Barriers to Solar, Wind and Pumped Hydro Storage


Powering competitiveness: Europe’s path to energy security and growth

by Ruben Maximiano and Wouter Meester, OECD Economics Department.

Europe’s competitiveness is increasingly linked to the availability of secure, affordable and reliable electricity. As electrification accelerates across industry, transport, heating and digital services, including AI data centres, power has become a strategic input to growth, investment and innovation, a point also underscored by the 2024 Draghi report. However, as outlined in a recent OECD report Diagnostic Tool for Reducing Regulatory Barriers to Solar, Wind and Pumped Hydro Storage in the EU, five key types of regulatory barriers slow the deployment of these technologies in Europe. This results in significant opportunity costs, especially in the European Union, where high import dependence exposes firms and households to price volatility, supply shock and higher prices.

The 2021–22 energy crisis laid bare this vulnerability: the EU’s energy import bill surged from EUR 137 billion in 2020 to nearly EUR 549 billion in 2022. Even after prices eased, the 2023 import bill remained well above historical levels.

Why the electricity system is changing and why rules matter

At the same time, Europe’s power system is being reshaped by technologies with fundamentally different system characteristics, including variable renewables, storage, demand-side response and digital controls. These resources increase the need for flexibility, real-time coordination across grids and more granular planning, particularly as new electricity-intensive loads, such as data centres, concentrate demand in specific locations. This transformation exposes the limits of regulatory frameworks designed for a centralised, thermal-based system. Ensuring the EU’s energy security, including by delivering its new energy mix, depends on fit-for-purpose regulation as much as on physical infrastructure.

Competitiveness increasingly depends on affordable, “always-on” electricity

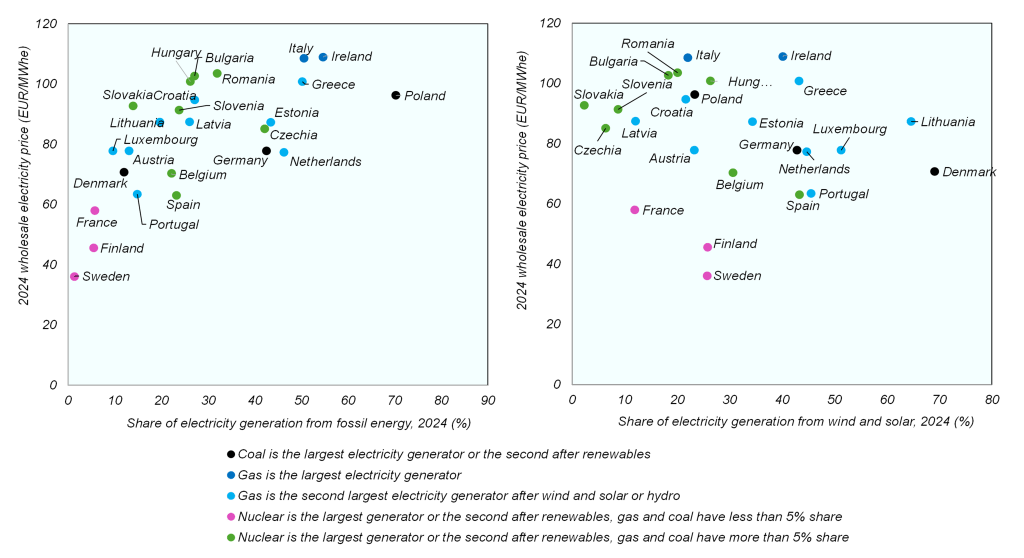
In addressing its energy security, Europe has already made important progress. Since Russia’s invasion of Ukraine, renewable energy has expanded substantially, helping to cushion price shocks (see Figure 1). Evidence suggests that EU countries with higher shares of wind and solar in their electricity mix tend to exhibit lower wholesale prices on average (Figure 2), reflecting the declining technology costs and the downward pressure renewables place on marginal pricing. Moreover, recent system-level modelling by WindEurope shows that, even once the additional cost of grids, storage and backup capacity are taken into account, a renewables-led pathway is the lowest-cost option for Europe’s power system.

Figure 2. Relationship between the average wholesale electricity prices and the share of electricity generation from wind and solar in EU Member States, 2024

Source: OECD calculations based on Ember Yearly and Hourly Electricity Data

Yet the next wave of electrification will put (even greater) pressure on the EU’s electricity system. For example, in the EU, demand from data centres could rise from around 96 TWh in 2024 to about 236 TWh by 2035, increasing their share of total electricity use from 1.5% to nearly 6%.

Energy system upgrades require regulatory upgrades – and a tool to help deliver them

This increasing electrification, with more decentralised generation, new flexibility technologies and large, concentrated loads such as data centres, requires regulatory frameworks that are aligned with these new system characteristics.

In this context, regulation increasingly functions like infrastructure itself: it must be planned ahead of need, operate reliably, and remain aligned with system needs. Outdated or fragmented rules quickly become binding constraints on investment, adding years to project timelines and raising costs. As such, modernising and simplifying regulatory frameworks have become a strategic lever of energy security and competitiveness.

Recent EU legislation, including the Renewable Energy Directive III, provides an important foundation. Implementation at national level, however, will determine whether projects proceed from pipeline to operation.

Across EU Member States, five recurring regulatory barriers consistently slow deployment and undermine system efficiency:

First, unclear or restrictive legal frameworks create uncertainty and deter market entry, particularly for newer solutions. Where rights and permitted uses have been clarified – such as enabling dual land use for both agriculture and PV solar in France and Italy – deployment has accelerated; where ambiguity persists, projects stall.

Second, insufficient remuneration for new system services limits investment, for instance in flexibility. Many frameworks still do not reward services such as inertia or fast frequency response on a standalone basis, despite their growing importance for system stability. Ireland’s recent market reforms to remunerate these ancillary services illustrate how rule changes can unlock these services.

Third, infrequent and inefficient spatial planning and permitting remain a major drag on investment. Complex, sequential procedures involving multiple authorities often result in long timelines distorting siting decisions and raising financing costs. Where procedures have been simplified, impacts have been immediate and significant: reform to grid-permitting rules in Germany have enabled the Federal Network Agency (BNetzA) to approve roughly four times more transmission-line kilometres in 2024–25 than in previous years (see figure 3).

Fourth, outdated grid-connection rules create artificial bottlenecks. First-come, first-served queues allow speculative projects to hold capacity delaying viable investments. Sweden’s readiness-based connection rules show how prioritisation can improve outcomes without new infrastructure.

Finally, grid-investment frameworks still contain structural disincentives that limit system optimisation. Regulation often favours capital-intensive network expansion while constraining anticipatory investment, flexibility procurement, and digital solutions. In some Member States, system operators cannot recover the costs for non-wire alternatives, even when these are faster and cheaper than traditional reinforcement.

These barriers can add years to project timelines and increase financing costs. They affect not only renewable developers but also energy-intensive industries, such as AI infrastructure and advanced manufacturing, that require stable, low-cost electricity to remain competitive.

To address these barriers systematically, the OECD has developed the Diagnostic Tool for Reducing Regulatory Barriers to Solar, Wind and Pumped Hydro Storage in the EU for the European Commission. The Tool helps policymakers at national and sub-national levels identify where rules are misaligned with system needs, prioritise reforms, and coordinate implementation – providing a practical roadmap for accelerating electrification while strengthening both energy security and competitiveness.

With clear rules, coordinated planning and tools such as the OECD Diagnostic Tool, the EU can move from energy dependence toward electric resilience – strengthening both economic competitiveness and energy security.

*We will be launching the Diagnostic Tool on 29th January. You may register here.

References

European Commission, 2024, Study on energy prices and costs – evaluating impacts on households and industry’s costs – 2024 edition

Draghi, M., 2024. The Future of European Competitiveness—A Competitiveness Strategy for Europe

IEA, 2025, Energy and AI, World Energy Outlook Special Report

IEA, 2023, Renewable Energy Market Update Outlook for 2023 and 2024

OECD, 2025, OECD–EU Diagnostic Tool for Reducing Regulatory Barriers to Solar, Wind and Pumped Hydro Storage

WindEurope and Hitachi, December 2025, Delivering a cost-effective energy system for Europe


The OECD Energy Support Measures Tracker: Looking back to move ahead

By Cassandra Castle, Assia Elgouacem, Giuliana Sarcina, Enes Sunel, and Jonas Teusch


In the past few years, the global economy has experienced two major crises: the COVID-19 pandemic and Russia’s war of aggression against Ukraine. The recovery from the pandemic and the war have both amplified tensions in the energy sector and provoked a surge in energy prices.

The fiscal response to the energy crisis has been large, especially in Europe

The 2023 OECD Energy Support Measures Tracker, released on 6 June 2023, shows that in 2022, support measures in response to higher energy prices had a gross fiscal cost of 0.7% of GDP in the median OECD economy, rising to over 2.5% of GDP in some European countries (Figure 1). By way of comparison, these costs exceed what the median OECD country spends on unemployment benefits and are about half of the expenditure on family and child benefits. Comparable levels of fiscal support are foreseen for 2023 in the OECD as a whole. However, the actual cost of support will heavily depend on the evolution of energy prices.

The 2023 OECD Energy Support Measures Tracker provides comprehensive data and information on energy-crisis related fiscal support measures

Documenting the measures governments have implemented to face the energy price shock and being able to compare them across countries, remains critical to improving support policies and building resilience against future crises. The 2023 Tracker systematically catalogues support measures in place from February 2021 to May 2023 in 41 countries – 35 OECD countries and 6 non-OECD economies (Brazil, Bulgaria, Croatia, India, Romania and South Africa).[1] The data have been collected and processed by OECD country, fiscal and energy policy experts and validated by national administrations.

The dataset provides granular information to comprehensively characterise individual support measures. These include start and end dates, gross fiscal costs, type of support and delivery mechanism, main beneficiaries of the measures (indicating whether vulnerable households or firms from specific sectors are targeted, and, where applicable, summary information on the differentiation of support between beneficiaries) and the impacted energy carriers (such as diesel, gasoline, electricity, natural gas). The sheer number and diversity of the measures makes classification challenging.

The 2023 Tracker classifies more than 550 support measures into two main categories: (1) price measures (e.g. reduced energy taxes and energy price caps), estimated to cost USD 422 billion in 2022-23; and (2) income measures (e.g. transfers and tax credits to consumers), estimated to total USD 383 billion in 2022-23. Within income measures, a distinction is made between measures that reduce the average price of energy in consumers’ energy bills and measures that are unrelated to the level of energy consumption (Figure 2).

The measures – which were implemented swiftly amidst uncertainty, political economy constraints, and a focus on administrative simplicity – affect the behaviour of firms and people in different and significant ways, and may contribute to or detract from important longer-term policy objectives. Income support can maintain incentives to save energy whereas price measures weaken them, propping up demand for fossil fuels and effectively acting as a negative carbon price. Among income measures, those that are unrelated to the level of energy consumption tend better to preserve incentives for energy efficiency improvements than those that reduce the average price in the energy bill paid by consumers.

Measures were rarely targeted and increased the incentive to consume fossil fuels

Untargeted support measures make up the majority of the estimated total cost of support in 2022-23 (Figure 3). Among these, energy price support measures account for over 50% of total spending and carry substantial non-fiscal implications. While price support measures are straightforward to design and often politically popular, they weaken incentives to save energy and are rarely targeted (over 92% of energy price support measures are untargeted), meaning that they tend to disproportionately support better-off households.

A clear taxonomy of measures and data can enable the design of better energy support policies when they are needed

Energy prices are receding, but possible renewed tensions in energy markets due to geopolitical developments and bottlenecks along the energy transition may result in higher energy price volatility in the future. Preparing government policy for possible new energy price spikes requires data and information on how support measures affect the behaviour of households and firms, their impact on public finances and their unintended consequences. The OECD Tracker is a resource for policymakers to do just that.

Interactive dashboard: Energy measures 2022/23


More information

OECD (2023), 2023 OECD Energy Support Measures Tracker, OECD database

OECD (2023), “Aiming Better: Government Support for Households and Firms During the Energy Crisis”, OECD Economic Policy Papers No. 32, OECD Publishing: Paris, https://doi.org/10.1787/839e3ae1-en


[1] The government of Iceland has not taken any energy support measures. The Tracker also includes information on another five countries, for which it was either not possible to quantify the gross fiscal cost of the energy support measures (Argentina, China, Hungary and Indonesia) or these were deemed to have no impact on budget deficits, as is the case of measures providing credit and equity support (Switzerland).

See also: 2026 OECD Energy Support Measures Tracker and accompanying blog: Crude Awakening:  Why energy shocks demand more than quick fixes.

The sharp rise in energy prices linked to the Middle East conflict is reviving a familiar policy dilemma. When energy costs jump sharply, governments come under pressure to shield households and firms. As of March 2026, governments across the OECD have acted swiftly to shield households and firms from rising fuel costs.


What are the economic and environmental effects of the European Union Emissions Trading Scheme?

By Daniel Nachtigall, OECD Environment Directorate and Antoine Dechezleprêtre, OECD Directorate for Science Technology and Innovation

The European Union (EU) put forward an ambitious climate mitigation target of reducing greenhouse gas (GHG) emissions by at least 55% below 1990 levels by 2030. How will the EU deliver? Carbon pricing – through the European Union Emissions Trading System (EU ETS) – is expected to deliver a large part of the emissions reductions. Under an ETS, installation operators can trade GHG emission permits with each other, ensuring that emissions are reduced cost-effectively. Launched in 2005, the EU ETS is the world’s first international ETS, covering over 14,000 energy-intensive plants across 30 European countries, accounting for around 40% of the EU’s total GHG emissions. From the outset the EU ETS raised concerns about its environmental effectiveness and potential negative economic effects for the European industry by putting regulated firms at a disadvantage vis-a-vis their foreign competitors.

A recent paper ‘The joint impact of the European Union emissions trading system on carbon emissions and economic performance’ published by OECD authors in the leading Journal of Environmental Economics and Management sheds light on this concern. Based on an earlier OECD working paper, the study is the first comprehensive, European-wide analysis of the impact of the EU ETS on both carbon emissions and economic performance of regulated companies during the first two phases of the system’s existence, from 2005 to 2012.

The study uses data for carbon emissions of installations from the national Pollutant Release and Transfer Registers (PRTR) of France, Netherlands, Norway and the United Kingdom, complemented with data from the European PRTR. It also includes economic data of firms for all European countries to investigate the impact of EU ETS on various economic dimensions, including employment, fixed assets, profits, and revenues. The study makes use of the EU ETS inclusion criteria, according to which installations below a certain capacity threshold do not need to participate in the carbon market. It compares installations or firms operating in the same country and the same sector and of similar characteristics, but which fall under different regulatory regimes since the launch of the EU ETS.

So what does the study tell us?

The EU ETS reduced emissions while not negatively affecting economic outcomes

The EU ETS led to a reduction of carbon emissions of around 10% between 2005 and 2012 but has not had any adverse impact on employment (see Figure 1). Most of the emissions reductions were observed in the second trading phase of the EU ETS and were primarily driven by larger installations. This is in line with the observation that pollution control technologies are capital-intensive and involve relatively high fixed costs. There is also evidence that a more generous allocation of free allowances results in a weaker reduction of emissions.

Figure 1. The impact of the EU ETS on jobs and CO2 emissions

Note: The graph shows the percentage change on CO2 emissions and number of employees by year of firms participating in the EU ETS versus those not participating.
Source: Based on Dechezleprêtre et al. (2018) and Dechezleprêtre et al. (2023)

The study also finds that the EU ETS has not had a negative effect on regulated firms’ revenue, profits, fixed assets and jobs. In fact, the EU ETS seemed to have led to an increase of revenues and fixed assets of regulated firms – contrary to what could have been expected. One explanation could be that the EU ETS induced regulated firms to increase investment – likely in carbon-saving technologies – which, in turn, may have increased productivity.

More research is needed to reflect more recent developments in carbon pricing

In its first eight years of existence, the EU ETS effectively reduced carbon emissions without negatively affecting the economic performance and competitiveness of European regulated firms. This is in line with recent literature reviews on the effects of carbon pricing on environmental and economic outcomes. While these results demonstrate that concerns about negative effects of the EU ETS on the competitiveness of the European industry have been vastly overplayed, more research is needed to assess these findings against new realities. In fact, the period between 2005-2012 was characterised by relatively low permit prices of EUR 20/tCO2 on average and a generous allocation of free allowances. From mid-2020, permit prices were fluctuating around EUR 80t/CO2, so it remains to be seen whether these findings hold true in a high price environment.

References:

This is in line with previous OECD work (OECD, 2021) and findings from recent literature reviews on the effects of carbon pricing on environmental and economic outcomes.

OECD (2021), Assessing the Economic Impacts of Environmental Policies: Evidence from a Decade of OECD Research, OECD Publishing, Paris, https://doi.org/10.1787/bf2fb156-en.

Dechezleprêtre, A., Nachtigall, D., & Venmans, F. (2023). The joint impact of the European Union emissions trading system on carbon emissions and economic performance. Journal of Environmental Economics and Management, 118, 102758. https://doi.org/10.1016/j.jeem.2022.102758.

Dechezleprêtre, A., D. Nachtigall and F. Venmans (2018), “The joint impact of the European Union emissions trading system on carbon emissions and economic performance”, OECD Economics Department Working Papers, No. 1515, OECD Publishing, Paris, https://doi.org/10.1787/4819b016-en.

This blog article was cross-posted on the OECD Environment Focus platform, which aims to increase dialogue on a variety of environmental topics among policy makers, experts and the general public.


Greece: Achieving the green economy transition

By Tim Bulman, Timo Leidecker and Ilai Levin, OECD Economics Department

More intense and more frequent wildfires and floods, hotter and drier summers, and disrupted seasons are among the striking signs that the climate in Greece and globally is changing. Like other OECD countries, Greece is contributing to the global effort to mitigate climate change by becoming a net zero emission economy.

Reducing emissions from energy use to transition towards a net-zero economy

The green economy transition poses a particular challenge for Greece. The economic crisis of the last decade has limited public and private financial capacity to invest in renewable energy production, make infrastructure more resilient, improve energy efficiency, upgrade heating systems, and replace fossil-fueled with zero emission cars. Using public funds effectively, mobilising private capital, and raising additional revenues will be key for Greece. The just-released OECD Economics Working Paper on “Transitioning to a green economy in Greece“, drawn from the OECD Economic Survey of Greece (2023) presents a mix of the policies required to limit the financial and social coss of the transition. Achieving the transition is feasible with little long-term cost to incomes and employment, especially if continued reforms to improve the business environment and raise investment accompany the transition (discussed in this ECOSCOPE post).

The Paper identifies three policy priorities that would make substantial cuts to the more than two-thirds of Greece’s emissions that come from energy use:

1. Pricing greenhouse gas emissions consistently to encourage investment, innovation and savings. Average CO2 prices from using fossil fuels are high in Greece but vary substantially across uses. For example, charges on CO2 emissions from using gasoline are effectively double those from diesel; in turn, charges for using fossil fuels for heating or producing electricity are much lower than average charges for using fossil fuels for road transport. Introducing a minimum price floor to harmonise prices would encourage low-cost ways to cut emissions. Higher and more consistent prices for emissions would also generate more than enough revenues to compensate low-income households for rising living costs.

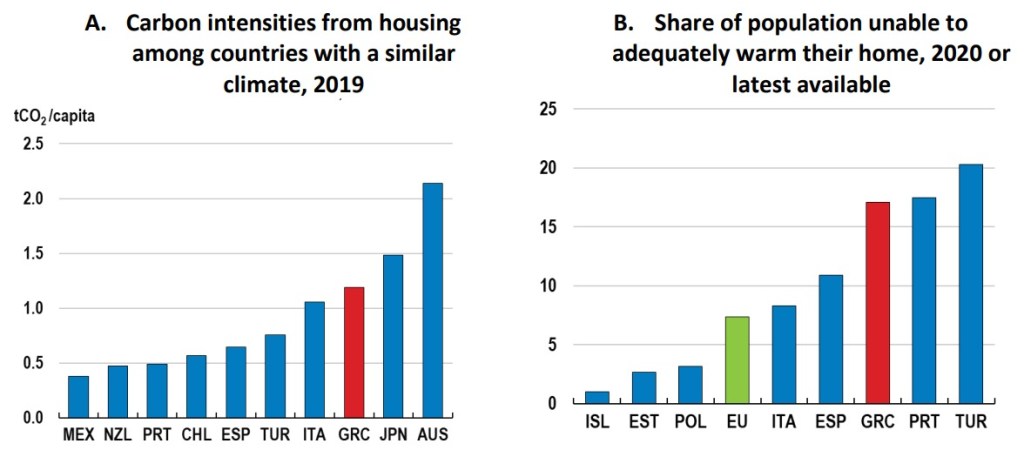
2. Giving a push to renovate buildings. Greece has an old housing stock with low energy efficiency. This harms residents’ well-being, especially when energy prices are rising, as experienced over the past year. It also contributes to high greenhouse gas emissions in Greece compared to countries with similar climates (Figure 1). Housing renovations can cut emissions, improve residents’ comfort, and usually pay for themselves through energy savings. The up-front costs of renovations, however, can be a major barrier to realising these savings. Substantially expanding the current financial support programmes and – to leverage more private financing – encouraging loans that are repaid through energy savings would boost renovations. Setting out a clear timeline of increasing minimum energy-efficiency standards to cover both new and existing buildings would provide certainty for investors and builders, bringing more resources to renovations and create green jobs.

Figure 1. Improving housing energy efficiency would reduce emissions and energy poverty

3. Moving transport onto low-emission modes. Cutting emissions from transport is costly and complex but, as it generates one-fifth of Greece’s total emissions, is central to Greece’s goals. More passengers and freight are carried on roads than in the EU on average. The car fleet is large and old, with Greeks spending less on buying cars than in most other OECD countries (Figure 2). Renewing the car fleet, especially with more expensive low-emission cars, is likely to be very slow, even if purchase subsidies were used more extensively. At the same time, modelling by the International Transport Forum and the OECD finds that improving public transport could cut transport emissions in Greece by 19% in 2030 relative to 2019 levels with an additional investment of about 0.2% of GDP annually.

Figure 2. Alternatives to road transport could cut emissions from transport cost effectively

Helping people and businesses adapt to the changing climate

Transforming the economy to net-zero emissions will affect how firms operate and which skills are needed. As some jobs bound to fossil fuels disappear, for example in lignite mining, new and potentially higher productivity job opportunities will be created, for example in housing renovations or greener technologies. Workers may need to up-skill for these new jobs, especially in regions highly dependent on fossil fuel industries such as Western Macedonia. Focused interventions such as those underway in Greece’s lignite mining areas are increasing access to quality training. and help hasten this transition and support incomes.

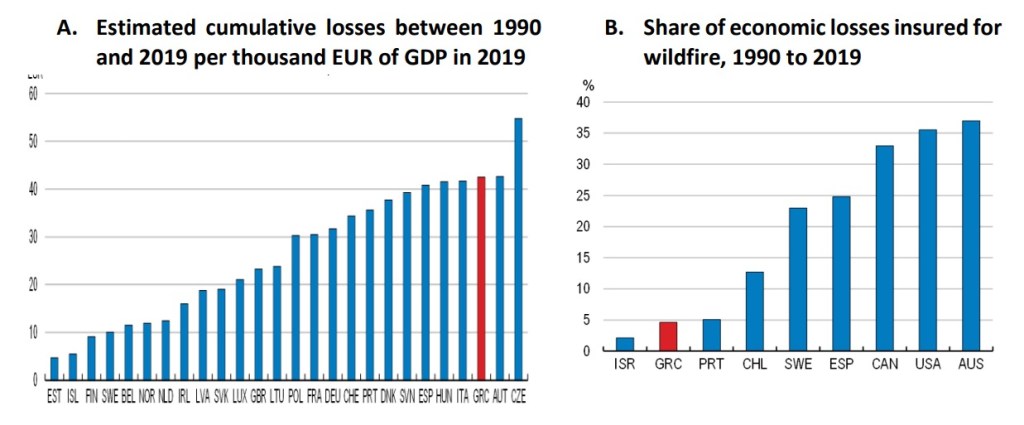
Damages from extreme weather events, such as wildfires or floods, are already mounting in Greece and are likely to further aggravate. Encouraging households and firms to anticipate these risks when they decide where and what to build will help reduce the disruption from a changing climate. Private insurance can help make the costs of climate-related risks clearer. Yet, insurance coverage in Greece is among the lowest in OECD countries (Figure 3). After past natural disasters the government has partly compensated damages, but this leaves people uncertain about how much and when they will receive compensation and weighs on public finances. Making insurance coverage compulsory could encourage people to take protective measures upfront, would leverage the skills of the private sector to assess reconstruction costs, and provide greater certainty to those afflicted. Public re-insurance, and ensuring that insurance markets remain competitive, can improve the accessibility of insurance.

Figure 3. Expanding insurance coverage would improve compensation for damages and encourage households and firms to minimise their exposure to a changing climate

Reference:

OECD (2023), OECD Economic Surveys: Greece 2023, OECD Publishing, Paris, https://doi.org/10.1787/c5f11cd5-en.

Leidecker, T., et al. (2023), “Transitioning to a green economy in Greece”, OECD Economics Department Working Papers, No. 1757, OECD Publishing, Paris, https://doi.org/10.1787/77cd54d8-en.


Rising energy prices and productivity: short-run pain, long-term gain?

By Christophe André, Hélia Costa, Lilas Demmou, Guido Franco, OECD Economics Department

Rising energy prices resulting from the strong post-COVID19 economic recovery and the war in Ukraine threatened to derail the post-pandemic recovery. Beyond exogenous price changes, increasing reliance on environmental policies to achieve climate change goals has also meant that energy prices have been on an increasing trajectory and will probably continue to be. Coal, natural gas and electricity are critical inputs to production in various sectors and an increase in their price can strain firms’ profitability. High energy prices could also deter investment, undermining firms’ productivity and competitiveness even further.

Policymakers may push towards temporarily shielding corporations from energy price shocks to preserve their economic performance and industrial jobs, at the expense of blurring the price signal needed for the green transition. To design policies that reconcile the two goals of providing firm support when faced with energy price increases and promoting the green transition, it is key to understand the conditions under which the impacts of energy price increases on firms materialise.

Against this backdrop, our new paper (André et al. 2023) uses historical cross-country firm-level data to estimate the impacts of energy price changes on firm productivity, a key driver of firms’ performance. We distinguish between the short- and the medium- term impact, by explicitly modelling the dynamics of gains and costs, on which the current literature is limited. Our analysis relies on newly updated measures of sectoral energy prices estimated through country-level prices and sectoral energy mixes, based on Sato et al. (2019), allowing us to explore country-industry-year variation in energy prices.

How do energy prices affect firms’ productivity?

Following an energy price shock, firms adjust their capacity utilisation, affecting their productivity. Specifically, our estimates suggest that a 5% increase in energy prices reduces productivity by approximately 0.4% one year later. The firms most affected are those operating in energy-intensive sectors, as well as firms that are financially constrained or small. This impact is also contingent on macroeconomic conditions: for example, when a country’s economy runs above potential (i.e., has a positive output gap), energy price increases have a less negative impact in the short term.

However, this impact changes over time, and firms may display positive productivity gains in the medium term. In particular, a shock corresponding to a 10% increase in energy prices is associated with an increase in productivity growth of around 0.9 p.p. four years after the shock. These gains are more likely in less energy-intensive sectors and for firms that are more likely to invest in newer, more energy-efficient capital. In addition, they are less likely to materialise in the case of more severe shocks.

Figure 1. The medium-term response of productivity to energy price shocks

Panel A: The thick black line represents the average change in firms productivity growth following a 10% energy price shock. Panel B: The blue solid (green dashed) line represents the average change in firms productivity growth following a 10% energy price shock in high (low) energy intensity sector. The shaded area represents the 90% confidence interval around the estimates.

Our analysis offers some indications that investment could be a channel through which this sign reversal operates. Energy price shocks are more likely to affect productivity positively when coupled with favourable conditions for investment to take place, as for example in countries with more stringent environmental policy, where managers are more likely to be aware of energy efficiency technologies. Conversely, in environments of large economic policy uncertainty, firms face lower scope for productivity gains as they are likely to delay irreversible investment including energy efficiency investment.

These results offer insights into policies for promoting firm performance and avoiding the risks of productivity stagnation, while encouraging the green transition. First, governments could incentivise firm-level decarbonisation by letting price signals on fossil fuel energy operate, especially in expansionary periods of the business cycle when the cost of adjustment is lower. Further, the analysis outlines several directions to establish a green-investment-friendly environment, for example by easing access to finance, reducing policy uncertainty, improving predictability of retail electricity prices, and increasing awareness of environmentally related challenges and solutions through environmental policy. Finally, this work suggests that in the case of severe shocks, like the one experienced last year, costs are likely to be high and persistent. To reduce scars for the corporate sector, some support to vulnerable but productive firms may be needed, especially for small and financially constrained firms which are the most at risk.

References:

André, Christophe; Costa, Hélia; Demmou, Lilas; Franco, Guido, 2023. Rising energy prices and productivity: short-run pain, long-term gain?, OECD Economics Department Working Paper, no 1755, OECD Publishing, Paris, https://doi.org/10.1787/2ce493f0-en.

Sato, Misato; Singer, Gregor; Dussaux, Damien; Lovo, Stefania, 2019. International and sectoral variation in industrial energy prices 1995–2015. Energy Economics, 78, issue C, p. 235-258.


Confronting the energy crisis: changing behaviours to reduce energy consumption

By Francesca Papa and Filippo Cavassini, OECD Economics Department

Russia’s war of aggression against Ukraine is strongly impacting energy prices worldwide. While relatively mild weather avoided rationing over the 2022-23 winter in European countries, challenges remain in securing sufficient storage levels for the 2023-24 winter (OECD, 2023). In some countries, high prices have already incentivised some demand reductions from firms and households. However, as argued in our recent paper (Cavassini and Papa, 2023), the crisis calls for additional changes in behaviour to accompany long-term technical and structural solutions to lower gas and electricity demand.

The current energy crisis calls for significant changes in behaviour

Diversifying energy sources and reducing energy demand will be critical. Some of these changes will take time to be implemented, such as improving buildings’ energy efficiency. However, the current crisis also calls for policies leading to more immediate demand reduction (Haas, Kozluk and Sarcina, 2022) (Figure 1).

Figure 1. Without demand reductions, Europe may risk gas supply interruptions

Note: For all scenarios, assuming 90% storage levels at the end of November; no imports from Russia from November 2022 and domestic production at average 2019-2021 levels. In the baseline, we assume “10% reduction” in gas demand relative to the 2017-21 average consumption, imports from other sources at 28 bcm/month, of which 13.5bcm/month from LNG imports. “Cold winter” assumes consumption at the maximum 2017-21 levels, a 10% reduction in gas demand relative to the maximum 2017-2021 levels and imports from other sources, incl. LNG imports, as the baseline. Low LNG imports assumes 12bcm/month of LNG imports starting from 2023 and a 10% reduction in gas demand relative to the 2017-21 average consumption.
Source: Update of OECD Ecoscope Blog (Haas, Kozluk and Sarcina, 2022[2]) .

Some of these actions will need to come from changes in the behaviour of households, which account for almost 24% of energy consumption in the EU, with an even higher share in winter (OECD, 2022) (Figure 2).

Figure 2. Households account for a large share of electricity consumption

Electricity total final consumption by sector
1971-2018 (Mtoe)

Notes: Other includes agriculture, fishing and non-specified sectors.
Source: (IEA, 2021).

Reducing households’ energy use can not only help curb the current crisis, but, if sustained over time, it can also support the transition to net zero. Identifying the psychological factors that influence energy conservation behaviour is particularly important, because changing behaviour is the result not only of responses to prices but also of expectations, habits, and biases (Carrus, 2021).

How to facilitate a behavioural response to energy savings?

A range of structural and psychological barriers make it hard for consumers to change their energy consumption. For example, inattention, sheer habit or emulation can create a gap between the intention to reduce energy consumption – I will turn off the light when I exit the room – and the actual action – but in fact I leave it on. The capacity of individuals to process information can also be a barrier. Information campaigns that are not sufficiently clear on what can be done can be difficult to act upon.

There are, however, ways of counteracting these behavioural barriers.

Successful information campaigns tend to provide a set of clear and actionable guidelines, which can be important for emergency situations (Cornago, 2022). For example, after the 2011 earthquake and tsunami hit the Fukushima nuclear power plant in Japan, the government launched an information campaign to encourage households to save energy. Government and energy utilities disseminated checklists of energy saving tips with simple actionable steps, complemented by technical support to commercial and industrial consumers (Institute of Energy Economics, Japan, 2021). Overall, the campaign led to 15% less electricity being used in 2011 relative to the previous year in the most affected regions. This was achieved without price increases (Kimura and Nishio, 2016).

Social norms are strong determinants of action and can influence the effectiveness of information campaigns. For example, a study on the role of beliefs in energy conservation found that the belief that neighbours were reducing energy consumption correlated highly with energy saving efforts, a finding which has often replicated in real-life applications (e.g. Figure 3) (Jachimowicz, 2018).

Figure 3. Sample of redesigned energy bill emphasising social comparison

Source: (Jachimowicz, 2018[9])

Behavioural change can also be promoted through a combination of price mechanisms (time of the day pricing) and user-centric technologies. A study conducted by the OECD in 2018 showed that smart meters providing real-time feedback on electricity consumption, price and expenditures induced households to reduce electricity demand by an average of about 3%, with results increasing to around 4% over a five-month period (OECD, 2019).

Table 1 presents possible responses that build on behavioural sciences and can be used to counteract different behavioural barriers affecting energy consumption.

Table 1. Examples of behavioural barriers that can affect energy consumption in the short and long term and possible responses

Source: OECD elaboration from (Andor and Fels, 2018), (Feygina, 2010), (Gifford, 2011), (Mol, Jantsje M., et al., 2020), and (OECD, 2019b).

Conclusions

Governments should already concentrate on energy saving measures that will prepare us for the next winter. The choice of message that policymakers send to consumers, how and when the information is provided to households and through which channels can make a difference in changing consumption behaviours. The effectiveness of these campaigns and actions should be monitored to gauge evolutions in behaviours and identify solutions to behavioural barriers.

References:

Andor, M. (2018), Behavioral economics and energy conservation–a systematic review of non-price interventions and their causal effects, Ecological economics 148 (2018): 178-210. https://www.researchgate.net/publication/331999076_Behavioral_Economics_and_Energy_Conservation_-_A_Systematic_Review_of_Non-price_Interventions_and_Their_Causal_Effects.

Carrus, G. (2021), Psychological predictors of energy saving behavior: A meta-analytic approach., Frontiers in Psychology, 12, 648221. https://www.frontiersin.org/articles/10.3389/fpsyg.2021.648221/full.

Cavassini F. and Papa F. (2023), “Confronting the energy crisis: changing behaviours to reduce energy consumption“, OECD Policy Responses on the Impacts of the War in Ukraine. Available at: https://www.oecd.org/ukraine-hub/policy-responses/confronting-the-energy-crisis-changing-behaviours-to-reduce-energy-consumption-5664e8a9/#back-note-d1e350.

Cornago, E. (2022), HOW TO SAVE ENERGY IN A SMARTER WAY, Center for European Reform. https://www.cer.eu/insights/how-save-energy-smarter-way.

Feygina, I. (2010), System justification, the denial of global warming, and the possibility of “system-sanctioned change”., Personality and social psychology bulletin, 36(3), 326-338. https://journals.sagepub.com/doi/abs/10.1177/0146167209351435.

Gifford, R. (2011), The dragons of inaction: psychological barriers that limit climate change mitigation and adaptation., American psychologist, 66(4), 290. https://psycnet.apa.org/doiLanding?doi=10.1037%2Fa0023566.

Haas, Kozluk and Sarcina (2022), Emergency plans and solidarity: Protecting Europe against a natural gas shortage, OECD Ecoscope. https://oecdecoscope.blog/2022/10/21/emergency-plans-and-solidarity-protecting-europe-against-a-natural-gas-shortage/.

IEA (2021), Electricity total final consumption by sector, 1971-2019, IEA, Paris https://www.iea.org/data-and-statistics/charts/electricity-total-final-consumption-by-sector-1971-2018, IEA. Licence: CC BY 4.0.

Institute of Energy Economics, Japan (2021), CERT Thematic Discussions: The role of ʻbehavioural aspectsʼ for reaching net zero emissions by 2050, https://iea.blob.core.windows.net/assets/d65c0edb-50fc-46e4-90db-d7df8933af4d/1.Naoko_DOI_ImpactofSetsuden.pdf.

Jachimowicz, J. (2018), The critical role of second-order normative beliefs in predicting energy conservation., Nat Hum Behav 2, 757–764 (2018). https://doi.org/10.1038/s41562-018-0434-0.

Kimura, O. and K. Nishio (2016), Responding to electricity shortfalls: Electricity-saving activities of households and firms in Japan after Fukushima., Economics of Energy & Environmental Policy, 5(1), 51–72. https://www.jstor.org/stable/26189398.

Mol, Jantsje M., et al. (2020), Insights into flood risk misperceptions of homeowners in the Dutch River Delta., Risk analysis 40.7 (2020): 1450-1468. https://onlinelibrary.wiley.com/doi/full/10.1111/risa.13479.

OECD (2023), OECD Economic Outlook, Interim Report March 2023: A Fragile Recovery,, OECD Publishing, Paris, https://doi.org/10.1787/d14d49eb-en.

OECD (2022), Emergency plans and solidarity: Protecting Europe against a natural gas shortage, OECD, Paris. https://www.oecd.org/economy/outlook/Briefing-Note-Gas-Emergency-Plans-and-Solidarity.pdf.

OECD (2019), Delivering Better Policies Through Behavioural Insights: New Approaches,, OECD Publishing, Paris, https://doi.org/10.1787/6c9291e2-en.

OECD (2019b), Tools and Ethics for Applied Behavioural Insights: The BASIC Toolkit, OECD Publishing, Paris, https://doi.org/10.1787/9ea76a8f-en.

Acknowledgments

Valuable comments, inputs and support were received from colleagues across the OECD Economics Department: special thanks go to Tomasz Kozluk; Mauro Pisu; Enes Sunel; Filippo Maria D’Arcangelo; Tobias Kruse; Jonas Teusch; Fátima Talidi and Jesús Calderón Argüello. The authors gratefully acknowledge Cassandra Castle for her important contributions. Isabell Koske, Acting Director, Country Studies, Economics Department, provided guidance and inputs to the policy brief. Antonia Vanzini prepared the blog for publication.


Energy expenditures have surged, posing challenges for policymakers

By Geoff Barnard and Patrice Ollivaud, OECD Economics Department

The estimated ratio of energy expenditures to GDP in OECD economies surged in 2022. The prices of oil, natural gas, electricity and coal had already risen strongly during 2021, and soared further after Russia’s invasion of Ukraine in February 2022. Even though by the end of 2022 prices had fallen well below their intra-year highs, for the year as a whole all four energy components contributed to the estimated increase in the OECD-wide expenditure-to-GDP ratio relative to 2021: 2½ percentage points of GDP for electricity, 2¼ for crude oil and oil products, 2 for natural gas and 1 for coal.

It is possible that the 2022 energy-expenditure estimates are somewhat overstated. First, full-year volumes are not yet known and are assumed to be equal to the average of 2019 and 2021 (leaving out the COVID-affected year of 2020). However, in some cases, such as gas and electricity consumption in Europe, high prices have been curtailing consumption in recent months. Moreover, end-user prices for 2022 are not yet available and have therefore been proxied by wholesale prices. To the extent that retail prices have been held down by government policies and/or that industrial users buy energy under long-term price contracts, actual end-user prices and expenditure may have risen by less than suggested by wholesale prices. Nonetheless, it is clear that expenditures on energy as a proportion of GDP will have risen rapidly, and to a high level, in 2022, both in the OECD as a whole and in the typical economy.

Experience suggests that this represents a warning about the potential risk of recession in OECD economies in 2023. Over the past 50 years, the share of incomes in OECD economies taken up by energy expenditures has been closely related to the incidence of economic downturns (Figure 1). As shown in the latest OECD Economic Outlook (OECD, 2022), end-use expenditures on energy in the OECD have been high and rising whenever an OECD-wide recession has occurred since 1970, with the sole exception of the pandemic-affected year of 2020. There were surges in energy expenditures during the first (1973-74) and second (1979-80) oil crises in many countries, both of which preceded an OECD-wide recession, while the global financial crisis occurred at the culmination of an upward trend in energy expenditures that began in the early-2000s, reaching 13% in 2008. The surge in energy expenditures seen in 2022 is thus a cause for concern.

The association between energy expenditures and the economic cycle is readily explicable: with energy an important input for firms, a rise in energy prices may represent an adverse supply shock, lowering output and raising the price level. At the same time, higher energy prices erode the purchasing power of households. While there are winners from higher energy prices, their propensity to spend their windfalls is typically low (Cookson et al., 2022), so that the net effect on aggregate demand is negative.

Figure 1. Periods of high energy expenditures are often associated with a recession

Estimated energy end-use expenditures for the OECD economies

Note: Recessions (shaded areas) correspond to years in which there were at least two quarters of negative GDP growth for the OECD aggregate. Estimates of the level of energy expenditure, computed as end-use prices in local currency multiplied by volumes consumed, are produced at the country level for 29 OECD countries. GDP shares are aggregated using moving GDP weights in PPP terms. End-use prices include taxes. Prices, which start in 1978 in the IEA database, were backcast to 1971 using the Brent price for oil, prices for coal products and natural gas and the rate of increase of the electricity price in the US CPI for electricity. Prices are extended to 2022 using the growth rate of reference prices converted in local currency (average of observed 2022 data compared to 2021): Brent for oil, ICE Newcastle futures for coal, and wholesale prices for electricity and natural gas (available for 25 and 27 OECD countries, respectively).
Source: International Energy Agency; OECD Economic Outlook 112 database; US Energy Information Administration; Japanese Power; German Federal Network Agency (SMARD); Korea Electric Power Statistics Information System; Canada Independent Electricity System Operator; and OECD calculations.

There are, however, some differences with previous episodes of sharp increases in energy expenditure. First, past surges in the expenditure-to-GDP ratio were mostly driven by oil, while this time the contributions are more evenly spread across energy sources. If the link to economic activity is stronger for oil than for the other energy components, this might mean that the negative growth impact is smaller than for past energy expenditure shocks of similar size. The impact on particular countries will also differ from the past depending on their endowments of the various energy components: for example, net exporters of natural gas, including the United States, are likely to suffer less of a negative impact from the current energy price spike than in the past.

Second, because the market for oil (as well as coal) is much more global than those for electricity and gas, the incidence of the OECD-wide energy price increase is more regionally focussed than in the past, with most European economies particularly severely affected. The recession signal may therefore turn out to be more regional than global on this occasion.

Finally, the energy intensity of OECD economies (defined as energy consumed per unit of GDP) has trended down over the past five decades (Figure 2), reflecting rising energy efficiency. A large part of this downtrend is driven by oil and coal; the use of natural gas intensified until the end of the 1990s, when it stabilised, while electricity intensity has remained relatively constant. The downtrend in energy intensity is often masked by swings in the relative price of energy. For example, energy intensity fell by nearly 15% from the mid-1990s to the early 2000s, but energy expenditures remained roughly stable in relation to GDP because of an offsetting increase in the relative (weighted) price of energy. And the spike in the expenditure-to-GDP ratio in 2022, reflecting the unprecedented rises in some energy prices, obscures the ongoing decline in energy intensity. To the extent that OECD economies have become less energy intensive, the impact of an energy price shock on output may be expected to be smaller than in the past.

Bearing these differences in mind, the latest OECD Economic Outlook projections do not show a global or OECD-wide recession in 2023. A sharp slowdown is, however, expected in Europe – GDP growth for the euro area is projected to decline from 3.3% in 2022 to 0.5% in 2023, with quarterly output declines projected in several European countries. In addition, the Economic Outlook points to a range of downside risks, including the risk that the impact of lower energy imports to Europe from Russia is more severe than expected.

Figure 2. Energy intensity has declined, especially for oil and coal

Energy volume consumed per unit of real GDP, index, 2015=100

Note: OECD aggregate computed using energy intensity for 33 OECD countries weighted by GDP (PPP).
Source: OECD Economic Outlook 112 database; International Energy Agency.

References:

OECD (2022), OECD Economic Outlook, Volume 2022 Issue 2, OECD Publishing, Paris.

Cookson, J., E. Gilje and R. Heimer (2022), “Shake Shocked: Cash Windfalls and Household Debt Repayment”, Journal of Financial Economics, Vol. 146, Issue 3.


What role for carbon pricing in reducing emissions and generating revenues?

By Filippo Maria D’Arcangelo, Mauro Pisu (OECD Economics Department), and Anasuya Raj, Kurt Van Dender (OECD Centre for Tax Policy and Administration)

Limiting global warming and avoiding its potentially catastrophic damages hinges on reaching net-zero emissions by mid-century (IPCC, 2022). Achieving this ambitious global target requires a wide range of mitigation policies to overcome market failures, path dependencies and coordination problems (D’Arcangelo et al., 2022).

Carbon pricing can play an important role in a well-coordinated mitigation policy mix for two main reasons. First, in many instances, carbon pricing can induce lower emissions at lower economic costs than alternative mitigation policies. Second, it can generate additional government revenues, at least until emissions start falling appreciably.

Available evidence on the responsiveness of CO2 emissions and government revenues to carbon pricing is fragmented and difficult to compare across countries and sectors. Thus, tracking and comparing countries’ progress towards emission reduction targets and assessing the contribution of carbon pricing to emission reductions is challenging. We tackle this challenge in our recent paper, Estimating the CO2 emission and revenue effects of carbon pricing: new evidence from a cross-country dataset.

The paper provides fresh evidence on the long-run responsiveness of CO2 emissions and government revenues to carbon pricing within a unified framework across countries, sectors and fuels. The analysis relies on the OECD Effective Carbon Rates (ECR) database, containing comprehensive and detailed information on instruments pricing carbon emissions from energy use in 44 OECD and G20 countries. The ECR database contains data on carbon taxes, permit prices resulting from emissions trading systems, and fuel excise taxes and covers about 80% of global CO2 emissions from energy use.

Broad-based carbon pricing is an effective measure to reduce emissions in most sectors and will accelerate coal phase-out

Baseline estimates suggest that a EUR 10 per tonne of CO2 increase in carbon prices decreases CO2 emissions from fossil fuels by 3.7% on average in the long term. Policy simulations indicate that introducing a EUR 60 per tonne of CO2 global carbon price floor (about three times the 2018 average effective carbon rate) would lower total CO2 emissions from fossil fuels by about 17% compared to 2018 levels, after firms and people have fully adjusted to the increase in ECRs. This is a sizeable reduction in emissions but far from what is required to reach net-zero.

Estimates of the responsiveness of CO2 emissions to carbon pricing vary across sectors and fuels. For example, emissions in the buildings sector are about three times less responsive to carbon pricing than those in the agriculture and fisheries sector. Increasing carbon prices can be expected to have the largest effects on emissions from the Electricity and Industry sectors (Figure 1) due to a confluence of factors: the low carbon prices these sectors still face in most countries; their high emission responsiveness compared to other sectors; and their large share in total emissions. A high price floor in the Road transport sector, where effective carbon rates are already elevated due to excise taxes, would also contribute substantially to reducing emissions.

Emissions from coal are more responsive to carbon pricing than those from all other types of fossil fuels. Even mild, broad-based carbon prices would contribute significantly to coal phase-out, given its high responsiveness to carbon pricing: a floor of EUR 60 per tonne of CO2 can be expected to reduce global emissions from coal by half.

Figure 1: Effect of different ECR floors on emissions by sector

Note: Simulations of the effect on CO2 emissions (y-axis) of a global ECR floor applied to all emissions priced in 2018, by EUR 5 increments (x-axis)

Broadening carbon pricing to unpriced emissions has large effects on emissions and revenues in some countries

Moderate increases in carbon pricing would initially translate into large government revenue increases, as carbon prices are still generally low. Globally, carbon-related revenues could triple, relative to 2018 levels, with a EUR 60 global carbon price floor. Over time, if carbon price floors keep on increasing, these carbon-related revenues would dwindle in tandem with the reduction of emissions.

The broadened coverage of carbon pricing to currently unpriced emissions would contribute to around two thirds of the total estimated effects on emissions and revenues. Emission-intensive countries that do not yet price a large share of their emissions would observe a larger reduction in emissions and greatly contribute to the increase in fiscal revenues.

Figure 2: Impacts of a EUR 60 ECR floor on carbon-related revenues

Note: Red bars: Carbon-related government revenues observed in 2018; Green bars: effect of a EUR 60 carbon price floor on revenues through emissions already priced in 2018; Blue bars: effect of a EUR 60 carbon price floor on revenues through emissions not priced in 2018.

Easing the substitution of clean energy sources for fossil fuels requires policies complementary to carbon pricing

The estimated responsiveness of emissions to carbon pricing suggests that even large carbon prices (about EUR 1000 per tonne by late 2030s) will not suffice to meet net-zero emission targets.

Complementing steady but moderate increases in ECRs with policies that markedly increase the emission responsiveness to carbon pricing is crucial to put emissions on a downward path towards net-zero targets. In this respect, innovation and reallocation-friendly policies have a major role to play, as they can ease the substitution of clean energy sources for fossil fuels, thus reducing emission abatement costs and making carbon price more effective. For instance, policy simulations show that an emission responsiveness twice as large as the baseline estimate, combined with an ECR floor of EUR 40 on priced and unpriced emissions, would result in the same emission reduction as the baseline responsiveness estimates combined with an ECR floor of EUR 175 on priced emissions and EUR 60 on unpriced emissions.

References

D’Arcangelo, F.M., Ilai Levin, Alessia Pagani, Mauro Pisu, and Åsa Johansson (2022), “A framework to decarbonise the economy”, OECD Economic Policy Papers, No. 31, OECD Publishing, Paris, https://doi.org/10.1787/4e4d973d-en.

IPCC, 2022: Climate Change 2022: Mitigation of Climate Change. Contribution of Working Group III to the Sixth Assessment Report of the Intergovernmental Panel on Climate Change. Cambridge University Press, Cambridge, UK and New York, NY, USA. doi: 10.1017/9781009157926.